Middle East Halal Food Market Report by Product, Distribution Channel, Countries and Companies Analysis 2026-2034
Buy NowMiddle East Halal Food Market Size and Forecast
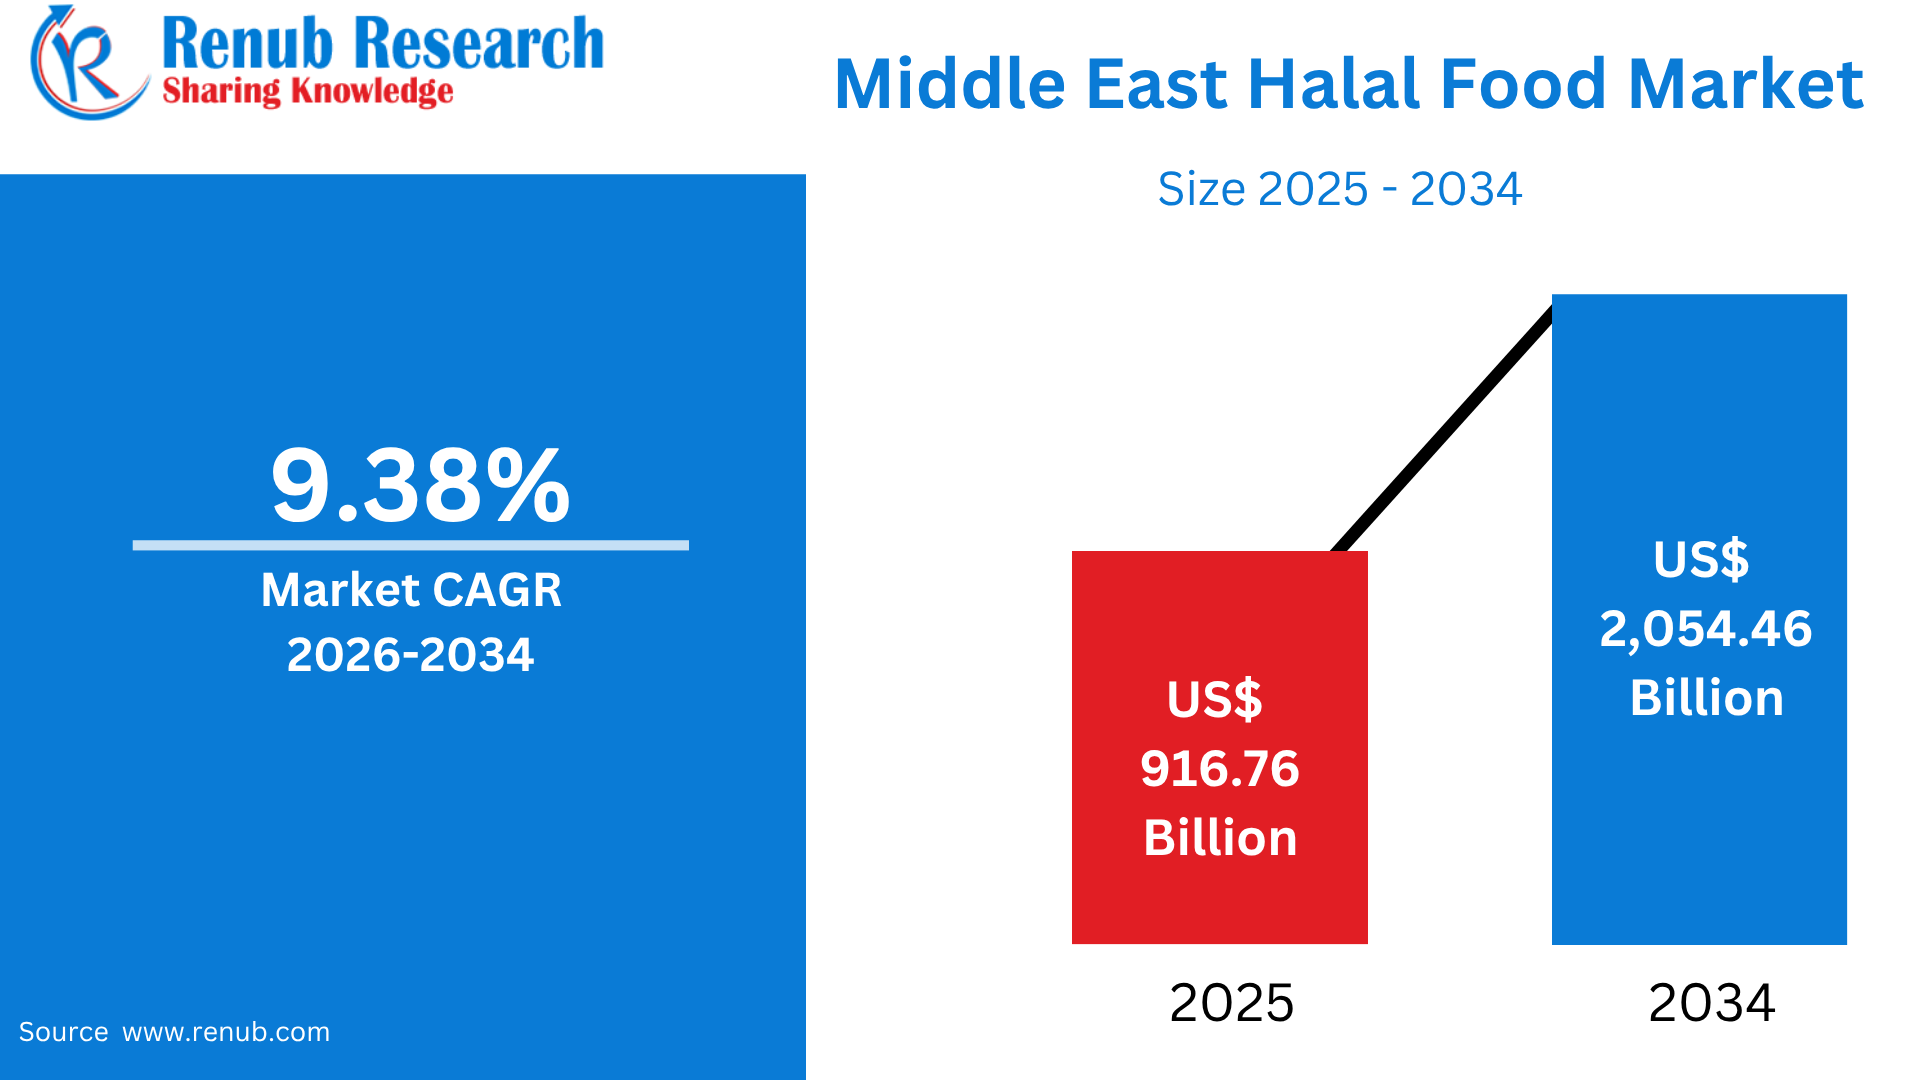
Middle East Halal Food Market is projected to grow from US$ 916.76 billion in 2025 to US$ 2,054.46 billion by 2034, registering a Compound Annual Growth Rate (CAGR) of 9.38% during 2026–2034. Market expansion is supported by the region’s predominantly Muslim population, increasing consumer preference for halal-certified food products, and government initiatives promoting food security and domestic food production. In addition, rapid urbanization, rising tourism activity, and the expansion of modern retail and foodservice infrastructure are creating new opportunities for halal food manufacturers and suppliers across the Middle East.
What is Halal Food and Its Uses & Popularity in the Middle East
Halal food refers to food and beverages that comply with Islamic dietary principles governing ingredients, preparation, processing, handling, and consumption. The term halal means permissible, while products containing pork, alcohol, blood, or other prohibited ingredients are excluded. For meat and poultry, halal requirements also cover the prescribed slaughtering process and prevention of cross-contamination. In the Middle East, halal food is deeply integrated into everyday consumption and is widely available across households, supermarkets, restaurants, hotels, catering services, and food-delivery platforms. Major categories include meat and poultry, seafood, dairy, bakery products, confectionery, beverages, processed foods, and ready-to-eat meals.
The market’s popularity is supported by the region’s large Muslim consumer base and strong cultural acceptance. Saudi Arabia alone recorded SAR 339.7 billion in Muslim consumer spending on halal food in 2023, according to its 2024/25 The Halal Products Development Company's 2024/25 report. Halal certification is also increasingly associated with food safety, hygiene, traceability, and ethical sourcing, broadening demand beyond purely religious considerations.
Muslim Population by Region: 2010 vs. 2030
- Worldwide: The global Muslim population was 1.62 billion in 2010, representing 100% of the world’s Muslim population. It is projected to reach approximately 2.19 billion by 2030, maintaining a 100% global share.
- Asia-Pacific: The region had around 1.01 billion Muslims in 2010, accounting for 62.1% of the global Muslim population. By 2030, the population is projected to increase to approximately 1.30 billion, although its global share is expected to decline to 59.2%.
- Middle East–North Africa (MENA): The Muslim population stood at approximately 216.87 million in 2010, representing 19.9% of the global total. By 2030, it is projected to reach 439.45 million, with its global share increasing slightly to 20.1%.
- Sub-Saharan Africa: The region recorded approximately 242.54 million Muslims in 2010, equivalent to 15.0% of the worldwide Muslim population. This figure is projected to rise to 385.94 million by 2030, increasing its global share to 17.6%.
- Europe: Europe had approximately 44.14 million Muslims in 2010, accounting for 2.7% of the global Muslim population. By 2030, the Muslim population is projected to reach 58.21 million, while its global share remains around 2.7%.
- Americas: The Muslim population in the Americas was approximately 5.26 million in 2010, representing 0.3% of the global total. By 2030, it is projected to more than double to 10.93 million, increasing its global share to 0.5%.
Pew Research Center
Growth Drivers of the Middle East Halal Food Market
Large Muslim Consumer Base and Strong Religious Demand
The predominantly Muslim population across the Middle East provides a structurally strong consumer base for halal food. Unlike many discretionary food trends, halal compliance is closely connected to religious dietary requirements, creating consistent demand for certified meat, poultry, dairy, packaged foods, and restaurant meals. Market research estimates that more than 500 million Muslims reside across the broader Middle East, supporting substantial recurring consumption of halal products. Saudi Arabia demonstrates the scale of this demand: Muslim consumers in the country spent approximately SAR 339.7 billion on halal food in 2023, according to the Saudi Arabia Halal Market Overview 2024/2025. Increasing consumer awareness of certification, ingredient transparency, hygiene, and ethical sourcing is further strengthening demand. In addition, halal requirements are increasingly incorporated into modern food manufacturing, retail, and foodservice operations, enabling consumers to access compliant products through supermarkets, convenience stores, restaurants, hotels, and online platforms.
Government Support for Halal Production and Food Security
Government initiatives across Middle Eastern countries are encouraging domestic halal food production, certification, supply-chain development, and food security. Saudi Arabia, in particular, is positioning halal production as part of its broader economic diversification strategy. Its Halal Products Development Company (HPDC) is focused on developing the domestic halal ecosystem and supporting Saudi Arabia’s role as a global halal hub. Saudi Arabia recorded approximately SAR 5.5 billion in halal-market investments in 2023, highlighting the scale of investment flowing into the sector. Across the wider MENA region, regulatory improvements and streamlined halal certification processes are also creating a more supportive environment for producers and exporters. Government-backed food-security programs are encouraging local processing, livestock production, cold-chain infrastructure, and food manufacturing, reducing dependence on imports while strengthening regional supply capabilities. These measures are expected to support both domestic consumption and halal food exports.
Tourism, Hospitality, and Modern Retail Expansion
Rapid tourism development and expanding hospitality infrastructure are creating additional demand for halal food across the Middle East. Saudi Arabia and the UAE are particularly important because their large tourism and hospitality sectors require extensive halal foodservice capacity for domestic and international Muslim visitors. The 2026 Global Muslim Travel Index projects international Muslim arrivals to reach 208 million in 2026, compared with 196 million in 2025, and 262 million by 2030, demonstrating the expanding potential of Muslim-friendly tourism and halal dining. Hotels, restaurants, airlines, catering companies, and tourism destinations are therefore expanding halal-certified menus and food offerings. At the same time, modern supermarkets, hypermarkets, convenience stores, e-commerce, and food-delivery platforms are increasing product accessibility. Online channels are identified as among the fastest-growing distribution routes for halal foods in the region. This combination of tourism and retail expansion is broadening consumption opportunities for both local and international halal brands.
Challenges of the Middle East Halal Food Market
Certification Complexity and Supply-Chain Compliance
Halal certification and supply-chain compliance can create operational challenges for manufacturers, importers, retailers, and foodservice companies. Businesses may need to comply with certification requirements covering ingredients, processing facilities, storage, transportation, labeling, and handling. Different markets and certification bodies can also create additional administrative requirements for companies operating across multiple Middle Eastern countries. In the GCC, halal certification frameworks involve national authorities and regional standards, while companies serving international markets may also need to satisfy additional certification requirements. Some industry assessments identify high certification and compliance costs as a barrier for smaller producers. Maintaining halal integrity throughout complex supply chains can also require stronger traceability systems and segregation procedures. These requirements may increase production and logistics expenses and can make market entry more difficult for small and medium-sized food manufacturers. Greater harmonization of standards, digital traceability, and streamlined certification procedures could help reduce these barriers while maintaining consumer confidence.
Import Dependence and Supply-Chain Infrastructure Constraints
The Middle East’s dependence on food imports creates exposure to international supply-chain disruptions, transportation costs, commodity-price fluctuations, and geopolitical risks. This is particularly important for countries with limited agricultural resources and high food-import requirements. Saudi Arabia, for example, has historically relied substantially on food imports while simultaneously pursuing policies to strengthen domestic production and food security. Some GCC market assessments also report import dependency exceeding 80% for certain protein categories, increasing exposure to external supply shocks. Infrastructure gaps outside major urban centers can further complicate distribution, particularly for temperature-sensitive halal meat, poultry, dairy, and seafood. Limited cold-chain capacity can increase logistics costs and affect distribution efficiency. Expanding domestic processing, cold-storage facilities, digital supply-chain monitoring, and regional production capabilities will therefore be important for improving supply resilience and supporting the long-term expansion of the Middle East halal food market.
Halal Food Product Launches in the Middle East
- Al Islami Foods – Extra-Large Wild-Caught Shrimps: Launched in the UAE in 2025, this premium seafood range features antibiotic-free and hormone-free wild-caught shrimp, targeting retail consumers seeking high-quality halal seafood.
- Tanmiah Food Company – Frozen Breaded Chicken Range: Introduced in Saudi Arabia in 2025, the range uses 100% fresh Saudi chicken and is designed for both retail and foodservice applications.
- Al Islami Foods – Chappati & Malabar Paratha: Launched in the UAE in 2025, these frozen bakery products are 100% vegetarian, zero-trans-fat, and can be prepared in approximately 3 minutes.
- Tanmiah Food Company – “Taste Secrets” Marinated Chicken: Introduced in Saudi Arabia in 2025, this value-added product line offers halal marinated fresh chicken designed to provide convenient meal preparation.
- Al Islami Foods – Gourmet Fries Range: The UAE 2025 launch includes products such as masala fries, jalapeño cheese poppers, and chili-garlic snacks, expanding the company’s frozen halal snack portfolio.
- Midtown Factory – Majlis Premium Arabian Ale: Launched in the UAE in 2025, this beverage line is positioned as a fully halal-brewed, alcohol-free alternative within the premium beverage category.
- JBS / Seara – Expanded Processed Chicken Products: In Saudi Arabia, the companies expanded halal chicken processing activities at their Jeddah facility, supporting greater availability of processed halal poultry products.
- Halal Products Development Company Ecosystem – ESG Halal Initiatives: Saudi Arabia’s halal ecosystem introduced initiatives combining halal certification with ESG principles, supporting the development of more sustainable and responsibly produced halal foods.
- Red Planet – Ultra Long Shelf-Life Halal Meals: The UAE-based company introduced freeze-dried halal meals designed for extended storage, with selected products offering up to 25 years of shelf life.
- Tanmiah Food Company – Halal Ingredient Collaborations: In Saudi Arabia, Tanmiah expanded its collaboration pipeline with Griffith Foods, supporting the development of halal culinary ingredients, sauces, and value-added food products.
Strong Religious Demand and Expanding Foodservice Consumption
Middle East halal meat, poultry, and seafood market is supported by strong religious adherence and the requirement for halal-compliant food among the region’s predominantly Muslim population. Demand extends across fresh meat, processed poultry, seafood, frozen products, and foodservice applications. Saudi Arabia illustrates the scale of the broader food market: its food retail sales exceeded US$50 billion in 2024, while the country imports around 70% of its food requirements, creating significant opportunities for international halal meat and seafood suppliers. Tourism, hospitality, and religious travel are also increasing demand for certified products in hotels, restaurants, catering, and institutional foodservice. Consumers increasingly seek halal certification alongside quality, hygiene, traceability, and food safety. Growing urbanization and modern retail infrastructure are expanding access through supermarkets, hypermarkets, specialist butcher shops, and online grocery platforms. Meanwhile, stronger certification systems and investments in domestic food production are helping regional countries improve supply security while supporting international halal trade.
Premium Sweets, Halal Ingredients, and Rising Consumer Spending
The Middle East halal confectionery market is expanding as consumers seek chocolates, candies, biscuits, pastries, and traditional sweets that comply with halal dietary requirements. Demand is particularly strong for products free from non-halal gelatin, alcohol-based flavorings, and other prohibited ingredients. Saudi Arabia demonstrates the substantial size of the regional opportunity, with its chocolate and sugar confectionery demand reaching approximately US$3.1 billion in 2025, according to Euromonitor. Imports represented 51.9% of the Saudi market in 2025, highlighting the importance of international suppliers. Manufacturers are responding with halal-certified premium chocolates, reduced-sugar products, filled confectionery, and locally inspired flavors. Attractive packaging is also important because confectionery is closely associated with gifting, celebrations, Ramadan, Eid, and hospitality. Supermarkets, duty-free outlets, convenience stores, specialty chocolate shops, and e-commerce platforms are broadening product availability. Rising disposable incomes, tourism, and demand for premium imported brands are expected to further support market expansion across major Middle Eastern markets.
High Dairy Consumption and Expansion of Value-Added Products
Middle East halal dairy products market benefits from the essential role of milk, yogurt, cheese, butter, and other dairy products in household consumption and foodservice. Halal compliance is particularly important for processed dairy products because ingredients such as enzymes, emulsifiers, flavorings, and gelatin may require certification. Saudi Arabia provides an important indication of regional food demand, with the country’s food retail market exceeding US$50 billion in 2024 and expected to grow by approximately 5% in 2025. Dairy manufacturers are expanding beyond traditional products into flavored milk, probiotic yogurt, lactose-free dairy, high-protein products, and convenient single-serve formats. Population growth and urbanization are increasing demand for packaged and convenient foods, while modern supermarkets and cold-chain networks improve availability of chilled products. Saudi Arabia also depends on imports for approximately 70% of its food requirements, creating opportunities for international halal-certified dairy suppliers. Premiumization, health awareness, and demand for nutritious products are expected to support continued development.
Urban Lifestyles and Demand for Convenient Halal Food
The Middle East halal food convenience-store market is benefiting from urbanization, longer working hours, tourism, and growing demand for quick food purchases. Convenience stores increasingly provide packaged halal snacks, beverages, bakery products, chilled foods, frozen meals, ready-to-eat products, and other everyday essentials. Saudi Arabia’s convenience retail market illustrates this expansion: one 2025 market assessment estimated the narrow-format convenience market at approximately US$4.62 billion, with around 53,800 convenience-oriented outlets and 1.05 billion annual transactions. The wider Saudi food retail market exceeded US$50 billion in 2024, providing a large consumer base for convenient food formats. Convenience retailers are also adopting digital ordering, electronic payments, delivery partnerships, and prepared-food counters to increase basket value. Riyadh, Jeddah, Makkah, Madinah, and other densely populated areas offer strong opportunities because of residential demand and tourism-related footfall. Competition from supermarkets and online grocery platforms remains significant, but proximity and immediate availability continue to support the convenience channel.
Saudi Arabia Vision 2030, Food Security, and Expanding Halal Production
Saudi Arabia represents a major halal food market in the Middle East, supported by its predominantly Muslim population, religious tourism, expanding food retail sector, and government focus on food security. Saudi Arabia’s food retail sales exceeded US$50 billion in 2024, while the country imports approximately 70% of its food requirements, creating opportunities for both domestic producers and international halal suppliers. The country’s young population also supports demand for packaged, convenient, and value-added food products; USDA data indicates that approximately 63% of the population is under 30. Hajj and Umrah tourism generates additional demand across hotels, restaurants, catering companies, and foodservice facilities. At the same time, Vision 2030 is supporting domestic food production, investment, supply-chain development, and diversification of the food economy. Modern retail and digital grocery channels are expanding alongside traditional outlets. These developments are strengthening the Kingdom’s halal food ecosystem and supporting opportunities across meat, poultry, seafood, confectionery, dairy, processed foods, and ready-to-eat categories.
United Arab Emirates Tourism, Trade Connectivity, and Premium Halal Food Demand
UAE halal food market is supported by its large Muslim consumer base, highly international population, tourism industry, and position as a major food-trade hub. The country’s food and beverage sector benefits from substantial import activity, with the UAE importing around 90% of its food requirements, creating significant opportunities for international halal-certified suppliers. The country also recorded approximately 29.2 million international tourist arrivals in 2024, according to the UAE Ministry of Economy, supporting demand across hotels, restaurants, catering, and retail. The UAE has established a formal national halal certification framework, strengthening consumer confidence in meat, poultry, dairy, packaged foods, and processed products. Dubai and Abu Dhabi are particularly important markets because of their dense retail networks and extensive hospitality infrastructure. E-commerce is also transforming food purchasing, with online grocery and food-delivery platforms providing convenient access to halal products. Rising demand for premium, healthier, sustainable, and convenient foods is encouraging manufacturers to diversify halal offerings. These factors are strengthening the UAE’s role as both a regional consumption market and an international halal-food trading center.
Qatar High Import Dependence, Regulation, and Hospitality Expansion
Qatar’s halal food market is driven by its predominantly Muslim population, high purchasing power, strong import dependence, and expanding hospitality sector. Qatar relies heavily on international food suppliers because of its limited agricultural capacity, creating substantial opportunities for halal-certified meat, poultry, dairy, packaged foods, and other products. According to the U.S. Department of Agriculture, Qatar’s food import requirements remain significant, with the country importing approximately 90% of its food needs. Qatar’s population also includes a large expatriate community, increasing demand for diverse international food products while maintaining strong requirements for halal compliance. The country’s food-control framework requires imported meat and poultry to meet halal and certification requirements, supporting traceability and consumer confidence. Tourism and hospitality remain important demand generators following the country’s major infrastructure investments associated with the 2022 FIFA World Cup. Doha’s hotels, restaurants, catering companies, supermarkets, and convenience stores provide broad distribution channels for halal products. Rising disposable income, urbanization, digital grocery services, and expanding international trade connections are expected to support continued market development.
Market Segmentation
Product
- Meat, Poultry & Seafood
- Fruits & Vegetables
- Dairy Products
- Cereals & Grains
- Oil, Fats & Waxes
- Confectionery
- Others
End Use
- Hypermarkets & Supermarket
- Online Stores
- Convenience Stores
- Specialty Stores
- Others
Countries
- Saudi Arabia
- United Arab Emirates
- Qatar
- Iraq
- Iran
- Egypt
- Algeria
- Morocco
- Nigeria
All the Key players have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Nestle SA
- JBS SA
- BRF SA
- Kawan Food Berhad
- Cargill Inc.
- Carrefour SA
- Crescent Foods Inc.
- VegaVites
- American Halal Company Inc.
- American Foods Group LLC
- Al Islami Foods
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Product, Distribution Channel and Countrie |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.