Europe Organic Food Market Report by Product Type, Distribution Channel, Country and Company Analysis 2026-2034
Buy NowEurope Organic Food Market Size and Forecast
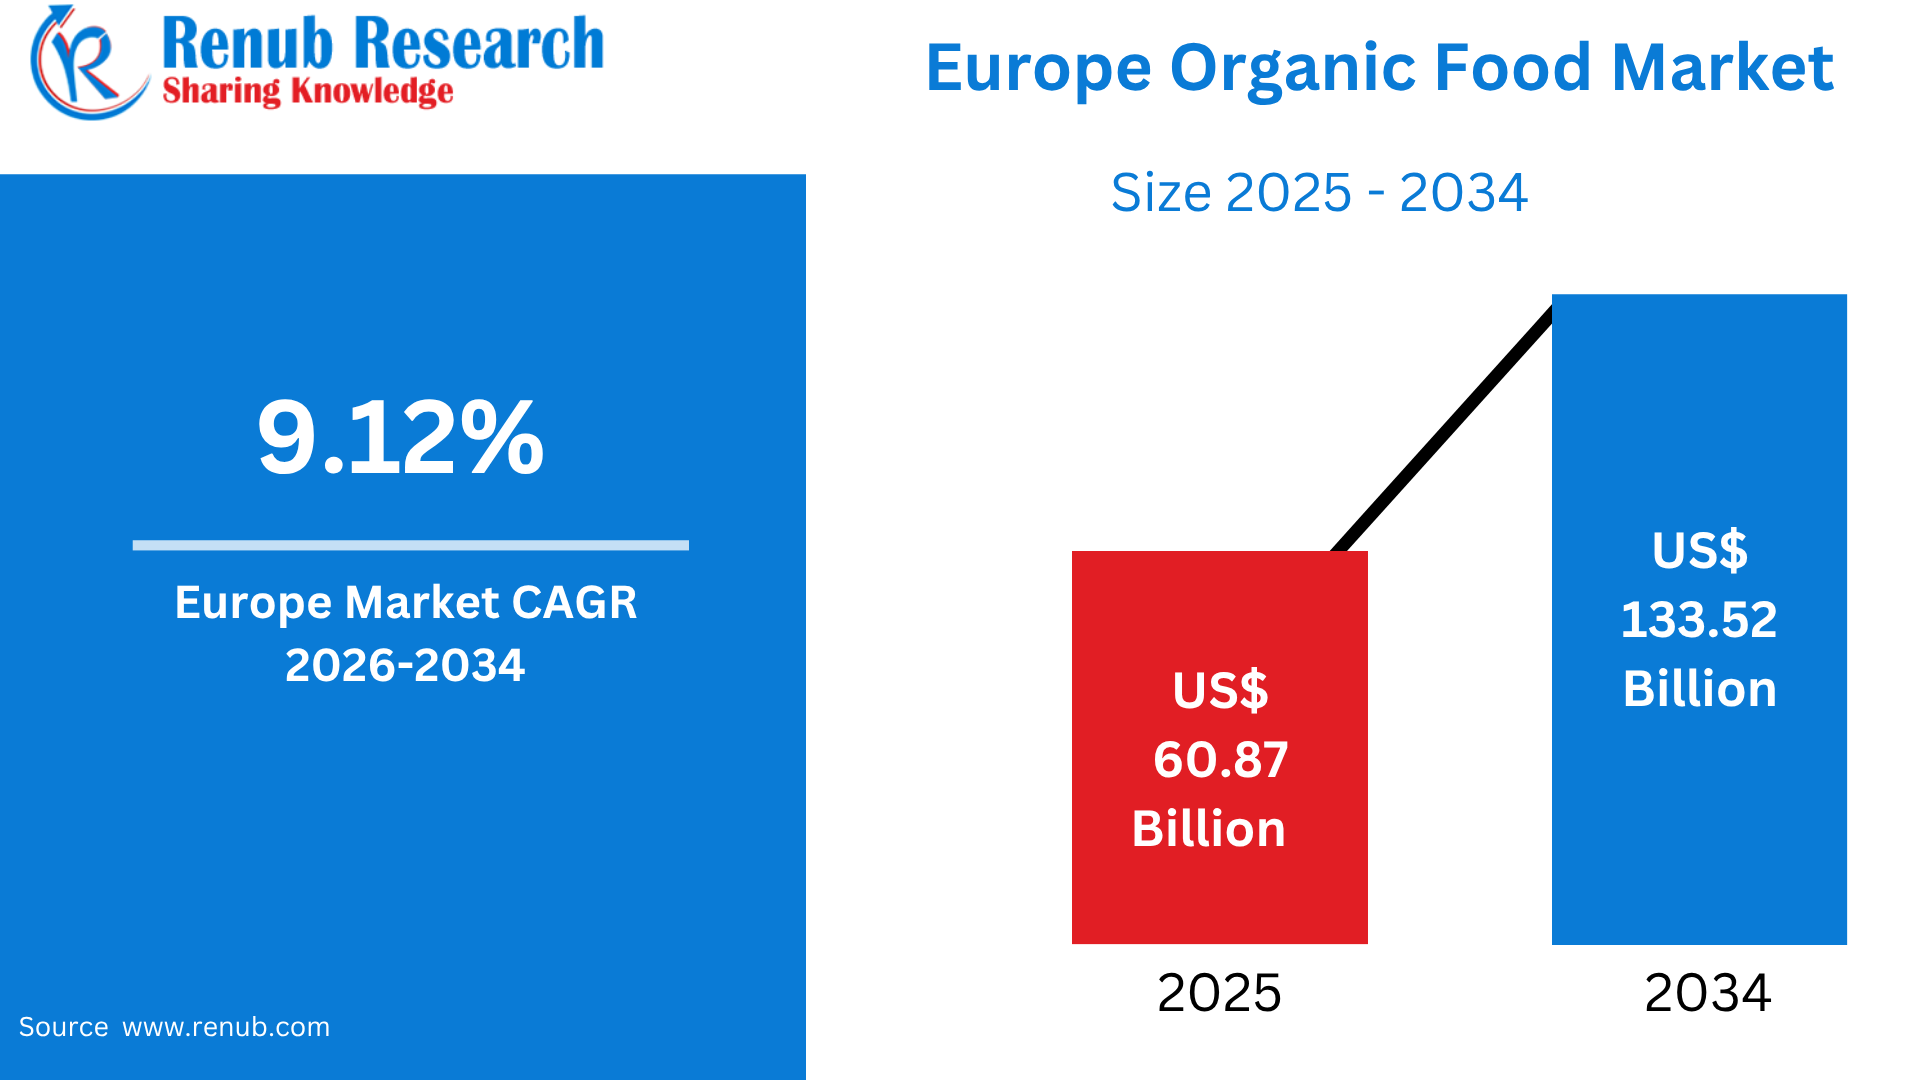
The Europe organic food market was valued at approximately US$ 60.87 billion in 2025 and is projected to reach US$ 133.52 billion by 2034, expanding at a CAGR of 9.12% during 2026–2034. The market is witnessing strong growth as European consumers increasingly prioritize health, nutrition, environmental sustainability, and food quality in their purchasing decisions. Rising concerns regarding chemical residues, synthetic pesticides, and the environmental impact of conventional agriculture are encouraging consumers to choose organically produced food products. In addition, growing awareness of the nutritional and perceived health benefits associated with organic foods is strengthening demand across the region.
What is Organic Food and Its Uses & Popularity in Europe
Organic food refers to agricultural and food products produced according to organic farming standards, which generally restrict the use of synthetic pesticides, chemical fertilizers, genetically modified organisms, and certain artificial additives. Organic farming emphasizes soil health, biodiversity, natural farming practices, animal welfare, and environmentally responsible production methods. Organic food includes fruits and vegetables, cereals, dairy products, meat, eggs, beverages, bakery products, packaged foods, and other processed products.
In Europe, organic food is increasingly popular because consumers are becoming more conscious of health, food quality, sustainability, and environmental protection. Organic products are widely used as part of healthy and environmentally responsible diets, while consumers often associate organic certification with controlled production standards and traceability. The European Union has established a common organic logo and regulatory framework, helping consumers identify certified organic products. The EU’s organic agricultural area reached approximately 19.6 million hectares in 2023, representing around 12% of its total agricultural land, demonstrating the region’s significant commitment to organic production. Growing retail availability, expanding organic product ranges, sustainability initiatives, and increasing consumer awareness are expected to further strengthen organic food popularity across Europe.
Agricultural area under organic farming in Europe
European Green Deal has established an ambitious objective for at least 25% of the European Union’s agricultural land to be managed organically by 2030. The proportion of EU agricultural land dedicated to organic farming increased substantially from 5.9% in 2012 to 10.8% in 2023, supported by rising consumer demand for organic products and favorable agricultural policies. However, reaching the 2030 target will require the pace of expansion to more than double during the remaining years. While existing policies and initiatives are encouraging the transition toward organic agriculture, current progress indicates that policy measures alone may not be sufficient to achieve the 25% target. Further efforts across the organic food value chain, including stronger farmer incentives, greater consumer awareness, improved market access, and increased investment in organic production, will be necessary to accelerate adoption and close the gap.
EU-27 Organic Farming: Key Findings
- 2012: Organic farming accounted for 5.9% of the EU-27’s utilised agricultural area (UAA).
- 2014: The share increased gradually to approximately 6.1%.
- 2016: Organic farmland reached around 7.0% of total UAA.
- 2018: The proportion rose to approximately 7.8%.
- 2020: Organic farming represented about 9.1% of EU-27 agricultural land.
- 2021: The share increased further to approximately 9.9%.
- 2022: Organic farming reached around 10.4% of utilised agricultural area.
- 2023: The share reached 10.8%, demonstrating continued expansion of organic agriculture.
- 2030 Target: The EU aims for 25.0% of utilised agricultural area to be under organic farming by 2030.
- Overall trend: The share increased from 5.9% in 2012 to 10.8% in 2023, an increase of 4.9 percentage points.
- Target gap: At 10.8% in 2023, the EU-27 remains 14.2 percentage points below its 25% target for 2030.
- Key implication: The pace of organic farmland expansion will need to accelerate substantially to achieve the EU’s 2030 objective.
Growth Drivers of the Europe Organic Food Market
Rising Consumer Awareness of Health and Sustainable Eating
Growing awareness of healthy diets and environmentally responsible consumption is a major driver of the Europe organic food market. European consumers are increasingly interested in food quality, ingredient transparency, sustainable agriculture, and products perceived as having fewer synthetic inputs. According to Eurostat, around 19.6 million hectares of agricultural land in the EU were managed organically in 2023, representing approximately 12.1% of the EU’s total agricultural area. This expanding production base is strengthening the availability of organic products across European markets. Consumers are also increasingly examining food labels, production methods, and certification before making purchasing decisions. Organic products are gaining popularity across categories such as fresh produce, dairy, meat, cereals, beverages, and packaged foods. Younger consumers are particularly interested in sustainability, animal welfare, biodiversity, and environmentally responsible brands. Retailers are responding by expanding private-label organic ranges and improving shelf space for certified products. Growing awareness, combined with greater product availability and transparent certification systems, is therefore expected to support sustained demand for organic food across Europe.
Expansion of Organic Agriculture and Supportive Government Policies
Government initiatives supporting sustainable agriculture and the expansion of organically managed farmland are providing an important foundation for market growth. The European Union’s Farm to Fork Strategy and Common Agricultural Policy (CAP) encourage more sustainable food production and support the transition toward environmentally friendly agricultural practices. The EU has set a target of achieving at least 25% of agricultural land under organic farming by 2030, compared with approximately 12% in 2023. This policy direction is encouraging farmers to adopt organic production methods while increasing the long-term supply of certified organic ingredients and food products. Financial support, technical assistance, certification frameworks, and environmental incentives can help farmers transition from conventional to organic agriculture. A stronger domestic supply base can also improve product availability and reduce dependence on imported organic ingredients. In addition, the EU organic logo provides consumers with a standardized identification system, increasing confidence in certified products. As governments continue emphasizing biodiversity, soil health, reduced chemical use, and sustainable food systems, policy support is expected to remain a significant growth catalyst.
Growing Retail and E-Commerce Availability of Organic Products
The expansion of supermarkets, specialty organic retailers, convenience stores, and e-commerce platforms is making organic food increasingly accessible to European consumers. Organic products were once concentrated primarily in specialist stores, but major supermarket chains now offer extensive ranges covering fresh produce, dairy, bakery products, meat, beverages, snacks, and ready-to-eat foods. This broader distribution is helping organic products reach a larger consumer base. According to industry estimates, European consumers spend tens of billions of euros annually on organic food, making the region one of the world’s most developed organic markets. Online grocery shopping is providing another growth channel by allowing consumers to compare products, certifications, ingredients, and prices conveniently. Retailers are also expanding private-label organic offerings, which can provide more affordable alternatives to premium branded products. Improvements in cold-chain logistics and distribution networks are further supporting the availability of perishable organic foods across countries. As retailers continue to expand organic product portfolios and digital purchasing becomes more common, improved accessibility is expected to encourage trial, repeat purchases, and broader adoption throughout Europe.
Challenges of the Europe Organic Food Market
Higher Prices and Production Costs Limit Mass Adoption
Higher retail prices remain one of the major challenges affecting the expansion of organic food consumption in Europe. Organic farming can involve greater labor requirements, certification expenses, specialized inputs, lower yields for certain crops, and stricter production standards. These factors can increase production and distribution costs, which are frequently reflected in retail prices. The price difference between organic and conventional products can become particularly important during periods of inflation or reduced household purchasing power. Although European consumers increasingly value sustainability and food quality, not all households can consistently afford premium-priced products. This creates a gap between consumer interest in organic food and actual purchasing behavior. Smaller organic farms may also face difficulties achieving economies of scale and maintaining profitability while complying with certification requirements. According to Eurostat, organic farming accounted for approximately 12.1% of EU agricultural land in 2023, indicating that conventional agriculture continues to dominate production. Retailers and producers are therefore increasingly focusing on private-label products, local supply chains, and improved production efficiency to reduce price barriers. Greater affordability will be important for expanding organic food consumption beyond higher-income consumer groups.
Supply Constraints, Certification Complexity, and Limited Production Capacity
Supply-side limitations represent another challenge for Europe’s organic food market. Organic agriculture generally requires producers to comply with strict production, processing, traceability, and certification requirements. Farmers transitioning from conventional to organic production may also face a conversion period during which they must follow organic practices without necessarily receiving the full price premium associated with certified organic products. These requirements can discourage some producers from entering the sector. Supply can also be affected by weather conditions, crop yields, labor availability, and the limited availability of organically certified seeds, feed, and other agricultural inputs. In 2023, the EU had approximately 19.6 million hectares under organic farming, equivalent to about 12% of its agricultural area, showing substantial progress but also indicating that most farmland remains outside organic production. In addition, differences in production capabilities between European countries can create uneven supply and pricing conditions. Imports are sometimes necessary to satisfy demand for specific organic products, potentially increasing transportation costs and supply-chain complexity. Expanding farmer support, simplifying certification processes, improving organic-input availability, and strengthening domestic supply chains will be important for addressing these constraints.
Organic Farming Product Launches in Europe
- Once Upon a Farm Organic Range – United Kingdom (2026): Once Upon a Farm announced its European expansion with a limited rollout of organic refrigerated snacks and food products at selected Whole Foods Market locations in London.
- Joseph Brotmanufaktur Organic Bakery Range – Austria (2025): Austrian organic bakery Joseph Brotmanufaktur expanded its range using 14 rare grain varieties sourced through partnerships with smallholder families, emphasizing biodiversity and sustainable production.
- Het Polderveld Organic Farm Products – Belgium (2025): Belgian farm Het Polderveld expanded its community-supported organic food model, supplying around 150 families and a local hospital with locally produced organic foods.
- Rozino Organic Farm Dairy and Meat Range – Bulgaria (2025): Rozino Organic Farm was recognized for its integrated organic production model covering dairy, meat, processing, seasonal production, and zero-waste practices.
- Peskesi Organic Farm-to-Table Products – Greece (2025): Peskesi in Crete expanded its farm-to-table organic food offering through its own organic farm and partnerships with local producers, with approximately 98% of its suppliers coming from local producers.
- Radis&Bona Organic Local Food Range – Germany (2025): German retailer Radis&Bona eG strengthened its organic product portfolio, offering 100% organic products sourced within an approximately 80-km radius of its Regensburg location.
- Organic Grain and Bakery Products – Austria (2025): Joseph Brotmanufaktur’s work with 24 smallholder families and 14 rare grain varieties represents a notable European launch and expansion of biodiversity-focused organic bakery products.
- Organic Poultry Products – Finland (2025): Kuorttisen Luomukanala, an organic poultry farm in Finland, was recognized among the finalists of the 2025 EU Organic Awards, highlighting its organic poultry production and expanding presence in Europe’s organic food sector.
- Organic Farm Dairy & Meat Products – Romania (2025): Herta Bio Apicole SRL from Romania was selected as a finalist in the EU Organic Awards’ Best Organic Food Processing SME category, highlighting the development of certified organic processed-food products.
- Organic Farming Scheme Expansion – Ireland (2025): Ireland expanded support for organic farming through its Organic Farming Scheme, with the number of participating farmers increasing 221% over 2021–2025 to approximately 5,500 farmers. The initiative is intended to strengthen domestic organic food production.
Rising Health Awareness and Sustainable Agriculture Support Europe Organic Fruits and Vegetables Segment Growth
Europe organic fruits and vegetables market is a leading segment of the regional organic food industry, supported by increasing consumer interest in healthy diets, clean-label products, and environmentally responsible agriculture. Organic fruits and vegetables are produced under certified farming practices that restrict the use of synthetic pesticides and fertilizers, making them attractive to consumers seeking more natural food choices. According to Eurostat, organic farming covered approximately 19.6 million hectares in the EU in 2023, representing around 12.1% of total agricultural land. The growing adoption of organic farming is strengthening the availability of certified produce across European markets. Rising concerns about nutrition, food quality, pesticide exposure, and environmental sustainability are also encouraging consumers to purchase organic fresh produce. In addition, the popularity of plant-based diets, vegetarianism, veganism, and clean eating is increasing demand for fruits and vegetables. Supermarkets, organic retailers, farmers’ markets, and online grocery platforms are expanding their organic produce ranges, further improving accessibility. Continued government support for sustainable farming and growing consumer willingness to prioritize healthier food choices are expected to sustain segment expansion.
Ethical Consumption and Premium Protein Demand Strengthen Europe Organic Meat Market Development
Europe organic meat market is expanding as consumers increasingly seek high-quality, responsibly produced, and traceable sources of animal protein. Organic livestock production follows strict standards governing feed, animal welfare, veterinary treatments, and farming practices, helping differentiate organic meat from conventional alternatives. European consumers are becoming more conscious of the environmental, ethical, and health-related aspects of meat production, supporting demand for certified organic options. Premiumization is another important trend, with consumers willing to pay higher prices for products offering greater transparency regarding sourcing, production methods, and animal welfare. Retailers and supermarkets are responding by expanding organic meat selections across beef, poultry, pork, and other categories. The EU’s organic production framework also requires certified organic livestock to meet defined requirements relating to feed, housing, and animal management, helping strengthen consumer confidence. However, organic meat remains relatively expensive because of higher production costs and limited supply compared with conventional meat. Despite these challenges, increasing awareness of sustainable consumption, improved retail availability, and demand for premium food products are expected to support steady growth in the European organic meat segment.
Health-Oriented Eating and Premium Bakery Trends Drive Europe Demand
Europe organic bread and bakery market is benefiting from growing consumer preference for natural, minimally processed, and health-oriented food products. Organic bakery products are manufactured using certified organic ingredients produced under regulated agricultural practices, while consumers increasingly seek products featuring whole grains, natural ingredients, and simplified formulations. Europe has a strong cultural connection with bread and bakery products, creating a favorable foundation for organic alternatives. The growing popularity of whole-grain, sourdough, gluten-free, vegan, and plant-based bakery products is creating new opportunities for manufacturers and specialist bakeries. Retailers are also expanding organic bread, biscuits, pastries, cakes, and snack offerings to meet changing consumer preferences. According to Eurostat, organic farming covered approximately 12.1% of EU agricultural land in 2023, supporting the development of a broader supply base for certified organic ingredients. Manufacturers are increasingly combining traditional European baking concepts with contemporary health and sustainability trends. Sustainable packaging and transparent ingredient labeling are also becoming important purchasing considerations. As consumers continue to prioritize food quality, natural ingredients, and responsible production, organic bakery products are expected to gain greater penetration across European supermarkets, specialty stores, bakeries, and online channels.
Demand for Convenient and Healthier Food Supports Europe Retail Expansion
Europe organic food convenience stores market is gaining importance as consumers increasingly seek healthier food choices that fit busy urban lifestyles. Convenience stores are expanding their organic product selections to include ready-to-eat meals, fresh produce, organic snacks, beverages, dairy products, bakery items, and on-the-go foods. Rising urbanization, longer working hours, and growing demand for convenient meal solutions are encouraging consumers to purchase healthier packaged and prepared foods closer to where they live and work. Retailers are responding by introducing private-label organic ranges, smaller package sizes, and convenient formats that appeal to time-conscious consumers. Sustainability is also influencing retail strategies, with stores increasingly focusing on recyclable packaging, reduced food waste, and responsibly sourced products. Europe’s extensive urban population and established organic food culture provide a strong foundation for this distribution channel. In addition, improved cold-chain infrastructure is making it easier for convenience retailers to stock perishable organic products such as fresh fruits, vegetables, dairy, and prepared meals. As consumers increasingly combine convenience with health and sustainability considerations, the organic product assortment available through convenience stores is expected to expand further across European markets.
Europe E-Commerce Expansion and Greater Product Transparency Accelerate Online Sales
Europe organic food online retail market is expanding as consumers increasingly use digital platforms to purchase groceries and specialty food products. Online channels provide convenient home delivery while giving consumers access to a broader selection of organic products than may be available in nearby physical stores. E-commerce platforms can also provide detailed information about ingredients, certifications, farming practices, nutritional content, sourcing, and sustainability, helping consumers make more informed purchasing decisions. The rapid adoption of online grocery shopping during the COVID-19 pandemic accelerated digital purchasing habits, many of which have continued as consumers value convenience and time savings. Improvements in cold-chain logistics and last-mile delivery are also enabling online retailers to distribute fresh organic fruits, vegetables, dairy, meat, and other temperature-sensitive products more efficiently. According to Eurostat, 77% of people aged 16–74 in the EU purchased or ordered goods or services online in 2024, demonstrating the extensive reach of digital commerce across the region. Supermarket websites, dedicated organic retailers, online marketplaces, and direct-to-consumer brands are consequently creating new routes to market. Increasing smartphone use, digital payments, subscription grocery services, and improved delivery networks are expected to further strengthen online organic food sales in Europe.
Rising Health Awareness and Sustainable Consumption Strengthen United Kingdom Market Demand
United Kingdom organic food market is expanding steadily as consumers increasingly prioritize health, sustainability, ethical sourcing, and food transparency. Demand is rising for products produced without synthetic pesticides and fertilizers and with strict controls on additives and genetically modified ingredients. Organic fruits and vegetables, dairy products, meat, bakery items, and packaged foods are gaining wider acceptance across the country. According to the Soil Association, UK organic food and drink sales reached approximately £3.7 billion in 2024, demonstrating the strength of consumer demand. Supermarkets, specialist retailers, and online grocery platforms are continuously expanding their organic ranges to improve accessibility. Growing interest in vegan, plant-based, clean-label, and environmentally responsible diets is also creating additional opportunities. Organic certification and clear labeling help strengthen consumer confidence by providing greater transparency regarding production standards. In January 2026, Once Upon a Farm announced a limited UK rollout through selected Whole Foods Market locations in London, marking the brand’s expansion into Europe with organic refrigerated products. Continued consumer awareness, retail expansion, and sustainability-focused agricultural policies are expected to support further market development.
Local Production, Sustainability, and Expanding Retail Availability Belgium Drive Growth
Belgium organic food market is benefiting from increasing consumer awareness of healthy eating, environmental sustainability, animal welfare, and responsible food production. Consumers are showing growing interest in organic fruits and vegetables, dairy products, meat, beverages, and packaged foods, while demand for locally produced organic food is encouraging farmers to adopt certified organic farming practices. Belgium’s organic agricultural area has continued to expand, supporting the availability of locally produced products. The market is also benefiting from growing interest in vegetarian, vegan, fair-trade, and environmentally responsible consumption patterns. Supermarkets and specialist retailers play an important role in making organic products more accessible to consumers. Colruyt Group’s Bio-Planet operates as a dedicated organic supermarket chain, while Colruyt stores offer more than 500 organic products, demonstrating the increasing integration of organic food into mainstream retail. In June 2025, Colruyt Group highlighted the continued expansion of its organic food assortment and its intention to maintain its leadership position in Belgium’s organic segment. Growing product availability, consumer awareness, and retailer investment are expected to support continued expansion of the Belgian organic food market.
Netherlands Sustainable Agriculture and Government Initiatives Accelerate Organic Food Adoption
Netherlands organic food market is developing as consumers increasingly prioritize sustainable, environmentally responsible, and high-quality food products. Demand for organic fruits, vegetables, dairy products, meat, and packaged foods is being supported by concerns regarding food safety, agricultural sustainability, biodiversity, and environmental impact. The Netherlands is also recognized for its advanced agricultural technologies and efficient farming systems, which provide opportunities for improving organic production methods. Supermarkets remain a major distribution channel, while online grocery platforms are increasing consumer access to organic products. Government initiatives are providing additional momentum. The Netherlands has established an objective of increasing the share of organic agricultural land to 15% by 2030, compared with approximately 4.5% in 2023. The national Action Plan for Growth in Organic Production and Consumption 2022–2030 aims to strengthen both organic supply and consumer demand. The launch of BioMarktMeter, developed through an initiative of the Ministry of Agriculture, Fisheries, Food Security and Nature and Wageningen University & Research, provides data on organic food supply and demand across sales channels. Continued agricultural innovation, policy support, and consumer awareness are expected to strengthen the country’s organic food market.
Strong Consumer Trust and Ambitious Organic Farming Targets Support Germany Market Leadership
Germany organic food market is one of Europe’s most established markets, supported by strong consumer awareness, extensive retail availability, developed certification systems, and growing interest in sustainable food production. German consumers place considerable importance on food quality, environmental protection, animal welfare, and transparent sourcing, creating favorable conditions for organic products. Organic food is widely available through supermarkets, discount retailers, specialist organic stores, farmers’ markets, and online channels. According to Germany’s Federal Ministry of Food and Agriculture, organic agriculture accounted for approximately 11.2% of Germany’s agricultural land in 2023, highlighting the country’s substantial organic farming base. Demand is also being strengthened by the growing popularity of plant-based, clean-label, regional, and sustainably produced foods. Government policy provides another important growth opportunity. Germany’s Organic Strategy 2030 established an ambitious objective of increasing organic farmland to 30% by 2030, supported by measures covering production, processing, retail, research, and consumer awareness. Continued investment in organic agriculture, strong consumer trust, and broad retail distribution are expected to maintain Germany’s position as a major contributor to Europe’s organic food market.
Market Segmentation
Product Types
- Organic Fruits and Vegetables
- Organic Meat, Poultry and Dairy
- Organic Processed Food
- Organic Bread and Bakery
- Organic Cereal and Food Grains
- Others
Distribution Channel
- Supermarkets/ Hypermarkets
- Specialty Stores
- Convenient Stores
- Online Retail Stores
- Others
Countries
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Russia
- Poland
- Greece
- Norway
- Romania
- Portugal
- Rest of Europe
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Competitive Landscape
- Danone S.A.
- General Mills Inc.
- Sprouts Farmers Market Inc.
- The Hain Celestial Group Inc.
- The Kroger Company
- United Natural Foods Inc.
- Dole PLc
- Newman's Own
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Product Type, Distribution Channel and Countries |
| Countries Covered |
|
| Companies Covered |
1. Danone S.A. |
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Key Questions Answered in This Report:
What is the projected market size of the Europe organic food market by 2033?
What is the expected CAGR of the Europe organic food market from 2025 to 2033?
Which countries are the leading markets for organic food in Europe?
What are the main product categories in the Europe organic food market?
How do government policies influence the growth of the organic food market in Europe?
What are the major distribution channels for organic food in Europe?
What role does consumer health consciousness play in the growth of the organic food market?
How does environmental sustainability drive demand for organic food in Europe?
What are the biggest challenges faced by the Europe organic food market?
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.