Frozen Vegetables Market Size, Share, Growth, Trends, Industry Analysis & Forecast 2026–2034
Buy NowFrozen Vegetables Market Trends
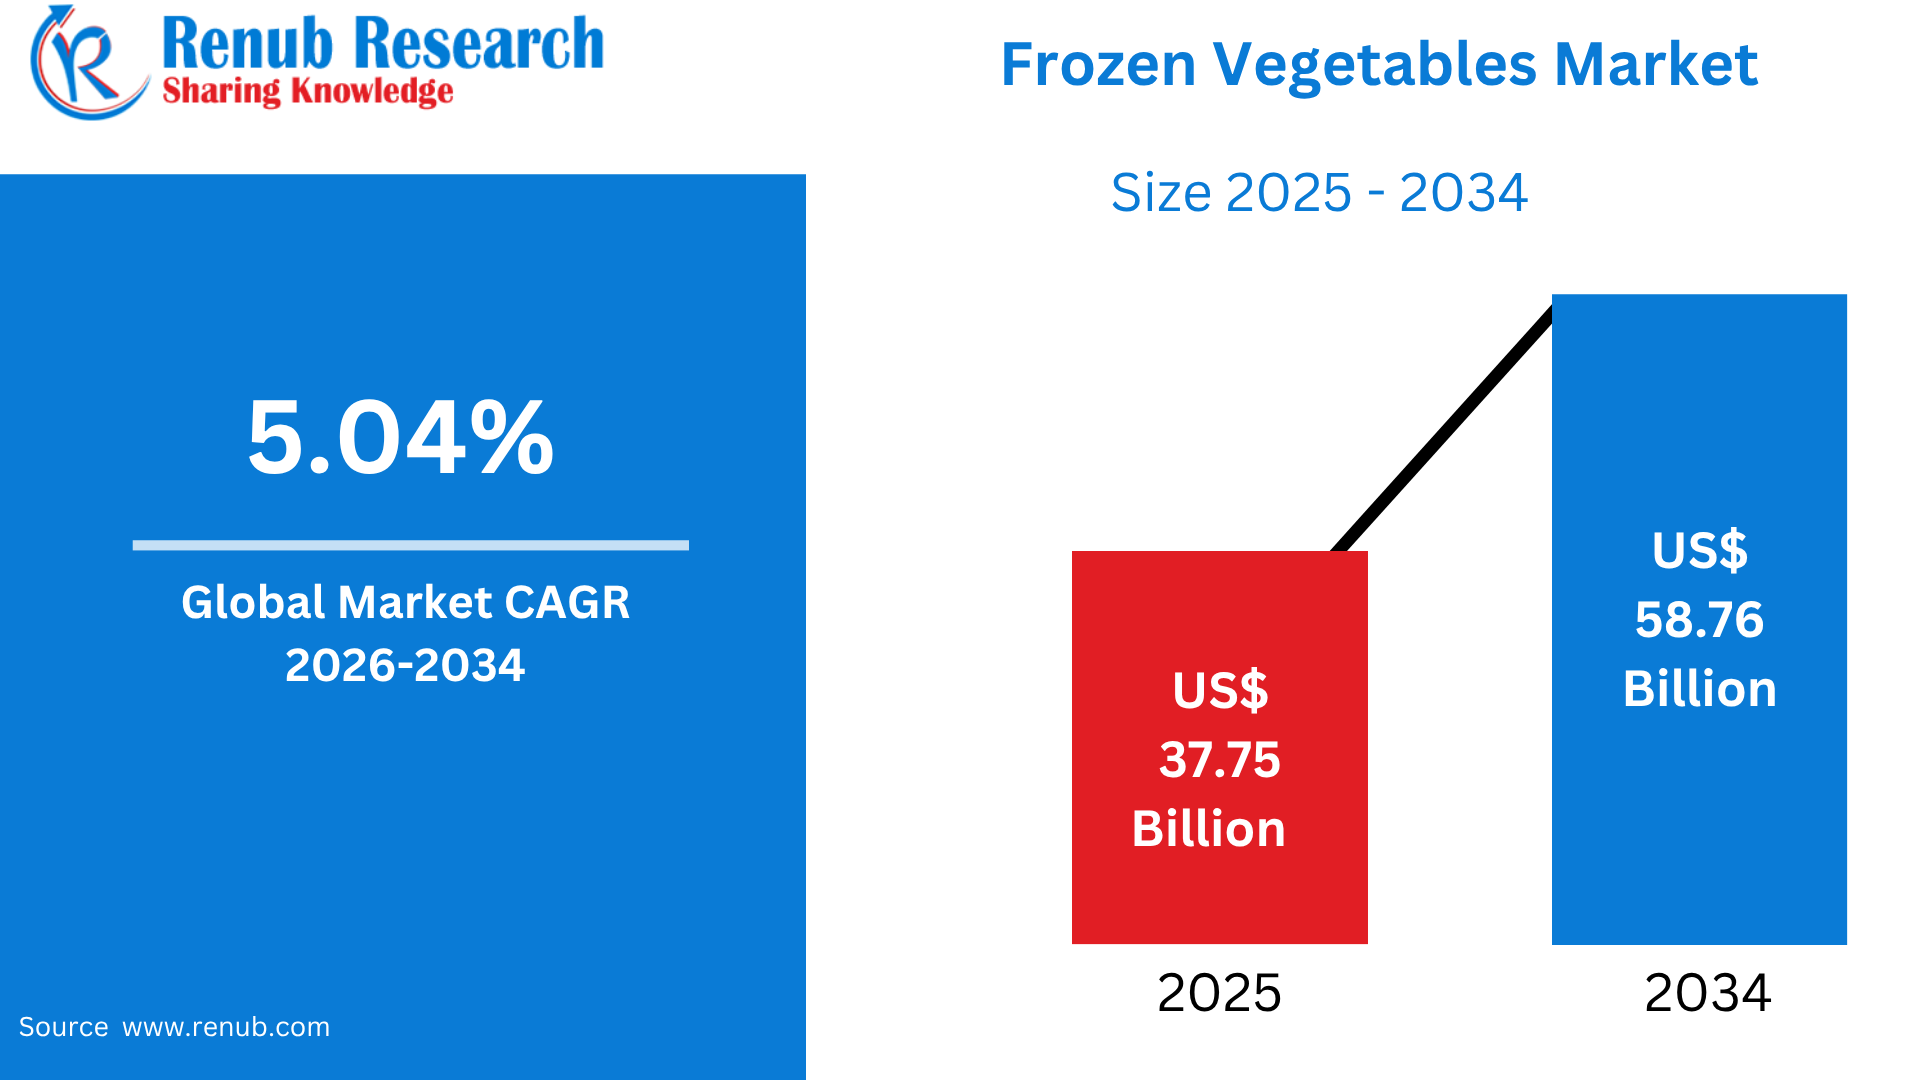
Frozen Vegetables Market is projected to grow from US$ 37.75 Billion in 2025 to US$ 58.76 Billion by 2034, registering a Compound Annual Growth Rate of 5.04% during 2026–2034. Market growth is driven by increasing consumer demand for convenient, nutritious, and long-shelf-life food products, rising urbanization, and busy lifestyles. Advancements in freezing technology, expanding retail and e-commerce distribution channels, growing preference for ready-to-cook meals, and increasing awareness of reducing food waste are expected to further support sustained market expansion globally.
Frozen Vegetables Industry Overview
Frozen vegetables are fresh vegetables that undergo washing, cutting, and brief blanching before being rapidly frozen to lock in nutrients, taste, and texture. This process slows natural spoilage and microbial activity, allowing the vegetables to remain safe and high-quality for months. Typically stored at sub-zero temperatures, they require no preservatives because freezing alone maintains freshness. These products offer year-round availability, reduce preparation time, and help minimize food waste. Due to being frozen shortly after harvest, they often retain nutritional value comparable to fresh produce that may travel long distances or spend days in storage before reaching consumers.
A key driver of the frozen vegetables market is the global rise in demand for quick-to-prepare meals among busy urban populations. As lifestyles become more fast-paced, consumers increasingly rely on products that save time without compromising nutrition. Modern freezing technologies, especially IQF techniques, help preserve color, taste, and nutrients, making frozen vegetables highly appealing. The expansion of e-commerce grocery platforms and improved cold-chain infrastructure further supports market growth. Additionally, greater awareness of food waste reduction and consistent product availability across seasons are encouraging households, restaurants, and food manufacturers to prefer frozen vegetables over fresh alternatives.
Global Frozen Vegetables Adoption & Market Popularity
Frozen vegetables are vegetables that are harvested at peak ripeness, thoroughly cleaned, blanched, and rapidly frozen using advanced quick-freezing technology to preserve their freshness, nutritional value, texture, and flavor. This process helps retain essential vitamins, minerals, and antioxidants while significantly extending shelf life without the need for artificial preservatives. Common frozen vegetables include peas, corn, broccoli, spinach, carrots, cauliflower, mixed vegetables, and green beans, making them convenient staples for households, restaurants, and foodservice operators. They are widely used in soups, curries, stir-fries, pasta dishes, salads, casseroles, pizzas, ready-to-eat meals, and frozen snacks. The popularity of frozen vegetables has grown worldwide due to increasing urbanization, busy lifestyles, rising demand for convenient meal solutions, and greater awareness of healthy eating habits. Consumers appreciate their year-round availability, reduced food waste, and consistent quality regardless of seasonal fluctuations. The expanding frozen food industry, improvements in cold chain logistics, and the rapid growth of supermarkets, hypermarkets, and online grocery platforms have further boosted global demand. Additionally, restaurants, institutional kitchens, and food manufacturers increasingly rely on frozen vegetables for their cost efficiency, ease of storage, and reliable supply, making them an integral part of the modern global food industry.
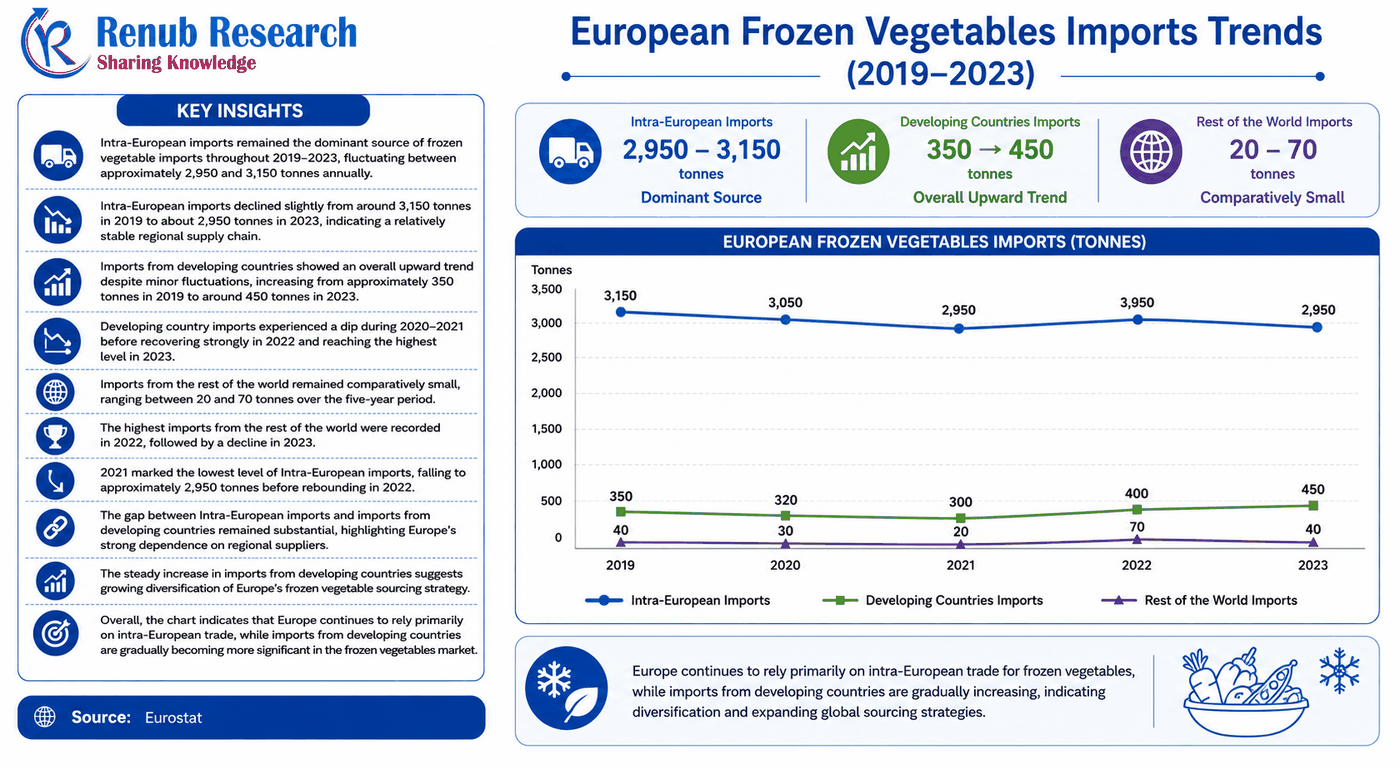
European Frozen Vegetables Imports Trends (2019–2023)
- Intra-European imports remained the dominant source of frozen vegetable imports throughout 2019–2023, fluctuating between approximately 2,950 and 3,150 tonnes annually.
- Intra-European imports declined slightly from around 3,150 tonnes in 2019 to about 2,950 tonnes in 2023, indicating a relatively stable regional supply chain.
- Imports from developing countries showed an overall upward trend despite minor fluctuations, increasing from approximately 350 tonnes in 2019 to around 450 tonnes in 2023.
- Developing country imports experienced a dip during 2020–2021 before recovering strongly in 2022 and reaching the highest level in 2023.
- Imports from the rest of the world remained comparatively small, ranging between 20 and 70 tonnes over the five-year period.
- The highest imports from the rest of the world were recorded in 2022, followed by a decline in 2023.
- 2021 marked the lowest level of Intra-European imports, falling to approximately 2,950 tonnes before rebounding in 2022.
- The gap between Intra-European imports and imports from developing countries remained substantial, highlighting Europe’s strong dependence on regional suppliers.
- The steady increase in imports from developing countries suggests growing diversification of Europe’s frozen vegetable sourcing strategy.
- Overall, the chart indicates that Europe continues to rely primarily on intra-European trade, while imports from developing countries are gradually becoming more significant in the frozen vegetables market.
Growth Driver
Rising Consumer Demand for Convenient and Healthy Food Products
The increasing demand for convenient yet nutritious food products is one of the strongest growth drivers for the global frozen vegetables market. Rapid urbanization, busy work schedules, and the growing number of dual-income households have significantly increased the preference for ready-to-cook and easy-to-store food items. Frozen vegetables provide a practical solution by offering minimal preparation time while maintaining nutritional quality. According to the United Nations, nearly 57% of the global population lived in urban areas in 2025, and this figure is projected to exceed 68% by 2050, creating sustained demand for convenient food solutions. The International Institute of Refrigeration estimates that the global cold chain industry handles over 620 million metric tons of frozen and chilled food annually, with vegetables accounting for a substantial share. Furthermore, studies indicate that frozen vegetables can retain over 90% of vitamins such as vitamin C, folate, and beta-carotene when properly processed. Growing awareness about reducing food waste has also increased adoption, as frozen vegetables typically have a shelf life of 8–24 months, significantly longer than fresh produce, making them attractive for households and foodservice operators worldwide.
Expansion of Cold Chain Infrastructure and Organized Retail Networks
The rapid expansion of cold storage facilities, refrigerated transportation, and organized retail has significantly accelerated the frozen vegetables market worldwide. Investments in cold chain logistics have enabled manufacturers to distribute frozen vegetables efficiently while maintaining product quality across domestic and international markets. According to the International Association of Refrigerated Warehouses, global refrigerated warehouse capacity has surpassed 750 million cubic meters, reflecting continuous infrastructure development. Emerging economies in Asia-Pacific, Latin America, and the Middle East are witnessing substantial investments in temperature-controlled logistics, improving product availability in both urban and semi-urban regions. In addition, supermarkets, hypermarkets, and online grocery platforms have expanded frozen food sections to meet rising consumer demand. Retail industry data suggest that frozen food categories contribute 10–15% of total supermarket food sales in many developed markets. The increasing penetration of e-commerce grocery services further supports market growth by offering home delivery of frozen products through specialized insulated packaging and refrigerated delivery networks. These developments reduce product losses, improve supply chain efficiency, and encourage manufacturers to expand frozen vegetable portfolios globally.
Growing Foodservice Industry and Increasing Demand from Food Manufacturers
The expanding global foodservice industry has become a major contributor to frozen vegetable market growth. Restaurants, hotels, quick-service restaurants (QSRs), catering companies, institutional kitchens, and ready-meal manufacturers increasingly rely on frozen vegetables because they offer consistent quality, standardized portion sizes, lower labor costs, and year-round availability. According to the World Travel & Tourism Council, international tourism has largely recovered, resulting in rising foodservice consumption across hospitality sectors. The global quick-service restaurant industry serves hundreds of millions of meals daily, creating significant demand for frozen peas, corn, broccoli, spinach, carrots, and mixed vegetables used in pizzas, burgers, pasta, soups, and ready-to-eat meals. Additionally, food manufacturers increasingly utilize frozen vegetables in frozen dinners, canned products, snacks, and meal kits due to their predictable quality and extended storage life. Studies indicate that food manufacturers can reduce ingredient waste by 20–30% through the use of frozen vegetables compared to fresh alternatives. The continuous expansion of processed food production, coupled with increasing consumer preference for convenient meal solutions, is expected to sustain long-term demand across global markets.
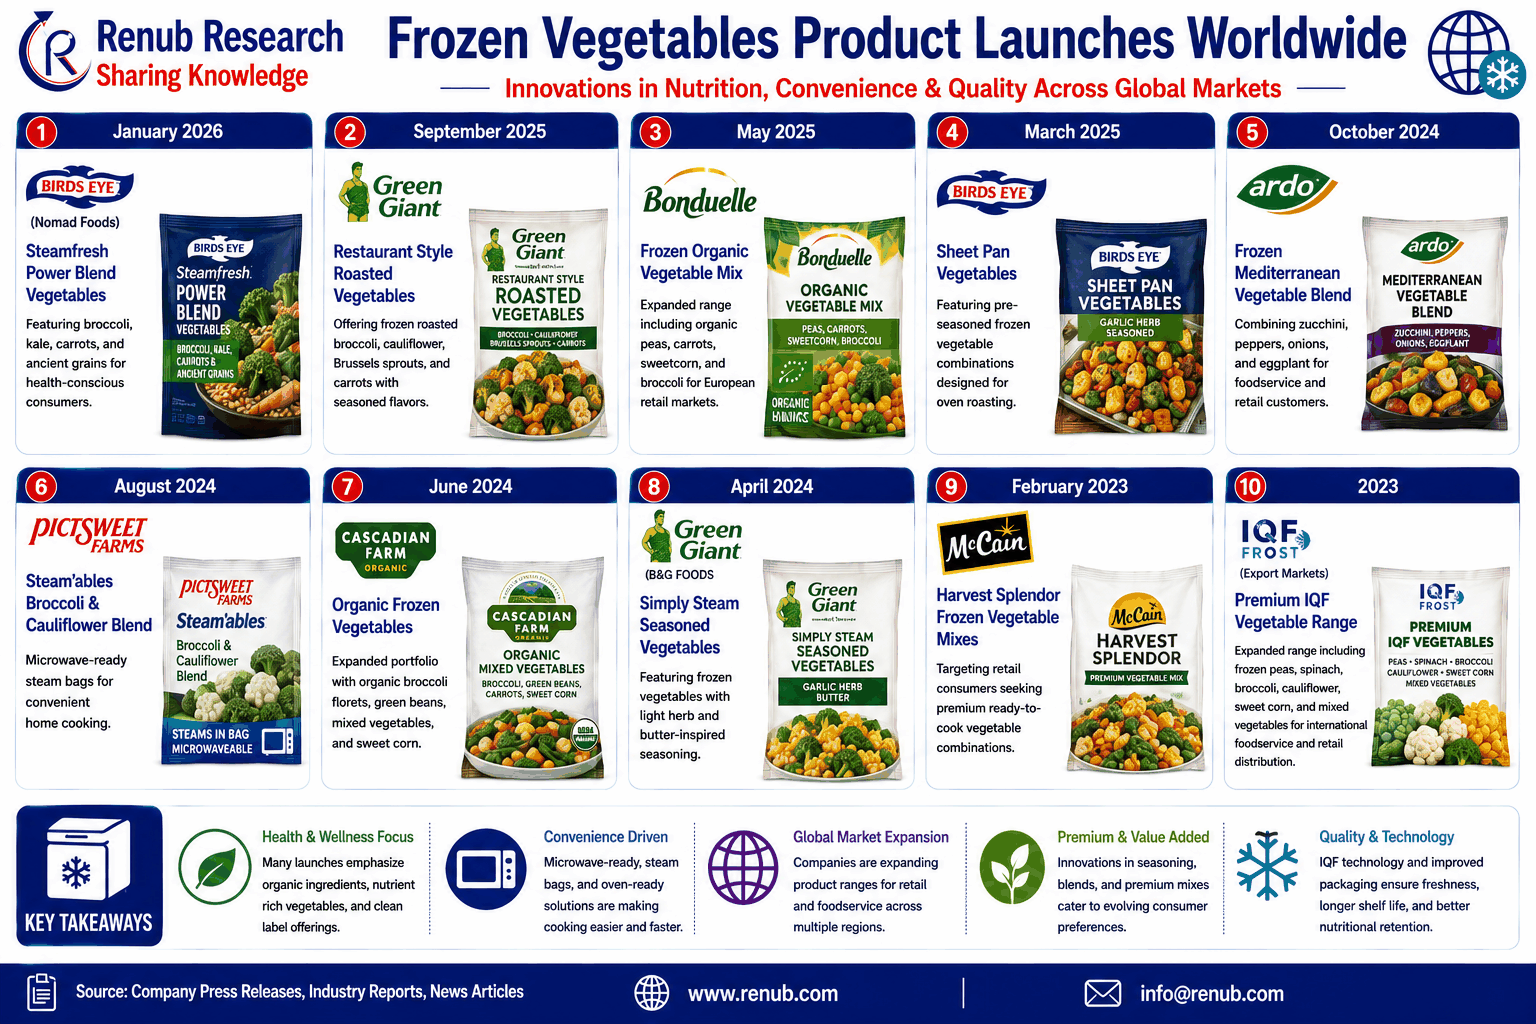
Frozen Vegetables Product Launches Worldwide
- Birds Eye (Nomad Foods) – Steamfresh Power Blend Vegetables launched in January 2026, featuring broccoli, kale, carrots, and ancient grains for health-conscious consumers.
- Green Giant – Introduced Restaurant Style Roasted Vegetables in September 2025, offering frozen roasted broccoli, cauliflower, Brussels sprouts, and carrots with seasoned flavors.
- Bonduelle – Expanded its Frozen Organic Vegetable Mix range in May 2025, including organic peas, carrots, sweetcorn, and broccoli for European retail markets.
- Birds Eye – Launched Sheet Pan Vegetables in March 2025, featuring pre-seasoned frozen vegetable combinations designed for oven roasting.
- Ardo – Released Frozen Mediterranean Vegetable Blend in October 2024, combining zucchini, peppers, onions, and eggplant for foodservice and retail customers.
- Pictsweet Farms – Introduced Steam’ables Broccoli & Cauliflower Blend in August 2024, packaged in microwave-ready steam bags for convenient home cooking.
- Cascadian Farm – Expanded its Organic Frozen Vegetables portfolio in June 2024 with organic broccoli florets, green beans, mixed vegetables, and sweet corn.
- B&G Foods (Green Giant) – Launched Simply Steam Seasoned Vegetables in April 2024, featuring frozen vegetables with light herb and butter-inspired seasoning.
- McCain Foods – Introduced Harvest Splendor Frozen Vegetable Mixes in February 2023, targeting retail consumers seeking premium ready-to-cook vegetable combinations.
- IQF Frost (Export Markets) – Expanded its Premium Individually Quick Frozen (IQF) Vegetable Range in 2023, including frozen peas, spinach, broccoli, cauliflower, sweet corn, and mixed vegetables for international foodservice and retail distribution.
Challenge
High Energy Costs and Cold Chain Infrastructure Requirements
One of the primary challenges facing the frozen vegetables market is the high operational cost associated with freezing, refrigerated transportation, and cold storage infrastructure. Maintaining temperatures of approximately –18°C or lower throughout the supply chain requires significant electricity consumption and continuous investment in refrigeration equipment. According to the International Energy Agency (IEA), refrigeration and air-conditioning systems account for approximately 17–20% of global electricity consumption, making energy costs a critical expense for frozen food producers and distributors. Rising electricity prices, fuel costs, and maintenance expenses directly impact production costs and profit margins. Developing countries often face limited cold storage capacity and unreliable electricity supplies, leading to higher spoilage rates and restricted market penetration. Small-scale producers frequently struggle to invest in advanced freezing technologies and refrigerated logistics due to high capital requirements. Furthermore, disruptions in power supply or transportation delays can compromise product quality, resulting in financial losses. These infrastructure challenges remain a major barrier to market expansion, particularly in emerging economies where cold chain development continues to lag behind growing consumer demand.
Consumer Preference for Fresh Produce and Price Sensitivity
Despite the nutritional benefits of frozen vegetables, consumer perception continues to present a significant challenge for market growth. Many consumers, particularly in developing regions, still associate fresh vegetables with superior taste, texture, and nutritional value, even though scientific studies demonstrate that properly frozen vegetables retain comparable nutrient levels. According to the Food and Agriculture Organization (FAO), global per capita vegetable consumption continues to be dominated by fresh produce, especially in Asia and Africa, where traditional food purchasing habits remain strong. In addition, frozen vegetables generally involve higher production, storage, packaging, and transportation costs than locally sourced fresh vegetables, leading to premium retail prices in several markets. Inflation and rising food prices have further increased consumer price sensitivity, encouraging households to choose lower-cost fresh alternatives when available. Seasonal availability of inexpensive fresh vegetables in agricultural regions also reduces demand for frozen products during harvest periods. Overcoming consumer misconceptions through education, product innovation, and competitive pricing remains essential for expanding frozen vegetable adoption across price-sensitive and emerging global markets.
Rising Demand for Frozen Broccoli: Nutrient-Rich Convenience Foods
Frozen broccoli represents one of the fastest-growing categories within the global frozen vegetables market due to its exceptional nutritional profile and broad culinary applications. Rich in vitamin C, vitamin K, dietary fiber, folate, and antioxidants, frozen broccoli is increasingly preferred by health-conscious consumers seeking convenient meal options without compromising nutritional quality. Industry estimates indicate that broccoli accounts for approximately 10–15% of the global frozen vegetable category in value terms. The product is extensively used in ready meals, soups, stir-fries, pasta dishes, salads, casseroles, and frozen food formulations. IQF (Individually Quick Frozen) technology preserves texture, color, and nutritional value while extending shelf life to 12–24 months, reducing food waste throughout the supply chain. North America and Europe remain the largest consumers due to strong retail penetration and high frozen food consumption, while Asia-Pacific is witnessing the fastest growth driven by urbanization and increasing disposable incomes. Growing vegan, vegetarian, and plant-based dietary trends further support demand, encouraging manufacturers to introduce organic, preservative-free, and sustainably packaged frozen broccoli products across global retail and foodservice channels.
Frozen Green Peas Strong Demand Across Household and Food Processing Industries
Frozen green peas remain among the highest-volume products in the frozen vegetables industry because of their versatility, affordability, and year-round availability. Green peas contain high levels of protein, fiber, vitamin C, vitamin K, and essential minerals, making them suitable for both household consumption and industrial food manufacturing. Industry assessments suggest frozen green peas contribute approximately 18–22% of total frozen vegetable sales globally by volume, making them one of the largest product segments. They are widely used in curries, soups, rice dishes, frozen snacks, ready-to-eat meals, canned food alternatives, and institutional catering. Individually Quick Frozen technology enables peas to maintain their shape, sweetness, and nutritional quality while reducing post-harvest losses. Food manufacturers increasingly prefer frozen peas due to standardized quality and reduced processing waste. Rising urban populations, increasing demand for convenient cooking ingredients, and expanding supermarket distribution networks continue supporting market growth. Emerging economies are also experiencing increasing consumption as cold chain infrastructure improves, allowing frozen green peas to reach new consumer markets with greater efficiency and affordability.
Frozen Mushroom Expanding Applications in Processed and Premium Food Products
The frozen mushroom market has experienced significant expansion due to increasing demand from both household consumers and commercial food manufacturers. Mushrooms such as button, shiitake, oyster, and portobello are widely frozen to preserve freshness while extending shelf life for year-round availability. Mushrooms are naturally rich in B vitamins, selenium, potassium, antioxidants, and dietary fiber while remaining low in calories, making them attractive ingredients in healthy diets. Industry estimates indicate mushrooms account for approximately 5–8% of the global frozen vegetable category, with steady annual demand growth from restaurants and processed food manufacturers. Frozen mushrooms are commonly used in pizzas, pasta sauces, soups, ready meals, frozen snacks, and premium culinary products. Foodservice operators benefit from reduced cleaning and trimming requirements, lowering labor costs and minimizing kitchen waste. Improvements in freezing technology have significantly enhanced texture retention after thawing, increasing consumer acceptance. Growing vegetarian and flexitarian lifestyles, combined with rising demand for plant-based protein alternatives, continue expanding frozen mushroom consumption across North America, Europe, and rapidly developing Asian food markets.
Frozen Vegetables Retail Customers Growing Household Consumption Worldwide
Retail customers constitute the largest consumer group in the frozen vegetables market, driven by increasing demand for convenience, healthy eating, and long-lasting food products. Household consumers purchase frozen vegetables primarily through supermarkets, hypermarkets, convenience stores, and online grocery platforms. Industry estimates suggest the retail segment accounts for approximately 65–70% of total frozen vegetable sales worldwide, reflecting widespread consumer acceptance across developed economies. Frozen vegetables offer consumers year-round access to seasonal produce while reducing food waste through extended shelf life of up to 24 months under proper storage conditions. Increasing participation of women in the workforce, smaller household sizes, and busier lifestyles have accelerated demand for ready-to-cook vegetable products. Premium retail offerings such as organic vegetables, mixed vegetable blends, microwave-ready packaging, and steamable bags have further expanded consumer choices. Rising health awareness following recent global public health trends has also encouraged consumers to stock frozen vegetables as reliable pantry essentials. Continuous product innovation and expanding retail availability continue strengthening this dominant customer segment worldwide.
Frozen Vegetables Supermarket/Hypermarket Dominant Distribution Channel Driving Global Sales
Supermarkets and hypermarkets remain the leading distribution channel for frozen vegetables due to their extensive product selection, advanced refrigeration facilities, and strong consumer accessibility. Industry analysis indicates that supermarkets and hypermarkets account for approximately 55–65% of global frozen vegetable retail sales, making them the dominant sales channel worldwide. Large retail chains provide dedicated frozen food sections that enable consumers to compare brands, packaging sizes, and product varieties in a single location. Frequent promotional campaigns, loyalty programs, and private-label frozen vegetable offerings have increased product affordability while strengthening customer retention. Modern retailers also maintain sophisticated cold chain systems that preserve product quality from warehouse to retail shelf, minimizing spoilage and ensuring food safety. Expansion of organized retail in emerging economies, particularly across Asia-Pacific, Latin America, and the Middle East, continues increasing frozen vegetable accessibility among middle-income consumers. Additionally, supermarkets increasingly integrate online ordering and home delivery services, allowing frozen products to reach consumers through omnichannel retail models. These factors position supermarkets and hypermarkets as the most influential distribution channel supporting long-term global frozen vegetable market growth.
United States Frozen Vegetables Mature Retail Infrastructure and High Consumer Adoption
The United States represents one of the largest frozen vegetables markets globally, supported by advanced cold chain infrastructure, high frozen food consumption, and strong retail penetration. Industry estimates indicate that over 90% of U.S. households purchase frozen foods at least once annually, while frozen vegetables account for a significant share of the country’s frozen food category. Americans consume millions of metric tons of frozen vegetables each year, with products such as broccoli, green peas, corn, spinach, mixed vegetables, and green beans leading sales. The country’s well-developed supermarket, warehouse club, and online grocery ecosystem ensures widespread product availability across urban and rural regions. Individually Quick Frozen (IQF) technology enables manufacturers to preserve nutritional quality while offering shelf lives of 12–24 months, reducing household food waste. Rising health awareness has accelerated demand for organic, low-sodium, microwave-ready, and steamable frozen vegetables. The expanding ready-to-eat meal industry, foodservice sector, and institutional catering further strengthen market demand. Continuous product innovation, sustainable packaging initiatives, and increasing consumer preference for convenient meal preparation continue positioning the United States as one of the world’s most stable and high-value frozen vegetables markets.
China Frozen Vegetables Expanding Production Capacity and Export Leadership
China has emerged as one of the world’s largest producers and exporters of frozen vegetables, supported by its extensive agricultural resources, competitive manufacturing base, and expanding cold chain infrastructure. The country processes millions of metric tons of vegetables annually for both domestic consumption and international exports. Frozen products including peas, sweet corn, broccoli, spinach, mushrooms, carrots, and mixed vegetables are widely supplied to North America, Europe, Japan, and Southeast Asia. Rapid urbanization has resulted in more than 65% of China’s population living in urban areas, significantly increasing demand for convenient frozen food products among working households. The rapid expansion of modern supermarkets, e-commerce grocery platforms, and refrigerated logistics has improved nationwide accessibility. China’s frozen vegetable industry also benefits from increasing automation in food processing plants and improved IQF technology, enhancing export-quality standards and product consistency. Government investments in food safety systems and agricultural modernization have strengthened manufacturing capabilities. Rising disposable incomes, changing dietary habits, and increasing demand for premium packaged foods are expected to drive continuous domestic market expansion alongside China’s strong position in global frozen vegetable exports.
Spain Frozen Vegetables Strong Agricultural Base Supporting European Demand
Spain occupies a strategic position in the European frozen vegetables market due to its highly productive agricultural sector, favorable climate, and well-established food processing industry. The country is among Europe’s leading producers of vegetables such as peas, spinach, broccoli, green beans, peppers, and artichokes, supplying both domestic retailers and international export markets. Agriculture contributes significantly to Spain’s food manufacturing industry, while frozen vegetables have become an important value-added export category. Advanced freezing technologies and efficient logistics allow Spanish manufacturers to preserve product quality throughout European distribution networks. Domestic demand continues growing as consumers increasingly seek convenient, healthy meal solutions supported by expanding supermarket and hypermarket penetration. Spain’s hospitality industry, serving tens of millions of international tourists annually, also contributes significantly to frozen vegetable consumption through restaurants, hotels, and catering services. Manufacturers increasingly focus on organic production, sustainable farming, recyclable packaging, and premium vegetable blends to meet evolving consumer preferences. Continuous investments in processing efficiency, export capabilities, and environmentally responsible production practices continue strengthening Spain’s position as a major European frozen vegetable manufacturing and distribution hub.
UAE Frozen Vegetables Import-Driven Growth Supported by Retail and Hospitality Expansion
The United Arab Emirates has become one of the fastest-growing frozen vegetables markets in the Middle East due to rapid urbanization, high disposable incomes, limited domestic agricultural production, and strong dependence on food imports. More than 85% of the UAE population resides in urban areas, creating substantial demand for convenient packaged food products. Frozen vegetables such as broccoli, green peas, corn, spinach, mixed vegetables, and beans are primarily imported from Europe, Asia, and neighboring countries through well-developed logistics networks. The country’s modern retail sector, including supermarkets, hypermarkets, convenience stores, and online grocery platforms, provides extensive frozen food availability throughout major cities. The hospitality sector, supported by millions of international tourists and business travelers each year, significantly increases demand from hotels, restaurants, airlines, and institutional catering companies. Investments in advanced cold storage facilities, temperature-controlled transportation, and food security initiatives have strengthened supply chain efficiency. Growing health awareness, increasing expatriate populations, and rising demand for premium, organic, and ready-to-cook food products continue to drive long-term growth in the UAE frozen vegetables market.
Recent Developments in Frozen Vegetables Market
- September 2024: Green Giant rolled out a lineup of twelve new frozen vegetable products, including items like Crispy Smashed Potatoes, Corn Cob Bites, Veggie Ramen, and Roasting Veggies. The launch targets consumers seeking affordable, easy-to-prepare meal solutions.
- April 2024: McCain Foods expanded its collaboration with Strong Roots, a frozen food company based in Dublin. Building on their earlier strategic alliance, McCain has increased its investment to broaden the shared product portfolio and promote sustainable, vegetable-focused food choices across global markets.
- March 2024: BigBasket, a major online grocery platform in India, unveiled its new frozen food label, Precia. The brand offers three nationwide product lines—frozen vegetables, frozen snacks, and frozen desserts—aimed at meeting rising demand for convenient frozen options.
Market Segmentation
Product
- Corn
- Asparagus
- Spinach
- Green Peas
- Broccoli
- Mushroom
- Green Beans
- Others
End-User
- Food Service Industry
- Retail Customers
Distribution Channel
- Discounters
- Supermarket/Hypermarket
- Others
Countries
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Malaysia
- Indonesia
- Australia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- Saudi Arabia
- UAE
- South Africa
All the Key players have been covered from 5 Viewpoints:
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Company Analysis:
- General Mills Inc.
- Conagra Brands
- Hormel Foods
- Unilever PLC
- The Kraft Heinz Company
- Nomad Foods Ltd
- B&G Foods, Inc.
- Greenyard
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Product, End User, Distribution Channel, and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.