Europe Non-Invasive Prenatal Testing Market Report by Component, Application, End User, Countries and Companies Analysis 2026-2034
Buy NowEurope Non-Invasive Prenatal Testing Market Size and Forecast
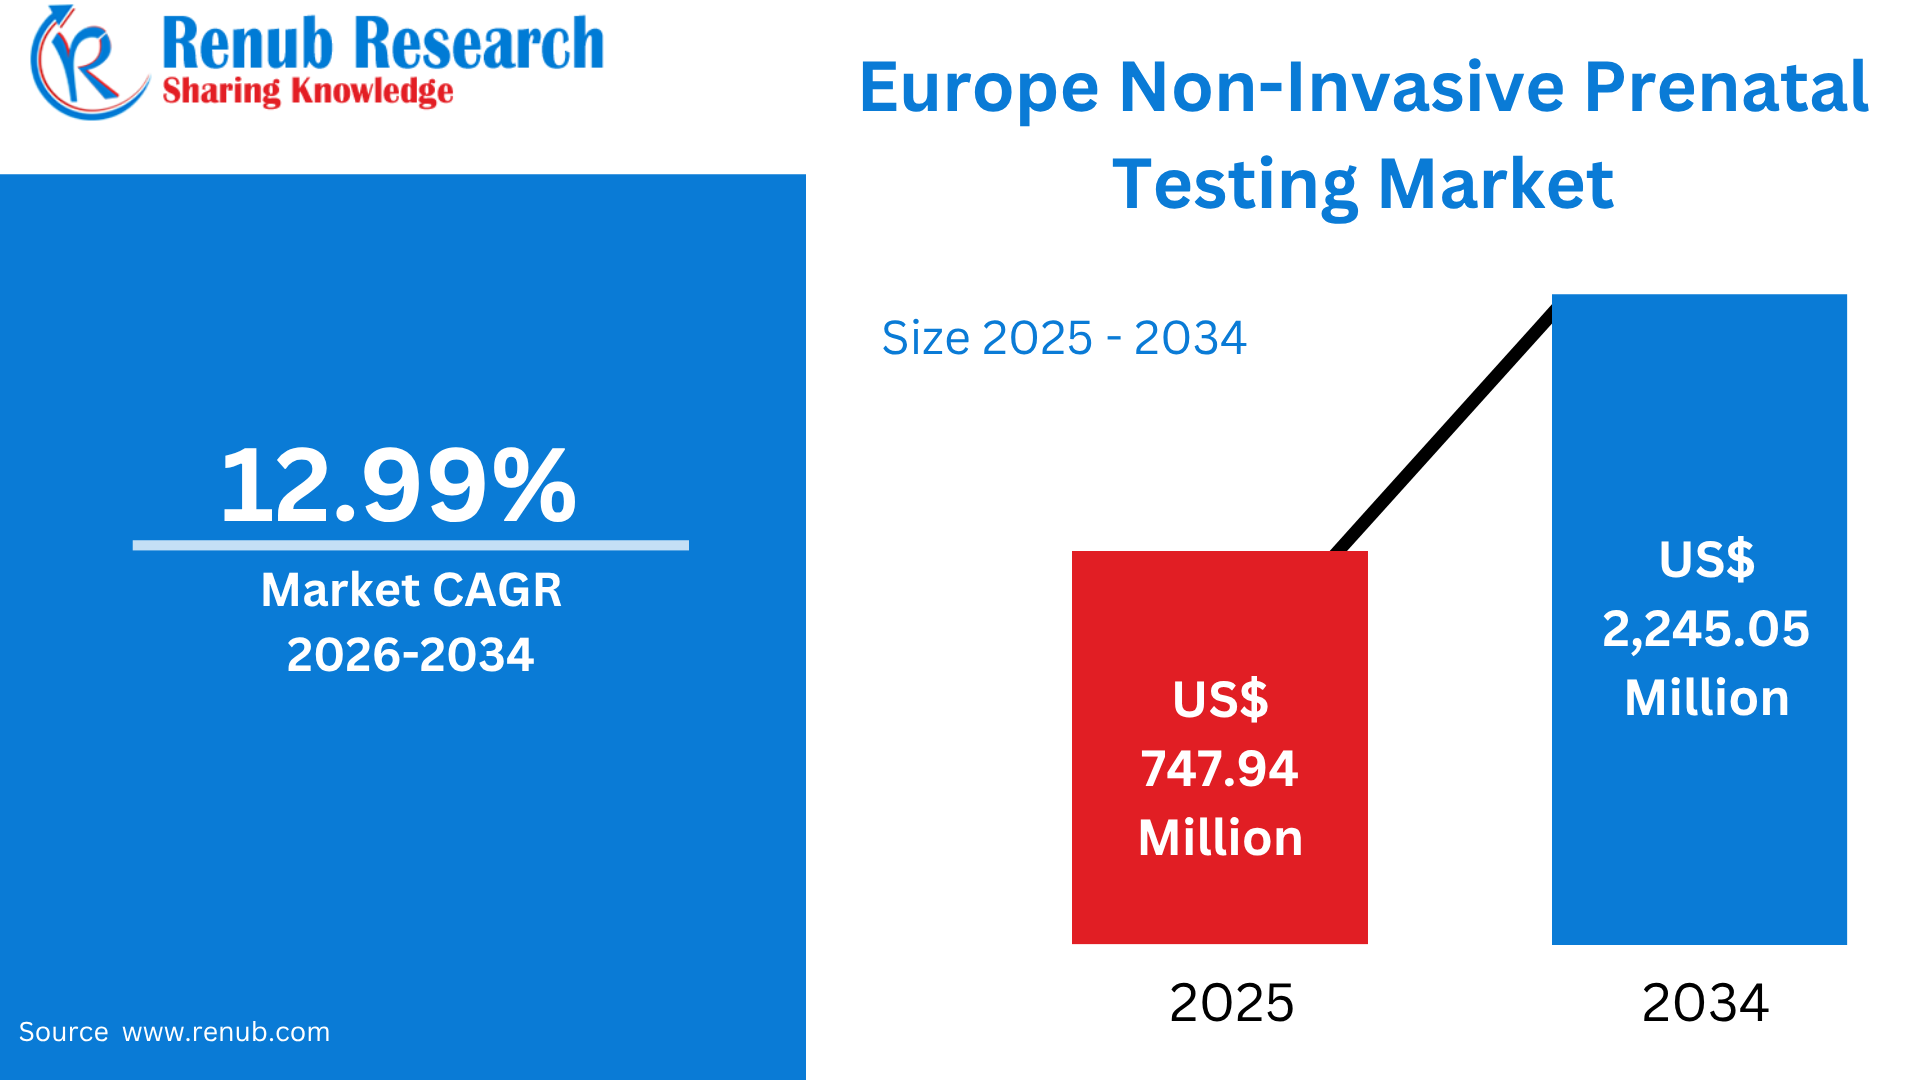
Europe Non-Invasive Prenatal Testing (NIPT) Market is expected to expand from US$ 747.94 million in 2025 to approximately US$ 2,245.05 million by 2034, registering a CAGR of 12.99% during 2026–2034. Market growth is supported by increasing awareness and adoption of prenatal genetic screening, rising maternal age, and ongoing advancements in genomic sequencing and molecular diagnostic technologies. In addition, expanding access to prenatal healthcare services and the growing preference for safe, non-invasive diagnostic approaches are contributing to greater NIPT adoption across Europe.
What is Non-Invasive Prenatal Testing and its Uses & Popularity in Europe
Non-Invasive Prenatal Testing (NIPT), also known as cell-free DNA (cfDNA) screening, is a prenatal blood test that analyzes small fragments of DNA released by the placenta into the pregnant woman’s bloodstream. It is primarily used to assess the likelihood of common fetal chromosomal abnormalities, particularly Down syndrome (trisomy 21), Edwards syndrome (trisomy 18), and Patau syndrome (trisomy 13). NIPT can generally be performed from around 10 weeks of pregnancy and does not involve inserting instruments into the uterus, making it an attractive alternative to invasive diagnostic procedures for initial screening.
NIPT is gaining importance across Europe as maternal age increases and healthcare systems place greater emphasis on early prenatal screening. In 2024, the average age of first-time mothers in the EU reached 29.9 years, up from 28.9 years in 2014. Approximately 6% of EU births in 2024 were to mothers aged 40 or older, double the 2004 share. These demographic changes, combined with improvements in genomic sequencing, growing genetic-awareness, and expanding access to prenatal services, are supporting demand for NIPT throughout European markets.
Chromosomal Screening Statistics in Top 10 European Countries
- France: EUROCAT data for 2018–2022 recorded a total prevalence of termination of pregnancy for fetal anomaly (TOPFA) of 8.35 per 1,000 births in the covered French registries, reflecting substantial prenatal detection and follow-up of fetal anomalies. France also has established first-trimester screening pathways for chromosomal abnormalities.
- Italy: The Italian EUROCAT registries reported a TOPFA prevalence of 7.17 per 1,000 births during 2018–2022. Italy’s prenatal screening landscape includes risk assessment for chromosomal abnormalities, with regional differences in access and implementation.
- Spain: The Valencian Region registry reported a TOPFA prevalence of 6.90 per 1,000 births in 2018–2022. Prenatal screening commonly incorporates ultrasound and maternal blood testing to assess risks for trisomies 21, 18 and 13.
- United Kingdom: EUROCAT UK registries reported a TOPFA prevalence of 5.55 per 1,000 births for 2018–2022. The UK has established prenatal screening pathways for Down syndrome, Edwards syndrome and Patau syndrome, with further diagnostic testing used following higher-risk screening results.
- Netherlands: The Northern Netherlands EUROCAT registry recorded a TOPFA prevalence of 5.97 per 1,000 births in 2018–2022. European prenatal screening commonly combines ultrasound findings and maternal blood testing to estimate chromosomal-abnormality risk.
- Belgium: Belgian EUROCAT registries recorded a TOPFA prevalence of 4.64 per 1,000 births during 2018–2022. Belgium participates in European prenatal-diagnosis surveillance, including detection of chromosomal and other congenital anomalies.
- Germany: The Saxony-Anhalt EUROCAT registry reported a TOPFA prevalence of 3.96 per 1,000 births in 2018–2022. Germany has established prenatal screening and diagnostic pathways, with non-invasive screening increasingly incorporated into clinical care.
- Austria: The Styria registry recorded a TOPFA prevalence of 3.77 per 1,000 births during 2018–2022. Prenatal assessment in Europe generally includes first-trimester ultrasound and maternal blood-based screening for common chromosomal abnormalities.
- Denmark: The Funen EUROCAT registry reported a TOPFA prevalence of 7.86 per 1,000 births for 2018–2022. Denmark has an established prenatal screening system, and EUROCAT data demonstrate substantial prenatal identification of fetal anomalies.
- Sweden: Sweden is represented in European prenatal-screening surveillance, although the cited EUROCAT table does not provide a national TOPFA figure for Sweden. European screening programs commonly assess trisomies 21, 18 and 13 through first-trimester ultrasound and blood-based risk assessment, with diagnostic testing available for higher-risk pregnancies.
Growth Driver of the Europe Non-Invasive Prenatal Testing Market
Rising Maternal Age and Increasing Need for Chromosomal Screening
The increasing age at which European women have their first child is an important factor supporting demand for NIPT. Eurostat reports that the mean age of first-time mothers in the EU increased to 29.9 years in 2024, compared with 28.9 years in 2014. Italy recorded the highest average age at first birth at 31.9 years, followed by Luxembourg at 31.6 years and Spain at 31.5 years. In addition, approximately 6% of babies born in the EU in 2024 were delivered to mothers aged 40 years or older, compared with 3% in 2004. Advanced maternal age is associated with an increased risk of fetal chromosomal abnormalities, making prenatal genetic screening increasingly relevant for older expectant mothers. NIPT provides a blood-based screening option that can assess the risk of common aneuploidies without requiring an invasive procedure. Although NIPT is relevant to pregnant women of all ages and risk groups, the growing proportion of pregnancies among older mothers is expanding the population seeking prenatal genetic screening. European countries with comparatively high maternal ages, including Italy, Spain and Luxembourg, therefore represent important opportunities for NIPT providers.
Technological Advances Improving NIPT Screening Performance
Continuous improvements in cell-free DNA analysis, genomic sequencing, bioinformatics and laboratory technologies are strengthening the capabilities of NIPT and supporting its adoption. The technology analyzes placental DNA circulating in maternal blood and can screen for common fetal aneuploidies without the fetal exposure associated with invasive procedures. Current clinical guidance identifies cfDNA as the most sensitive and specific screening test for common fetal aneuploidies, particularly trisomies 21, 18 and 13. Technological progress is also expanding the range of applications being investigated and commercialized, including screening approaches involving sex-chromosome abnormalities and other genetic conditions. However, clinical recommendations remain selective for some newer applications. For example, current guidance does not recommend routine population screening for microdeletion conditions using cfDNA. As sequencing platforms become more efficient and laboratory workflows improve, NIPT providers can potentially deliver faster and more comprehensive screening services. These advances, combined with increasing availability of specialized genomic laboratories across Europe, are expected to support continued market development.
Growing Adoption of Early and Non-Invasive Prenatal Screening
Growing emphasis on early detection and patient-centered prenatal care is supporting the adoption of non-invasive screening technologies across Europe. NIPT can be performed from approximately 10 weeks of pregnancy, allowing prospective parents to receive screening information relatively early in gestation. Its blood-based nature also avoids the procedural risks associated with invasive diagnostic techniques, although a positive screening result requires follow-up diagnostic testing. The broader European prenatal-care infrastructure provides an important foundation for market expansion. The EUROCAT network, which monitors congenital anomalies across Europe, publishes prenatal detection data covering 2019–2023, demonstrating the continuing role of prenatal screening and diagnosis in European healthcare systems. At the same time, clinical guidance increasingly recognizes cfDNA as a first-line screening option for common fetal aneuploidies. Greater awareness among expectant parents, improved access to genetic counseling, and the integration of genomic testing into prenatal-care pathways can therefore increase NIPT utilization. Private laboratories, hospitals and specialized diagnostic centers are also expanding testing availability, creating additional opportunities for market growth.
Challenges of the Europe Non-Invasive Prenatal Testing Market
High Testing Costs and Unequal Reimbursement Across Europe
The cost of NIPT and differences in reimbursement policies represent important challenges for market expansion across Europe. Although NIPT has become increasingly established as a prenatal screening technology, access can differ depending on national healthcare policies, insurance arrangements, clinical indications and whether testing is provided through public or private healthcare channels. These differences can create variation in adoption rates between European countries and between patient groups.
The economic barrier is particularly relevant because NIPT is a screening test rather than a definitive diagnostic procedure. A positive NIPT result generally requires genetic counseling and confirmatory diagnostic testing such as chorionic villus sampling or amniocentesis. Consequently, the overall cost of a prenatal testing pathway can extend beyond the initial NIPT test. Current clinical guidance also emphasizes considering test performance, availability, cost, individual risk and patient preferences when selecting screening approaches. Differences in public reimbursement and private-pay requirements may therefore influence affordability and limit uniform NIPT penetration across European markets.
Regulatory, Clinical and Interpretation Challenges
Regulatory requirements, clinical interpretation and the need for appropriate genetic counseling remain significant challenges for the European NIPT market. NIPT provides a probability or risk assessment rather than a definitive diagnosis. A positive result does not establish that a fetus has a chromosomal abnormality, while false-positive and false-negative results remain possible. Therefore, professional guidance recommends that positive cfDNA results be followed by genetic counseling, detailed ultrasound assessment and diagnostic testing. The rapid development of new NIPT applications also creates challenges in determining which tests have sufficient clinical evidence for routine use. Current guidance supports cfDNA screening for common aneuploidies but does not recommend routine general-population screening for microdeletion conditions, illustrating the importance of evidence-based clinical validation. In addition, differences in healthcare systems, laboratory standards, reimbursement frameworks and national approaches to prenatal screening can complicate market access across Europe. Providers must therefore maintain analytical accuracy, appropriate counseling procedures, transparent reporting and compliance with applicable regulatory requirements while communicating the limitations of screening clearly to patients.
NIPT Product Launches in Europe
- 2025 – Roche: Harmony NIPT Expansion Across Europe
Roche expanded the availability of its Harmony Non-Invasive Prenatal Test (NIPT) across selected European markets through collaborations with hospitals, laboratories, and prenatal-care providers. - 2025 – Illumina: VeriSeq NIPT Solution v2 Adoption in Europe
Illumina supported the broader implementation of the VeriSeq NIPT Solution v2, an NGS-based prenatal screening platform designed to enable laboratories to analyze cell-free DNA for common fetal chromosomal abnormalities. - 2024 – Natera: Panorama NIPT Expansion in European Markets
Natera increased the availability of its Panorama NIPT services through European laboratory and healthcare partnerships, providing expanded access to cfDNA-based prenatal screening. - 2024 – Eurofins Clinical Genetics: Expanded NIPT Screening Services
Eurofins Clinical Genetics broadened its prenatal screening offerings in Europe, incorporating additional chromosomal assessment capabilities and expanding access to genomic testing services. - 2024 – LifeCodexx: PraenaTest Expansion in Germany and Europe
LifeCodexx expanded its PraenaTest portfolio, a cfDNA-based prenatal screening service, supporting the wider use of non-invasive screening for common chromosomal abnormalities. - 2023 – BGI Genomics: NIFTY NIPT European Expansion
BGI Genomics continued expanding the availability of its NIFTY prenatal testing service through partnerships with laboratories and healthcare providers across European markets. - 2023 – PerkinElmer: Next-Generation NIPT Workflow Development
PerkinElmer expanded the use of next-generation sequencing and laboratory workflow solutions for prenatal genetic screening, supporting clinical laboratories seeking scalable NIPT testing capabilities. - 2023 – Yourgene Health: IONA Nx NIPT Platform Expansion
Yourgene Health broadened adoption of the IONA Nx NIPT platform in European clinical laboratories. The sequencing-based solution supports screening for common fetal chromosomal abnormalities using maternal blood samples. - 2022 – Thermo Fisher Scientific: Ion Torrent NIPT Workflow Enhancement
Thermo Fisher Scientific advanced the use of its Ion Torrent sequencing technology for prenatal screening applications, providing laboratories with sequencing-based workflows for cfDNA analysis. - 2022 – Roche/Ariosa Diagnostics: Harmony NIPT European Expansion
Roche and Ariosa Diagnostics continued expanding access to the Harmony prenatal test in European healthcare networks, supporting wider availability of non-invasive screening for fetal chromosomal abnormalities.
Advanced Genomic Platforms Supporting NIPT Instrument Demand
Europe Non-Invasive Prenatal Testing (NIPT) Instruments Market is expanding as laboratories and healthcare providers increasingly adopt genomic technologies for cell-free DNA screening. NIPT workflows typically rely on next-generation sequencing (NGS), automated sample and DNA-extraction systems, molecular-analysis technologies, and bioinformatics platforms to process maternal blood samples and identify chromosomal abnormalities. Current clinical guidance recognizes cfDNA as the most sensitive and specific screening approach for common fetal aneuploidies, including trisomies 21, 18, and 13. Demand for advanced instruments is also supported by changing European maternal demographics. The average age of first-time mothers in the EU reached 29.9 years in 2024, compared with 28.9 years in 2014. Approximately 6% of babies born in the EU in 2024 were delivered to mothers aged 40 or older, up from 3% in 2004. These demographic trends increase the relevance of prenatal chromosomal screening and encourage investment in laboratory capacity. Automation, higher testing throughput, improved sequencing performance, and sophisticated data-analysis software can help laboratories manage growing sample volumes while maintaining reproducibility. Furthermore, the European Union’s regulatory framework for in-vitro diagnostic devices emphasizes performance, safety, reliability, clinical evidence, and post-market surveillance, supporting demand for compliant and technologically advanced NIPT instrumentation.
Expanding Access to Genetic Screening and Prenatal Counseling
Europe Non-Invasive Prenatal Testing Services Market is growing as cfDNA screening becomes increasingly integrated into prenatal-care pathways. NIPT services involve collecting maternal blood and analyzing placental cell-free DNA to estimate the risk of common chromosomal abnormalities, particularly Down syndrome (trisomy 21), Edwards syndrome (trisomy 18), and Patau syndrome (trisomy 13). Testing can generally begin from approximately 10 weeks of pregnancy, providing screening information relatively early during gestation. Demographic changes are creating a larger population seeking prenatal genetic screening. Eurostat reports that the EU’s mean age of first-time mothers increased to 29.9 years in 2024, while around 3.6 million babies were born in the EU during 2024. Of these births, 6% were to mothers aged 40 or older. Greece recorded the highest proportion of births to women aged 40+, at 11%, followed by Spain at 10%, while Italy and Ireland each recorded 9%. These trends support demand for prenatal screening services across Europe. Laboratories, hospitals, private diagnostic providers, and genetic-counseling networks are expanding service capacity as patients seek accessible and minimally invasive testing. However, NIPT remains a screening rather than diagnostic test, and positive results require appropriate counseling and confirmatory diagnostic testing.
Rising Focus on Trisomy 21 Screening
Europe Down Syndrome Non-Invasive Prenatal Testing Market represents an important application within the broader NIPT industry because Down syndrome, or trisomy 21, is one of the principal chromosomal abnormalities evaluated through cfDNA screening. NIPT analyzes placental DNA circulating in maternal blood and provides a risk assessment without requiring an invasive procedure. Current clinical guidance identifies cfDNA as the most sensitive and specific screening test for common fetal aneuploidies, including trisomy 21. Increasing maternal age is an important demographic factor. In 2024, the mean age of first-time mothers in the EU was 29.9 years, while approximately 6% of all EU births occurred among women aged 40 or older. The proportion of births to mothers aged 40+ has doubled since 2004, when it stood at 3%. Because chromosomal-abnormality risk increases with maternal age, the expanding older-mother population contributes to the need for prenatal screening, although NIPT is relevant to pregnant patients regardless of age or baseline risk. Greater awareness of genetic screening, earlier prenatal assessment, and improvements in sequencing and laboratory technologies are supporting adoption. Nevertheless, healthcare providers must clearly communicate that a positive NIPT result indicates increased risk rather than a confirmed diagnosis and should be followed by appropriate diagnostic testing.
Hospital Integration Strengthening NIPT Adoption
Europe Non-Invasive Prenatal Testing Hospitals Market is expanding as hospitals increasingly incorporate genomic screening into maternal and fetal healthcare pathways. Hospitals can support the complete NIPT journey, including prenatal consultation, risk assessment, blood-sample collection, laboratory testing, genetic counseling, interpretation of results, and referral for confirmatory diagnostic procedures when required. The clinical importance of NIPT is increasing as professional guidance recommends cfDNA screening for common fetal aneuploidies, including trisomies 21, 18, and 13. European demographic trends provide an additional demand base. The average age of first-time mothers reached 29.9 years in 2024, while around 3.6 million babies were born in the EU that year. Approximately 6% of births were to women aged 40 or older, with the share reaching 11% in Greece and 10% in Spain. Hospitals are consequently investing in laboratory capabilities, digital diagnostic systems, sample-management infrastructure, and partnerships with specialized genetic-testing laboratories. Regulatory requirements are also shaping hospital procurement and laboratory operations. The EU’s IVDR, applicable since 2022, introduced stronger requirements for the safety, performance, clinical evidence, and oversight of in-vitro diagnostic devices. From 28 May 2026, four EUDAMED modules, including device registration and market surveillance, became mandatory, further strengthening transparency and traceability within the European IVD ecosystem.
France Expanding Prenatal Screening Supported by France’s Healthcare Infrastructure
France Non-Invasive Prenatal Testing (NIPT) Market is supported by growing adoption of genomic screening and increasing emphasis on early identification of fetal chromosomal abnormalities. NIPT uses cell-free DNA from maternal blood to screen primarily for trisomies 21, 18, and 13, providing a non-invasive alternative to initial screening approaches that can lead to invasive diagnostic procedures. France has established a national prenatal screening pathway in which NIPT is offered following an initial assessment of the risk of fetal trisomy 21. The French Haute Autorité de Santé (HAS) recommends cfDNA testing for pregnancies with an estimated trisomy-21 risk between 1 in 51 and 1 in 1,000 following combined screening, while invasive diagnostic testing is generally considered for higher-risk results. France also has a substantial annual birth population, creating a sizeable addressable population for prenatal screening. In 2024, France recorded approximately 663,000 births, although this represented a decline from previous years. Continued development of genomic laboratories, improved awareness, and integration of NIPT into established prenatal-care pathways are supporting market development. However, equitable access, appropriate pre- and post-test counseling, and clear communication that NIPT is a screening rather than diagnostic test remain important considerations.
Germany Clinical Integration and Growing Use of Cell-Free DNA Screening
Germany Non-Invasive Prenatal Testing (NIPT) Market is expanding as cfDNA screening becomes increasingly integrated into prenatal healthcare. NIPT provides a blood-based screening method for common fetal chromosomal abnormalities, particularly trisomies 21, 18, and 13. Germany’s healthcare system has progressively incorporated NIPT into publicly supported prenatal care under defined conditions. Since 1 July 2022, statutory health insurance has covered NIPT for trisomies 13, 18 and 21 in specific circumstances following individual counseling and when the test is considered appropriate. Germany’s demographic profile also creates a substantial need for prenatal screening. According to Destatis, the average age of women giving birth in Germany has continued to increase, reflecting the broader European trend toward later parenthood. In addition, Germany recorded approximately 677,000 live births in 2024, providing a large potential patient base for prenatal screening services. The market is further supported by Germany’s strong laboratory infrastructure, specialist medical centers, and advanced genomic capabilities. At the same time, ethical considerations, informed consent, genetic counseling, and equitable access remain important factors. Continued development of specialist services and standardized patient information can support responsible NIPT adoption across German healthcare settings.
United Kingdom NHS Integration and Expanding Demand for Prenatal Genetic Screening
The United Kingdom Non-Invasive Prenatal Testing (NIPT) Market is developing alongside the country’s established prenatal screening infrastructure and increasing interest in cfDNA-based testing. The NHS offers screening for Down syndrome, Edwards’ syndrome and Patau’s syndrome as part of routine antenatal care. Pregnant women identified as having a higher chance of these conditions following the combined or quadruple screening pathway may be offered further testing, with NIPT available within NHS pathways in relevant circumstances and also offered commercially through private providers. The UK’s large annual birth cohort supports continued demand for prenatal screening services. Approximately 594,000 live births were registered in England and Wales in 2024, according to the Office for National Statistics, although this remained below the levels observed in earlier decades. NIPT adoption is also supported by improvements in sequencing technologies and growing awareness of non-invasive screening. Nevertheless, differences between NHS and private access pathways, regional availability, test costs in private settings, and the need for appropriate counseling can influence uptake. Because NIPT is a screening test rather than a definitive diagnosis, positive results require appropriate follow-up and confirmatory testing. Continued investment in prenatal services, workforce training, and patient education will therefore remain important for market development.
Market Segmentation
Component
- Instruments
- Kits and Reagents
- Services
Application
- Down Syndrome (Trisomy 21)
- Edwards Syndrome (Trisomy 18)
- Patau Syndrome (Trisomy 13)
- Turner Syndrome
- Other Applications
End User
- Hospitals
- Diagnostic Labs
Countries
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Russia
- Poland
- Greece
- Norway
- Romania
- Portugal
- Rest of Europe
All the Key players have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Eurofins Scientific
- F. Hoffmann-La Roche Ltd
- Invitae Corporation
- Illumina Inc.
- Natera Inc.
- Centogene NV
- Qiagen
Report Details:
| Report Features | Details |
| Base Year |
2024 |
| Historical Period |
2021 - 2024 |
| Forecast Period |
2025 - 2033 |
| Market |
US$ Billion |
| Segment Covered |
Component, Application, End User and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.