United States Non-Invasive Prenatal Testing Market Report by Component, Application, End User, States and Companies Analysis 2026-2034
Buy NowUnited States Non-Invasive Prenatal Testing Market Size and Forecast
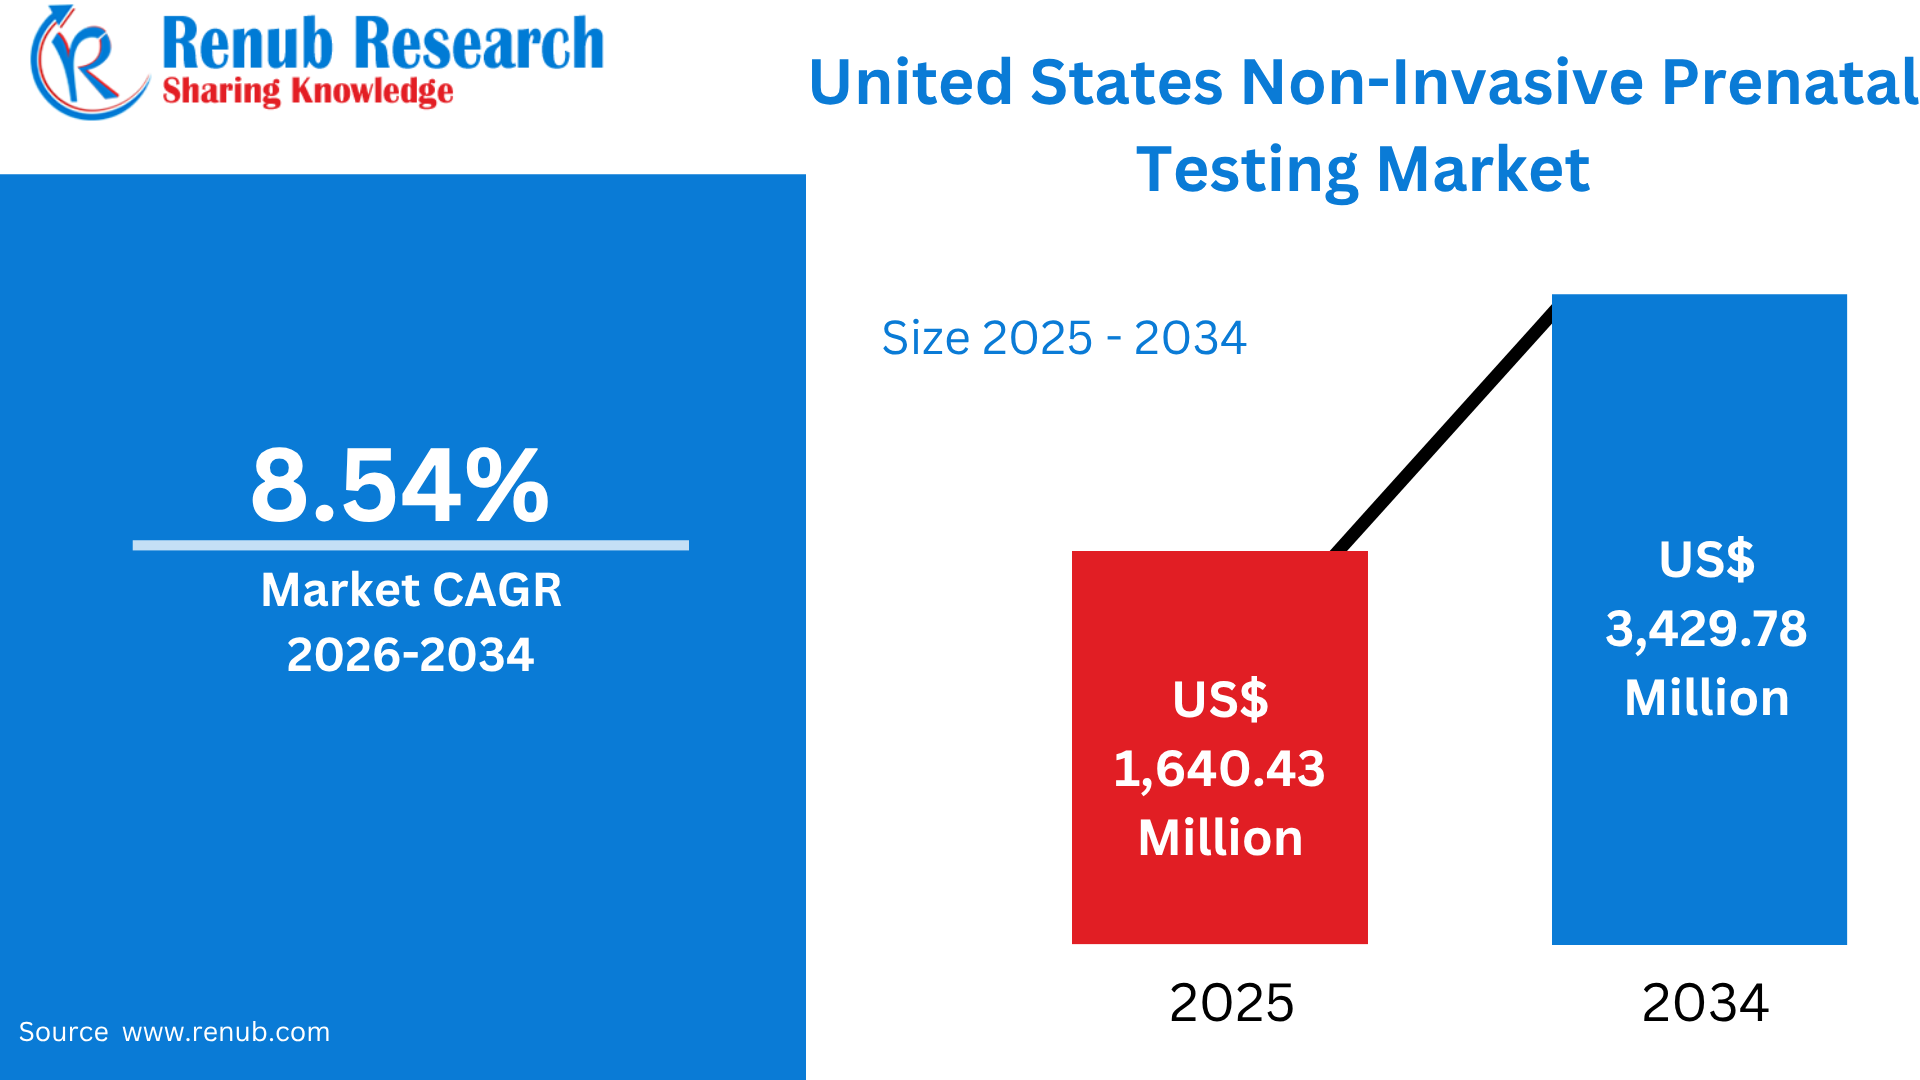
The United States Non-Invasive Prenatal Testing (NIPT) Market is projected to grow from US$ 1,640.43 million in 2025 to US$ 3,429.78 million by 2034, registering a CAGR of 8.54% during 2026–2034. The market is witnessing strong growth due to increasing maternal age, greater awareness of early genetic screening, and rising adoption of cell-free DNA-based testing technologies. NIPT offers a safer and minimally invasive approach to screening for common chromosomal abnormalities, including Down syndrome, Edwards syndrome, and Patau syndrome. Expanding insurance coverage and broader acceptance among healthcare providers are improving access to these tests across the United States.
What is Non-Invasive Prenatal Testing and Its Uses & Popularity in the USA
Non-Invasive Prenatal Testing (NIPT), also known as cell-free DNA (cfDNA) screening, is a blood-based prenatal screening method that analyzes small fragments of fetal DNA circulating in a pregnant woman’s bloodstream. It is generally performed from around 10 weeks of pregnancy and is primarily used to assess the risk of common chromosomal abnormalities, including Down syndrome (trisomy 21), Edwards syndrome (trisomy 18), and Patau syndrome (trisomy 13). NIPT can also provide information about sex chromosome abnormalities and fetal sex in appropriate circumstances. The test is popular in the United States because it provides highly sensitive and specific screening without the miscarriage risk associated with invasive procedures such as amniocentesis or chorionic villus sampling. In January 2026, ACOG endorsed recommendations for cfDNA screening to be routinely available to all obstetrical patients. With 3.63 million U.S. births in 2024, the large pregnancy population provides a substantial addressable market for NIPT services.
Number of live births and general fertility rate: United States, final 2000–2024 and provisional 2025
- Live births in the United States increased from approximately 4.0 million in 2000 to a peak of around 4.3 million in 2007, before declining in subsequent years.
- The number of live births fell to approximately 3.6 million by 2024, indicating a long-term downward trend.
- The general fertility rate was around 65 births per 1,000 females aged 15–44 years in 2000.
- The fertility rate increased during the early 2000s and reached approximately 69 births per 1,000 females in 2007.
- Following 2007, the general fertility rate generally declined, reaching approximately 54 births per 1,000 females aged 15–44 years in 2024.
- In 2020, live births declined noticeably, followed by a modest recovery in 2021–2022.
- The fertility rate continued to trend downward through 2024, despite short-term fluctuations.
- Provisional 2025 data indicate approximately 3.6 million live births, while the general fertility rate remained near 53 births per 1,000 females aged 15–44 years.
- Overall, the figure demonstrates a long-term decline in both the number of live births and the general fertility rate in the United States, particularly since the late 2000s.
- Source: National Center for Health Statistics (NCHS), National Vital Statistics System, natality data file.
Growth Drivers of the United States Non-Invasive Prenatal Testing Market
Rising Maternal Age and Demand for Chromosomal-Abnormality Screening
Increasing maternal age is an important driver of NIPT adoption in the United States because the risk of fetal chromosomal abnormalities increases with maternal age. ACOG recognizes pregnancy with anticipated delivery at 35 years or older as a risk factor for adverse maternal, fetal, and neonatal outcomes and recommends that prenatal genetic screening options, including cfDNA screening, be offered regardless of age or chromosomal-abnormality risk. U.S. birth statistics also demonstrate continued activity among older mothers. In 2024, the birth rate for women aged 35–39 was 54.3 births per 1,000 women, while the rate for women aged 40–44 increased 2% to 12.7 per 1,000 from 2023. This demographic trend supports demand for early and reliable prenatal screening. NIPT offers pregnant women a convenient blood-based alternative to invasive diagnostic procedures while providing highly sensitive screening for trisomies 21, 18, and 13. As awareness of age-related pregnancy risks increases, physicians are increasingly discussing genetic screening earlier during prenatal care. Consequently, the growing proportion of pregnancies among women in older age groups is expected to expand the U.S. NIPT customer base.
Strong Clinical Adoption and Favorable Professional Guidelines
The growing acceptance of cell-free DNA screening by medical professionals is accelerating the U.S. NIPT market. In January 2026, ACOG endorsed updated guidance recommending that cfDNA screening for common aneuploidies be routinely available to all obstetrical patients and identified cfDNA as the most sensitive and specific screening method for trisomies 21, 18, and 13. This represents a significant shift from approaches that historically focused genetic screening more heavily on higher-risk pregnancies. ACOG also emphasizes that prenatal genetic screening should be discussed and offered regardless of maternal age or risk. Such recommendations encourage obstetricians, maternal-fetal medicine specialists, and prenatal-care providers to incorporate NIPT into routine pregnancy counseling. The availability of testing across average-risk and high-risk populations increases the potential testing volume. In addition, NIPT requires only a maternal blood sample, making it more convenient and less invasive than diagnostic procedures. As clinical confidence, physician familiarity, and patient awareness continue to improve, broader guideline-supported access is expected to strengthen testing rates and market penetration throughout the United States.
Expanding Insurance Coverage and Accessibility
Expansion of payer coverage is another important growth factor for the United States NIPT market. Major private insurers increasingly cover NIPT for eligible pregnancies, although coverage criteria and prior-authorization requirements vary. ACOG’s payer overview shows that UnitedHealthcare covers all singleton pregnancies, while Anthem, Aetna, Cigna, and Centene have policies covering broad groups of singleton pregnancies; some plans also cover twin pregnancies. Broader insurance coverage reduces the financial burden on patients and encourages physicians to recommend testing. The size of the U.S. pregnancy population further supports demand, with 3,628,934 births recorded in 2024. Moreover, ACOG advocates for health insurance policies that do not create barriers to evidence-based prenatal testing. As insurers increasingly recognize NIPT as a clinically valuable screening option, reimbursement availability can improve patient access. Laboratories and testing companies can also benefit from partnerships with healthcare providers and payers, expanding distribution through hospitals, OB/GYN practices, maternal-fetal medicine centers, and specialized laboratories.
Challenges of the United States Non-Invasive Prenatal Testing Market
Insurance Restrictions and Prior-Authorization Barriers
Despite increasing insurance coverage, reimbursement complexity remains a significant challenge for the U.S. NIPT market. Coverage policies differ substantially among insurers, and some plans continue to impose eligibility criteria or prior-authorization requirements. ACOG reports that many health plans require physicians to obtain prior authorization for NIPT and may require documentation of counseling, maternal history, or other clinical information. For example, ACOG’s payer overview shows that UnitedHealthcare, TRICARE, BCBS Federal Employee Health Plan, Molina, and Humana have prior-authorization requirements under specified coverage policies. These administrative procedures can delay testing, increase workload for healthcare providers, and create uncertainty regarding patient out-of-pocket costs. Coverage can also differ according to pregnancy type, maternal age, clinical risk, and insurer policy. Such variation may discourage some patients from undergoing testing, particularly when they cannot determine their final financial responsibility before testing. Consequently, laboratories and NIPT providers must navigate complex reimbursement systems while working with physicians and insurers to demonstrate medical necessity and improve patient access.
Screening Limitations, False Results, and Counseling Requirements
Although NIPT is highly accurate for common fetal aneuploidies, it remains a screening test rather than a diagnostic test, creating an important market challenge. ACOG states that cfDNA is the most sensitive and specific screening test for common fetal aneuploidies but can produce false-positive and false-negative results and is not equivalent to diagnostic testing. Positive results may therefore require additional genetic counseling and confirmatory diagnostic procedures such as amniocentesis or chorionic villus sampling. Test performance can also be affected in certain circumstances, including multiple gestations, vanishing twin pregnancies, fetal demise, or abnormal findings. ACOG notes that screening performance in twin pregnancies is less established for some abnormalities. These limitations require healthcare professionals to provide appropriate pre- and post-test counseling so patients understand residual risk and the difference between screening and diagnosis. Misinterpretation of results can create anxiety and increase demand for follow-up procedures. Therefore, maintaining clinical confidence, educating patients, ensuring appropriate counseling, and clearly communicating test limitations remain essential for sustainable NIPT adoption in the United States.
Non-Invasive Prenatal Testing Launches & Major Product Developments in the USA
- January 2024 – Identifai-Genetics: U.S. Clinical Trial for Non-Invasive Fetal Whole-Genome Sequencing: Identifai-Genetics launched its first U.S. clinical trial with Columbia University and Columbia University Irving Medical Center to evaluate AI-based, non-invasive fetal DNA sequencing from maternal blood.
- March 2024 – Igentify: Digital NIPT Offering: Igentify launched NIPT through its Digital Genetic Assistant platform, providing digital patient intake, ACOG-compliant consent, educational videos, clinician tools, and personalized result communication.
- May 2024 – Natera: Fetal RhD NIPT: Natera launched a cfDNA-based fetal RhD test that can determine fetal RhD status from maternal blood as early as nine weeks. Validation involving more than 650 RhD-negative pregnancies demonstrated 100% sensitivity and greater than 99% specificity.
- May 2025 – BillionToOne: Expanded UNITY Fetal Risk Screen: BillionToOne expanded its UNITY Fetal Risk Screen to assess up to 14 recessive and X-linked conditions, in addition to aneuploidies, from a single maternal blood sample starting at nine weeks.
- August 2025 – Natera: Fetal Focus: Natera launched Fetal Focus, a single-gene NIPT designed to screen the fetus for inherited conditions when the pregnant patient is a carrier and the biological father is unavailable for testing.
- October 2025 – Natera: 20-Gene Fetal Focus Expansion: Natera announced an expansion of Fetal Focus from five to 20 genes, with the expanded panel planned for launch in Q4 2025.
- January 2026 – Natera: 21-Gene Fetal Focus: Natera launched an expanded 21-gene single-gene NIPT. Clinical validation across 294 samples showed overall 96% sensitivity and 98% population-weighted specificity.
- February 2026 – BillionToOne: Expanded Fetal Antigen NIPT Portfolio: BillionToOne announced expanded RBC Fetal Antigen NIPT and a first-of-its-kind Platelet Fetal Antigen NIPT in the U.S., targeting pregnancies at risk of hemolytic disease of the fetus and newborn and fetal/neonatal alloimmune thrombocytopenia.
- May 2026 – BillionToOne: UNITY Confirm: BillionToOne launched UNITY Confirm, a non-invasive confirmation test using circulating fetal cells to help confirm high-risk prenatal screening results from a maternal blood sample. It became available to clinicians using UNITY Aneuploidy Screen from May 28, 2026.
- May 2026 – Natera: Enhanced Panorama NIPT: Natera announced an enhanced Panorama NIPT using SNP-informed deep sequencing technology. The updated test demonstrated a 0.5% no-call rate, improving the ability to generate results for pregnancies with low fetal fractions.
Increasing Adoption of Advanced Sequencing Platforms in the United States
United States non-invasive prenatal testing (NIPT) instruments market is expanding as diagnostic laboratories, hospitals, and genetic-testing providers invest in high-throughput sequencing and molecular diagnostic infrastructure. NIPT instruments include next-generation sequencing (NGS) platforms, PCR systems, automated sample-preparation equipment, and associated laboratory technologies used to isolate, amplify, and analyze cell-free DNA. NGS remains particularly important because it enables high-volume analysis and supports screening for multiple chromosomal abnormalities from a single maternal blood sample. Globally, NGS accounted for approximately 75% of the NIPT market in 2024, reflecting its strong sensitivity, scalability, and ability to support multi-condition screening. Rising testing volumes are encouraging laboratories to upgrade instruments to improve throughput, automation, accuracy, and turnaround times. With 3.63 million births recorded in the U.S. in 2024, the underlying pregnancy population provides substantial demand for NIPT testing infrastructure.
Growing Demand for Early Trisomy 18 Screening
United States non-invasive prenatal Edwards syndrome (Trisomy 18) testing market is benefiting from broader adoption of cell-free DNA screening during pregnancy. Edwards syndrome is a serious chromosomal abnormality associated with substantial developmental and medical complications, making early risk assessment an important component of prenatal care. NIPT evaluates fetal chromosomal risk by analyzing cell-free DNA obtained through a maternal blood sample, providing a safer screening approach than invasive procedures. The expanding U.S. prenatal testing population provides a significant market foundation. The CDC reported 3,628,934 births in the United States in 2024, while the birth rate among women aged 35–39 was 54.3 per 1,000, and the rate among women aged 40–44 increased 2% to 12.7 per 1,000. These demographic trends are relevant because advanced maternal age is associated with increased risk of fetal chromosomal abnormalities and greater demand for genetic screening. Increasing physician recommendations, patient awareness, improved sequencing technologies, and the integration of NIPT into prenatal-care pathways are therefore expected to sustain demand for Trisomy 18 screening.
Hospitals Expand Prenatal Genetic Screening Capabilities
The hospital segment represents an important end-user market for non-invasive prenatal testing in the United States, supported by the extensive healthcare infrastructure available for obstetric, maternal-fetal medicine, laboratory, and genetic-counseling services. Hospitals can perform NIPT directly through in-house molecular laboratories or collaborate with specialized commercial laboratories for sample processing and genomic analysis. The growing integration of genetic screening into prenatal care is encouraging hospitals to strengthen their testing capabilities and referral networks. The American Hospital Association reported approximately 6,100 hospitals in the United States, including 5,121 community hospitals, based on its 2024 Annual Survey. These hospitals collectively had more than 907,000 staffed beds and recorded approximately 35.7 million admissions. This extensive healthcare network provides a substantial distribution and referral infrastructure for prenatal screening services. Hospitals are increasingly using NIPT alongside ultrasound, genetic counseling, and maternal-fetal medicine services to support early assessment of fetal chromosomal abnormalities. Growing emphasis on personalized medicine, preventive care, and earlier risk identification is expected to further increase hospital-based NIPT utilization.
California Strong Public Prenatal Screening Infrastructure
California is one of the most important state markets for non-invasive prenatal testing (NIPT) in the United States, supported by extensive prenatal screening infrastructure, advanced healthcare facilities, and strong adoption of genetic-testing technologies. The state’s California Prenatal Screening (PNS) Program provides screening services to pregnant individuals statewide and integrates cell-free DNA screening into its prenatal screening pathway. More than 340,000 pregnant individuals participate in California’s prenatal screening program each year, creating a substantial testing pool and supporting demand for NIPT. The state also recorded approximately 413,000 births in 2024, reinforcing the size of its prenatal-care market. Rising maternal age, increasing awareness of chromosomal abnormalities, and greater availability of maternal-fetal medicine and genetic-counseling services are supporting adoption. California’s emphasis on early fetal risk assessment and expanded access to prenatal screening is expected to encourage continued utilization of NIPT across hospitals, physician offices, and specialized diagnostic laboratories.
Large Birth Population and Expanding Healthcare Demand in Texas
Texas represents a major growth market for non-invasive prenatal testing, supported by its large population, high number of pregnancies, expanding healthcare infrastructure, and growing awareness of genetic screening. The state recorded approximately 387,000 newborns screened through its newborn screening program in 2025, demonstrating the substantial scale of maternal and neonatal healthcare services in Texas. Texas also recorded approximately 385,000 births in 2024, creating a large potential patient base for prenatal genetic screening. Increasing adoption of advanced molecular diagnostics, growing physician awareness, and wider availability of NIPT through hospitals and commercial laboratories are contributing to market expansion. Texas has also developed a strong biotechnology and healthcare ecosystem, particularly in major metropolitan areas such as Houston, Dallas–Fort Worth, Austin, and San Antonio. The increasing number of pregnancies among older mothers is another relevant demand factor because maternal age is associated with a higher risk of chromosomal abnormalities. As healthcare providers increasingly emphasize early risk assessment and personalized prenatal care, NIPT is becoming an important screening option. Continued investment in maternal healthcare infrastructure and genetic-testing services is expected to strengthen the Texas NIPT market over the forecast period.
Florida Prenatal Risk Screening Supports NIPT Adoption
Florida’s non-invasive prenatal testing market is benefiting from the state’s large pregnancy population, expanding maternal healthcare services, and increasing awareness of prenatal genetic screening. Florida recorded approximately 225,000 births in 2024, creating a substantial population requiring prenatal healthcare and screening services. Healthcare providers increasingly use NIPT to evaluate the risk of common fetal chromosomal abnormalities, including trisomy 21, trisomy 18, and trisomy 13. Florida’s regulatory framework also supports early identification of pregnancy-related risks. Under Florida law, prenatal care providers are required to conduct prenatal risk screening during the first prenatal visit to identify high-risk conditions and facilitate appropriate intervention. This screening-oriented approach provides a favorable environment for the adoption of advanced prenatal diagnostic and screening technologies. In addition, Florida has a broad network of hospitals, obstetric practices, maternal-fetal medicine specialists, and diagnostic laboratories capable of offering or facilitating NIPT. Growing patient awareness, increasing demand for non-invasive testing, and improvements in cell-free DNA technologies are expected to support market expansion. The combination of a large birth population and an established prenatal-care framework positions Florida as an attractive regional market for NIPT providers.
Advanced Healthcare Infrastructure and High Demand for Genetic Screening in New York
New York is a significant market for non-invasive prenatal testing, supported by its extensive healthcare network, advanced academic medical centers, genetic-testing capabilities, and established maternal-fetal medicine services. According to CDC 2024 data, New York had a general fertility rate of 52.1 births per 1,000 females aged 15–44 years, indicating a substantial population requiring prenatal healthcare services. The state also recorded approximately 206,000 births in 2024. NIPT adoption is supported by increasing physician awareness and growing patient interest in early assessment of fetal chromosomal abnormalities. The availability of specialized hospitals and genetic-counseling services enables patients with higher-risk pregnancies or abnormal screening results to receive appropriate follow-up care. New York’s concentration of major medical institutions in New York City and other urban centers further supports access to advanced genomic testing. This national growth, combined with New York’s sophisticated healthcare infrastructure and emphasis on early prenatal risk assessment, is expected to support continued expansion of the state’s NIPT market.
United States Non-Invasive Prenatal Testing Market Segmentation
Component
- Instruments
- Kits and Reagents
- Services
Application
- Down Syndrome (Trisomy 21)
- Edwards Syndrome (Trisomy 18)
- Patau Syndrome (Trisomy 13)
- Turner Syndrome
- Other Applications
End User
- Hospitals
- Diagnostic Labs
States
- California
- Texas
- New York
- Florida
- Illinois
- Pennsylvania
- Ohio
- Georgia
- New Jersey
- Washington
- North Carolina
- Massachusetts
- Virginia
- Michigan
- Maryland
- Colorado
- Tennessee
- Indiana
- Arizona
- Minnesota
- Wisconsin
- Missouri
- Connecticut
- South Carolina
- Oregon
- Louisiana
- Alabama
- Kentucky
- Rest of United States
All the Key players have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Eurofins Scientific
- F. Hoffmann-La Roche Ltd
- Invitae Corporation
- Illumina Inc.
- Natera Inc.
- Centogene NV
- Qiagen
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Million |
| Segment Covered |
Component, Application, End User and States |
| States Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.