Non-Invasive Prenatal Testing Market Report by Component, Application, End User, Country and Company Analysis 2026-2034
Buy NowNon-Invasive Prenatal Testing Market Size and Forecast
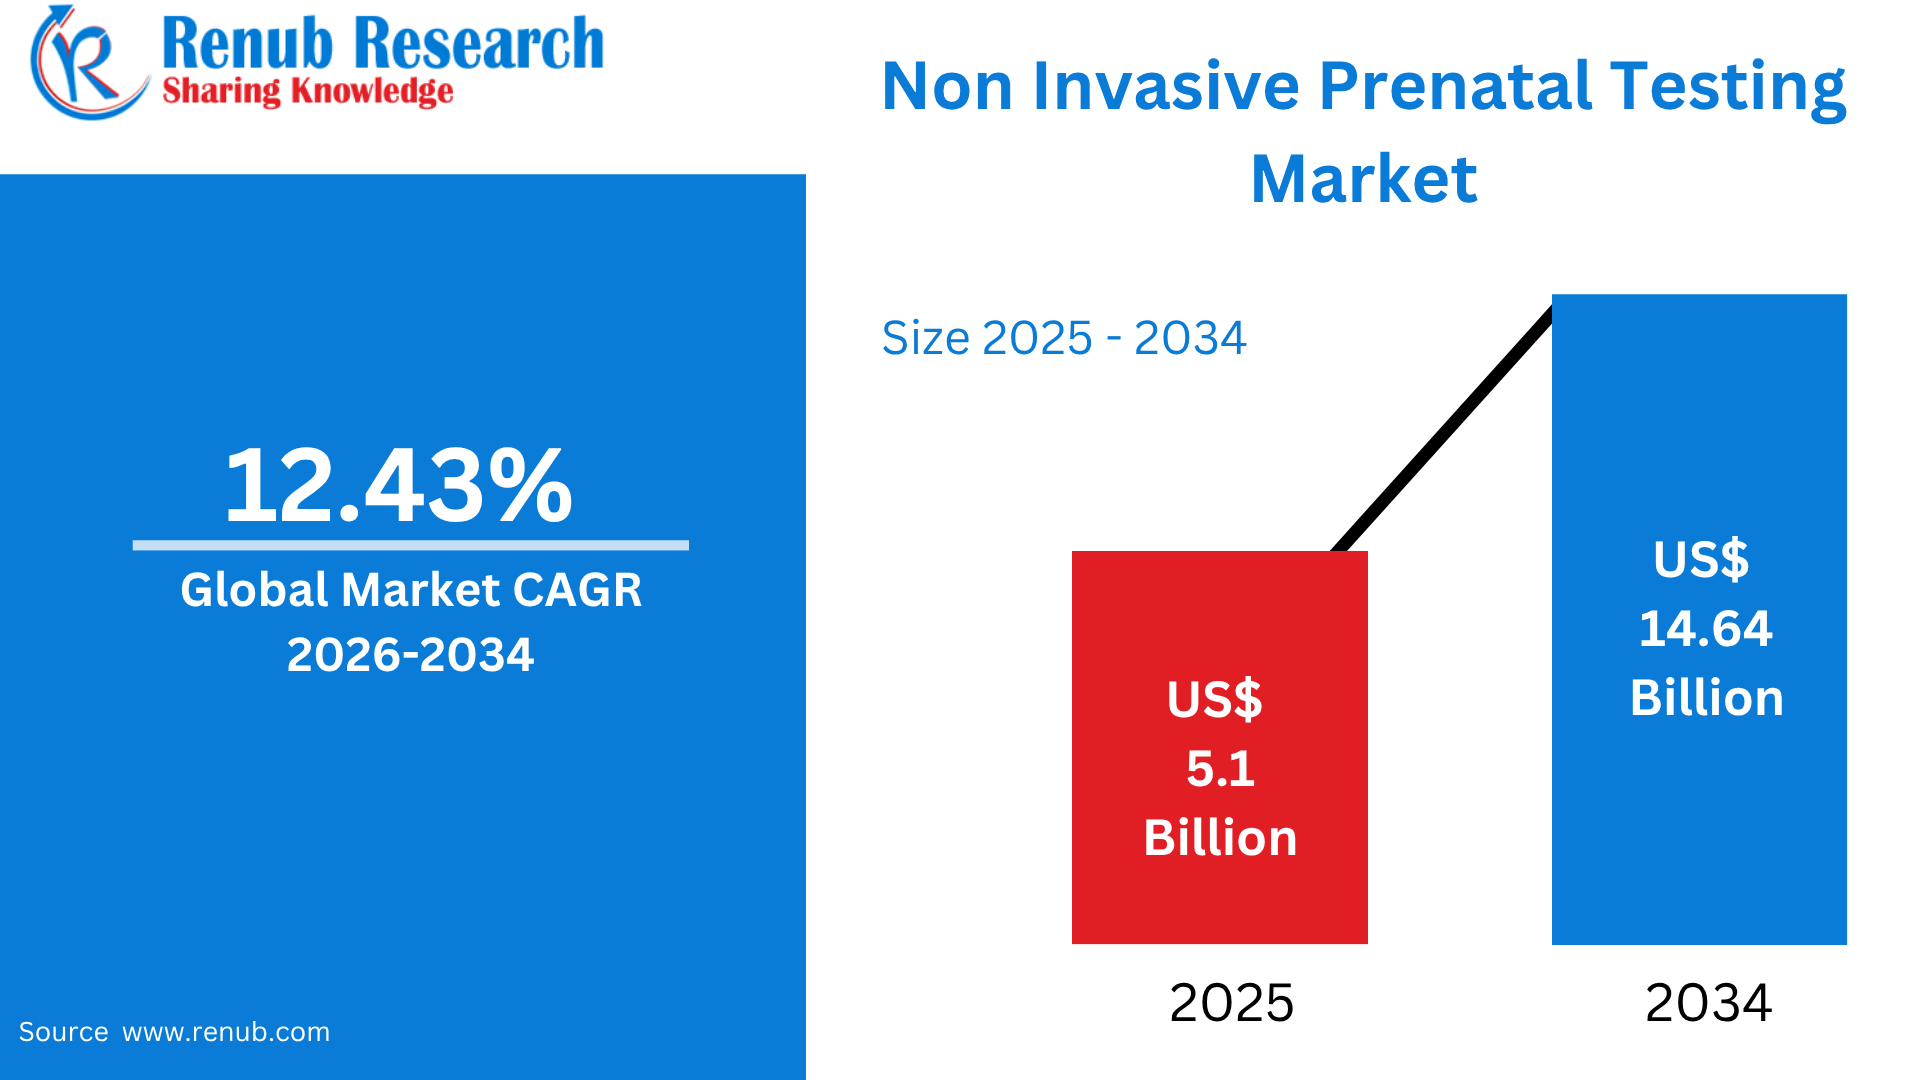
Non-Invasive Prenatal Testing Market is projected to grow from US$ 5.10 billion in 2025 to US$ 14.64 billion by 2034, registering a CAGR of 12.43% during 2026–2034. Market expansion is expected to be driven by the increasing age of mothers, rising awareness of early screening for chromosomal and genetic abnormalities, and continuous advancements in next-generation sequencing and cell-free DNA technologies. The growing adoption of non-invasive prenatal screening as a safer alternative to invasive diagnostic procedures, along with expanding access to prenatal genetic testing, is further supporting market growth.
What is Non-Invasive Prenatal Testing (NIPT) and Its Uses & Popularity Worldwide
Non-Invasive Prenatal Testing (NIPT), also known as cell-free DNA (cfDNA) screening, is a prenatal screening method that analyzes small fragments of placental DNA circulating in a pregnant woman’s blood. It is generally available from around 9–10 weeks of pregnancy and is primarily used to assess the risk of common chromosomal abnormalities, particularly trisomy 21 (Down syndrome), trisomy 18 (Edwards syndrome), and trisomy 13 (Patau syndrome). NIPT can also provide screening for certain sex-chromosome abnormalities, depending on the test. The technology has become increasingly popular because it requires only a maternal blood sample and avoids the procedure-related risks associated with invasive diagnostic procedures such as amniocentesis and chorionic villus sampling. In 2026, the American College of Obstetricians and Gynecologists recommended that cfDNA screening for common aneuploidies be routinely available to all obstetrical patients and described it as the most sensitive and specific screening approach for these abnormalities. For trisomy 21, current guidance reports approximately 99.2% sensitivity and 99.91% specificity, supporting its growing adoption worldwide. However, NIPT remains a screening rather than diagnostic test.
Key facts
- An estimated 240 000 newborns die worldwide within 28 days of birth every year due to congenital disorders. Congenital disorders cause a further 170 000 deaths of children between the ages of 1 month and 5 years.
- Congenital disorders can contribute to long-term disability, which takes a significant toll on individuals, families, health care systems and societies.
- Nine of ten children born with a serious congenital disorder are in low- and middle-income countries.
- As neonatal and under-5 mortality rates decline, congenital disorders become a larger proportion of the cause of neonatal and under-5 deaths.
- The most common severe congenital disorders are heart defects, neural tube defects and Down syndrome.
- Although congenital disorders may be the result of one or more genetic, infectious, nutritional or environmental factors, it is often difficult to identify the exact causes.
- Some congenital disorders can be prevented. Vaccination, adequate intake of folic acid or iodine through fortification of staple foods or supplementation, and adequate care before and during a pregnancy are examples of prevention methods.
Growth Drivers of the NIPT Market
Increasing Maternal Age and Risk of Chromosomal Abnormalities
The increasing age at pregnancy is an important factor supporting demand for Non-Invasive Prenatal Testing because the risk of fetal chromosomal abnormalities rises with maternal age. Advanced maternal age is associated particularly with a higher probability of trisomies, encouraging expectant parents and healthcare providers to consider prenatal screening earlier in pregnancy. According to the American College of Obstetricians and Gynecologists, chromosomal abnormalities occur in approximately 1 in 150 live births, while their incidence increases as maternal age rises. NIPT provides an early blood-based screening option that can be performed from approximately 9–10 weeks of gestation, allowing risk assessment before many traditional second-trimester procedures. The positive predictive value of cfDNA screening for trisomy 21 also increases with maternal age; updated clinical guidance reports approximately 79% PPV at age 35 and 93% at age 40, compared with 48% at age 20. Growing maternal-age pregnancies, greater awareness of age-related genetic risks, and demand for earlier prenatal information are therefore supporting the worldwide expansion of NIPT services.
High Accuracy and Preference for Non-Invasive Screening
The strong analytical and clinical performance of cell-free DNA screening is accelerating the adoption of NIPT as an important component of prenatal care. Unlike amniocentesis and chorionic villus sampling, NIPT uses a maternal blood sample and does not require fetal or placental tissue collection. Current clinical guidance identifies cfDNA as the most sensitive and specific screening test for common fetal aneuploidies, including trisomies 21, 18, and 13. Updated performance data indicate sensitivity of approximately 99.2% for trisomy 21, 96.3% for trisomy 18, and 91% for trisomy 13, with specificity exceeding 99.8% for these three conditions. The combination of early testing, high screening performance, and a non-invasive sampling procedure has increased acceptance among pregnant women and healthcare professionals. NIPT can generally be performed from 9–10 weeks, while results are often available within approximately one week. Growing preference for safer and more convenient prenatal screening is therefore contributing significantly to market expansion across developed and emerging healthcare systems.
Advancements in Cell-Free DNA and Sequencing Technologies
Technological advancements in cell-free DNA analysis, next-generation sequencing, and bioinformatics are creating new opportunities for the NIPT market. Modern testing platforms can analyze fragments of placental DNA circulating in maternal blood and identify chromosome-level abnormalities with high sensitivity. NIPT for common aneuploidies became clinically available in 2011, and adoption has increased substantially since its introduction. Advances in sequencing platforms, laboratory automation, bioinformatics algorithms, and sample processing are improving testing efficiency and expanding the range of prenatal genomic information that can be evaluated. Current cfDNA methodologies include massively parallel sequencing and single-nucleotide polymorphism-based approaches, with different platforms offering specific analytical capabilities. NIPT is also being investigated or marketed for additional applications, including sex-chromosome abnormalities, microdeletions, rare autosomal trisomies, and selected single-gene disorders. However, clinical evidence and professional recommendations differ across these applications. Continued innovation in genomic technologies, declining sequencing costs, improved laboratory capacity, and broader availability of prenatal genetic services are expected to support long-term market growth.
Challenges of the NIPT Market
NIPT Is a Screening Test Rather Than a Diagnostic Test
A major challenge for the NIPT market is the possibility of misunderstanding screening results as definitive diagnoses. Although cfDNA testing provides high sensitivity and specificity for common aneuploidies, it does not establish with certainty that a fetus has a chromosomal abnormality. A positive NIPT result therefore generally requires follow-up genetic counseling and diagnostic testing through procedures such as chorionic villus sampling or amniocentesis. Current guidance emphasizes that cfDNA is not equivalent to diagnostic testing and that false-positive and false-negative results can occur. The positive predictive value also varies according to the underlying prevalence and maternal age. For trisomy 21, for example, updated data show PPVs ranging from approximately 48% at age 20 to 93% at age 40. These differences can complicate interpretation and counseling, particularly for low-risk populations and less common abnormalities. The need for confirmatory testing can increase patient anxiety, healthcare utilization, and overall testing costs. Ensuring appropriate pretest counseling and clear communication of NIPT limitations remains essential for responsible market expansion.
Cost, Access, and Limited Standardization Across Markets
Cost and unequal access to advanced genetic testing remain important barriers to the wider adoption of NIPT, particularly in countries where prenatal genetic services and reimbursement coverage are limited. NIPT requires specialized laboratory infrastructure, sequencing or genomic analysis platforms, trained personnel, and bioinformatics capabilities, which can increase testing costs compared with conventional screening approaches. Access can also vary considerably between public and private healthcare systems and between urban and rural areas. In addition, differences in laboratory platforms, reporting procedures, test panels, and clinical interpretation can create challenges for standardization. Updated professional guidance notes that laboratories use different cfDNA technologies and that proprietary bioinformatics algorithms and reporting practices vary. The expansion of testing beyond common trisomies also raises questions regarding clinical validity and utility. For example, current guidance does not recommend routine general-population screening for microdeletion conditions, reflecting limitations in available evidence. Addressing affordability, laboratory capacity, reimbursement, quality standards, and consistent clinical counseling will be important for broader global NIPT adoption.
Advancements in Sequencing and Laboratory Automation
Non-Invasive Prenatal Testing (NIPT) Instruments Market is expanding as laboratories and healthcare providers increasingly require advanced platforms for analyzing cell-free fetal DNA. Key instruments include next-generation sequencing (NGS) systems, PCR platforms, microarray analyzers, automated nucleic-acid extraction systems, and high-throughput sample-processing equipment. These technologies support the detection of common chromosomal abnormalities, particularly trisomy 21, trisomy 18, and trisomy 13. NIPT can generally be performed from around the 10th week of pregnancy, creating demand for instruments capable of processing samples rapidly and accurately. Modern NGS platforms allow laboratories to analyze large numbers of samples while advanced automation reduces manual handling and processing time. Increasing laboratory adoption of automated workflows, improved sequencing accuracy, and bioinformatics integration is further strengthening demand. The growing use of molecular diagnostics and expanding prenatal screening programs are encouraging investments in sophisticated laboratory infrastructure. In addition, developments in AI-assisted genomic analysis and cloud-based data processing are helping laboratories improve interpretation and workflow efficiency, creating further opportunities for NIPT instrument manufacturers.
Outsourcing and Expanding Access to Prenatal Genetic Screening
Non-Invasive Prenatal Testing Services Market is growing as hospitals, obstetricians, diagnostic laboratories, and expectant parents increasingly use specialized genetic-testing providers. NIPT services generally include sample collection, laboratory processing, sequencing, bioinformatic analysis, result interpretation, and genetic counseling. Outsourcing is particularly attractive to healthcare facilities because establishing an in-house NIPT laboratory requires expensive sequencing systems, specialized personnel, quality-control procedures, and bioinformatics infrastructure. NIPT typically requires only a maternal blood sample and can be performed from approximately 10 weeks of pregnancy, supporting its use as an early prenatal screening option. The technology is primarily used to assess the risk of trisomies 21, 18, and 13, while some providers offer additional screening panels. Increasing maternal age, growing awareness of chromosomal abnormalities, and demand for non-invasive testing are expanding the patient base. Improvements in telemedicine and digital healthcare platforms are also enabling patients and physicians to access test ordering, counseling, and results remotely, supporting broader adoption of NIPT services across developed and emerging markets.
Rising Demand for Early Trisomy 18 Screening
Edwards Syndrome Non-Invasive Prenatal Testing Market is supported by increasing awareness of trisomy 18, also known as Edwards syndrome, and the importance of early prenatal risk assessment. Trisomy 18 occurs when a fetus has an additional copy of chromosome 18 and is associated with severe developmental and structural abnormalities. The condition is relatively uncommon, with estimates indicating approximately 1 case per 2,000–6,000 live births in the United States, although prevalence varies depending on whether pregnancy losses and stillbirths are included. NIPT provides a maternal blood-based screening approach that analyzes cell-free DNA and can assess the risk of trisomy 18 without requiring an invasive procedure. The test is generally available from around 10 weeks of pregnancy, enabling earlier risk assessment. Increasing awareness among pregnant women, particularly those with advanced maternal age or abnormal ultrasound findings, is contributing to demand. However, NIPT remains a screening test, and a positive result requires diagnostic confirmation through procedures such as amniocentesis or chorionic-villus sampling.
High-Throughput Genetic Testing Supports Laboratory Expansion
Non-Invasive Prenatal Testing Diagnostic Labs Market is expanding because specialized laboratories play a central role in processing and interpreting prenatal cell-free DNA tests. These laboratories use next-generation sequencing, molecular diagnostic technologies, automated sample preparation, bioinformatics, and quality-control systems to identify chromosomal abnormalities such as trisomy 21, trisomy 18, and trisomy 13. Centralized laboratories can process large numbers of samples, allowing healthcare providers to outsource testing rather than establish expensive in-house genomic facilities. This model can reduce infrastructure requirements while providing access to specialized personnel and advanced sequencing platforms. The ability to process high sample volumes is particularly important as NIPT adoption expands across obstetric clinics and hospitals. Laboratory automation is also helping reduce manual processing, improve consistency, and shorten turnaround times. In Germany, for example, NIPT for trisomies 13, 18, and 21 can be covered by statutory health insurance in defined clinical circumstances, increasing the role of qualified laboratories in prenatal screening. Continued investments in genomic infrastructure, quality assurance, and molecular testing capabilities are expected to support diagnostic-laboratory market growth.
United States Advanced Genomic Infrastructure and Growing Prenatal Screening Demand
The United States NIPT Market is supported by advanced genomic infrastructure, high adoption of molecular diagnostics, and increasing demand for early screening of fetal chromosomal abnormalities. NIPT uses maternal blood to analyze cell-free DNA and primarily screens for trisomy 21, trisomy 18, and trisomy 13. Trisomy 18 is estimated to occur in approximately 1 in 2,000–6,000 live births in the United States, while Down syndrome occurs at roughly 1 in 700 births, according to commonly cited U.S. estimates. The increasing number of pregnancies among women of advanced maternal age is also supporting demand because the probability of chromosomal abnormalities increases with maternal age. Technological advances in next-generation sequencing and bioinformatics have improved the performance and scalability of NIPT. The United States also benefits from a large network of specialized genetic laboratories, obstetric providers, and genomic-testing companies. Growing physician and patient awareness of non-invasive screening, combined with expanding availability through hospitals, diagnostic laboratories, and specialized testing providers, is expected to sustain market development.
Germany Non-Invasive Prenatal Testing Market
Regulated Adoption and Integration into Prenatal Care
Germany’s NIPT Market is developing as expectant parents and healthcare providers increasingly recognize the role of cell-free DNA screening in assessing common fetal chromosomal abnormalities. NIPT is primarily used to determine the probability of trisomy 21, trisomy 18, and trisomy 13 and is generally performed using a maternal blood sample from around the 10th week of pregnancy. Germany introduced statutory health-insurance coverage for NIPT in defined circumstances beginning in July 2022, following extensive evaluation by the Federal Joint Committee. The test is not considered a routine screening procedure and requires appropriate medical counseling and individual consideration. Germany’s advanced healthcare infrastructure, strong laboratory capabilities, and established genetic-testing sector provide a supportive environment for NIPT adoption. At the same time, regulatory requirements, counseling obligations, ethical considerations, and differences in reimbursement policies can influence market expansion. Increasing awareness of prenatal genetic screening and continuing improvements in sequencing technologies are expected to encourage demand for NIPT services and related laboratory technologies. Specialized diagnostic laboratories and genetic-testing companies are therefore gaining importance within the country’s prenatal-care ecosystem.
China Non-Invasive Prenatal Testing Market
Large Pregnancy Population and Expansion of Genomic Healthcare
China’s Non-Invasive Prenatal Testing Market is experiencing strong development due to increasing awareness of prenatal healthcare, expanding genomic-testing capabilities, and demand for safer screening methods. NIPT is increasingly used to assess the risk of chromosomal abnormalities including Down syndrome, trisomy 18, and trisomy 13 without requiring invasive fetal sampling. The country’s large population and substantial number of pregnancies create a significant potential testing base, while delayed childbearing and increasing maternal age in some population groups are contributing to greater demand for prenatal genetic screening. China has also developed a strong domestic genomic-testing industry, with companies investing in sequencing platforms, bioinformatics, laboratory networks, and prenatal-testing services. BGI Genomics has reported collaborations with more than 160 hospitals in China and overseas for its NIPT-related services, illustrating the expanding institutional reach of prenatal genomic testing. Government investments in healthcare modernization and precision medicine are further supporting technological adoption. However, testing affordability, differences in healthcare access between regions, and the need for specialized laboratory infrastructure remain important considerations for broader NIPT penetration across the country.
Saudi Arabia Non-Invasive Prenatal Testing Market
Healthcare Transformation and Growing Demand for Genetic Screening
Saudi Arabia’s Non-Invasive Prenatal Testing Market is supported by healthcare modernization, increasing investment in advanced diagnostics, and growing emphasis on maternal and child health. NIPT provides a blood-based screening method for assessing the risk of fetal chromosomal abnormalities, including trisomy 21, trisomy 18, and trisomy 13, and is particularly relevant for pregnancies requiring additional genetic-risk assessment. The Kingdom’s healthcare system includes Ministry of Health, private, and other government healthcare providers, creating multiple channels for adoption of specialized diagnostic technologies. Saudi Arabia’s Health Sector Transformation Program under Vision 2030 is supporting improvements in healthcare quality, digitalization, prevention, and investment. Advanced hospitals and tertiary referral centers are increasingly incorporating genomic medicine and specialized laboratory testing into clinical services. In July 2025, King Faisal Specialist Hospital & Research Centre announced a partnership with Rady Children’s Institute for Genomic Medicine to implement genome-based newborn screening capable of identifying more than 500 treatable genetic disorders, demonstrating growing interest in genomic healthcare. Increasing awareness of preventive medicine, personalized healthcare, and prenatal genetic screening is expected to create further opportunities for NIPT providers, although testing costs and availability of specialized genomic services remain important market considerations.
Non-Invasive Prenatal Testing Market Segments
Component
- Instruments
- Kits and Reagents
- Services
Application
- Down Syndrome (trisomy 21)
- Edwards Syndrome (trisomy 18)
- Patau Syndrome (trisomy 13)
- Turner Syndrome
- Other Applications
End User
- Hospitals
- Diagnostic Labs
Country
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Malaysia
- Indonesia
- Australia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- Saudi Arabia
- UAE
- South Africa
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Company Analysis:
- Eurofins Scientific
- F. Hoffmann-La Roche Ltd
- Invitae Corporation
- Illumina Inc.
- Natera Inc.
- Centogene NV
- Qiagen
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Component, Application, End User and Country |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.