Europe Distributed Control Systems Market Report by Component, End User, Countries and Companies Analysis 2026-2034
Buy NowEurope Distributed Control Systems Market Size and Forecast
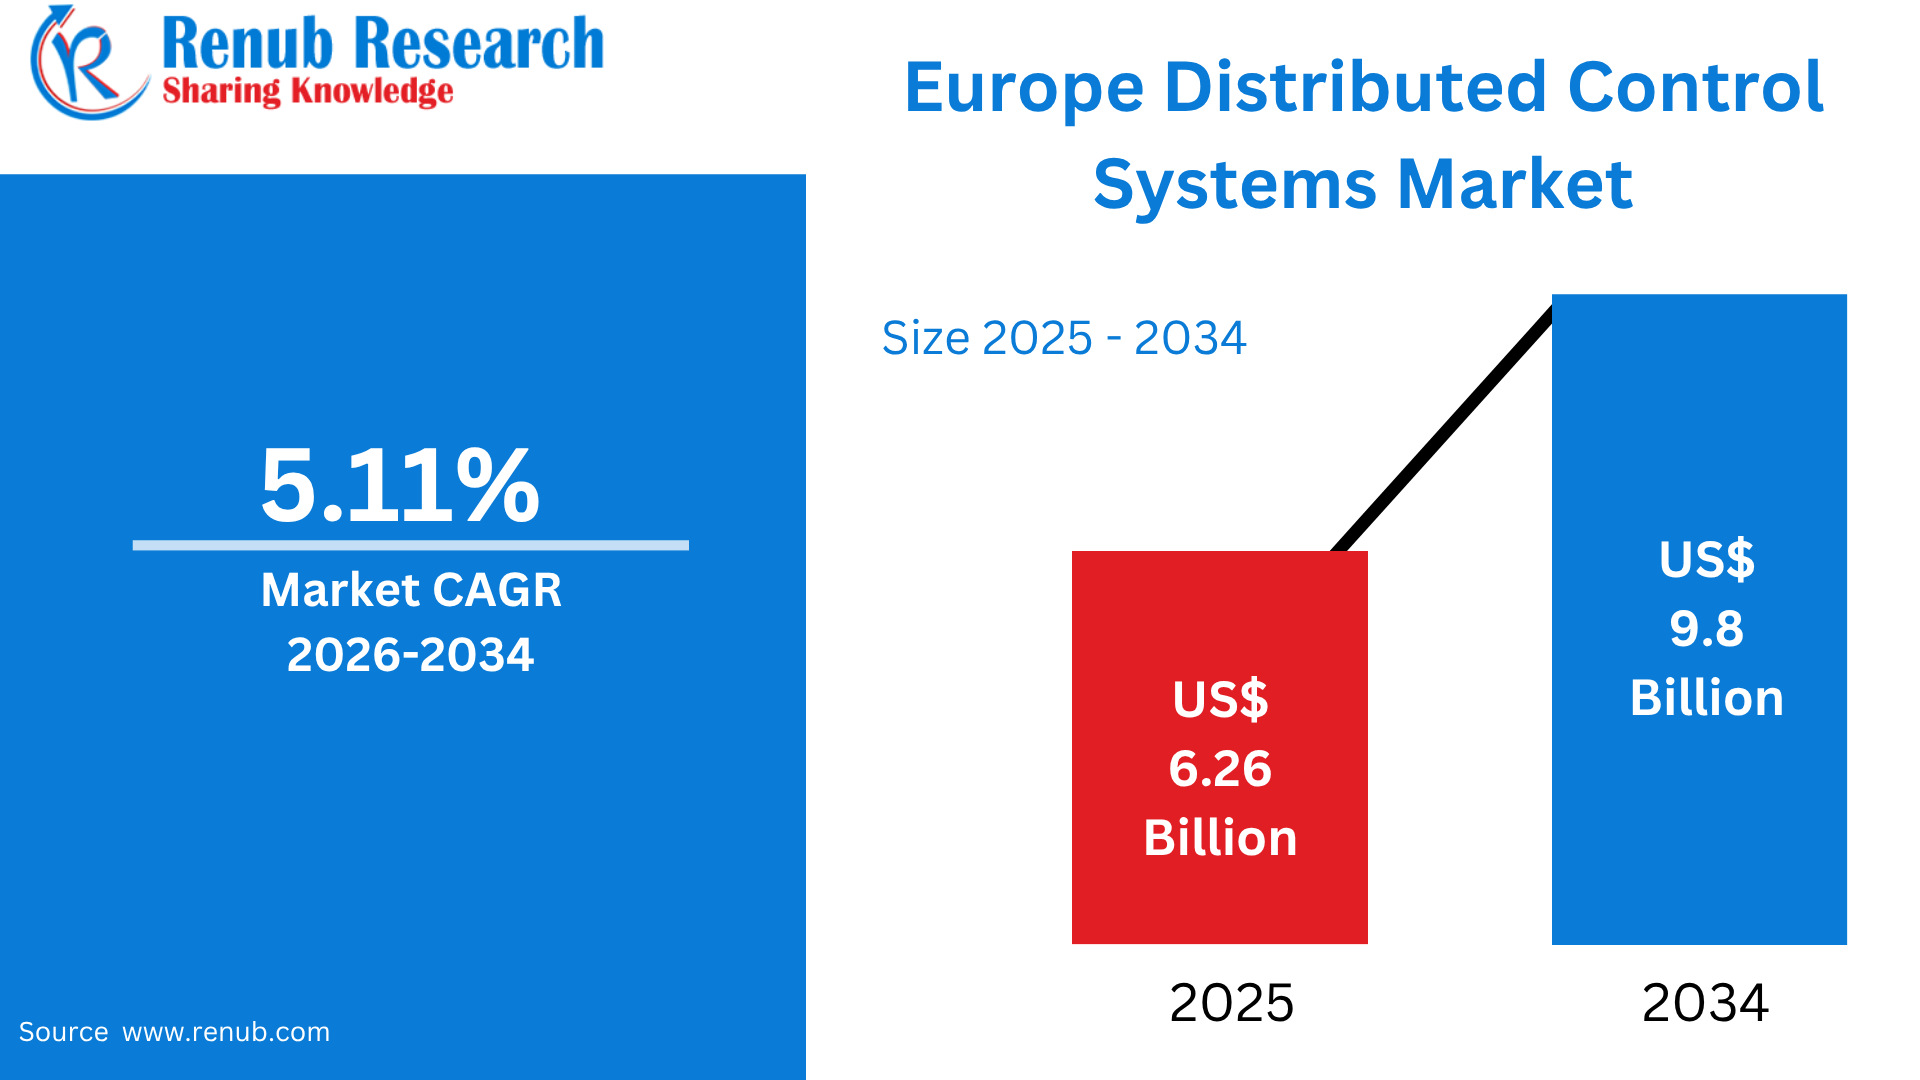
Europe Distributed Control Systems Market is projected to reach US$ 9.8 billion by 2034, increasing from US$ 6.26 billion in 2025 and registering a CAGR of 5.11% during 2026–2034. The European DCS market is anticipated to witness consistent expansion as industries accelerate automation, modernize aging control infrastructure, and adopt digital transformation strategies. Growing investments in Industry 4.0, renewable energy integration, smart industrial facilities, and real-time process monitoring are further supporting demand for advanced DCS solutions.
What are Distributed Control Systems and Their Uses & Popularity in Europe
A Distributed Control System (DCS) is an automated control architecture used to monitor, regulate, and optimize industrial processes through multiple interconnected controllers rather than relying on a single centralized controller. DCS solutions integrate sensors, controllers, human-machine interfaces (HMIs), communication networks, and software to provide real-time monitoring and control of complex operations. They are widely used in oil and gas, chemicals, power generation, pharmaceuticals, food and beverages, metals, mining, and manufacturing.
In Europe, DCS adoption is gaining importance as industries modernize production facilities, improve energy efficiency, and transition toward smart manufacturing. The European industrial sector provides around 36 million jobs, while manufacturing accounts for approximately 16% of EU value added, highlighting the region’s substantial industrial base. Moreover, digitalization is becoming increasingly widespread: 20% of EU enterprises used AI technologies in 2025, up from 13.5% in 2024. DCS platforms complement this transformation by enabling real-time data analysis, predictive maintenance, process optimization, improved safety, and greater operational reliability, supporting their growing popularity across Europe’s process industries.
Enterprises using AI technologies, 2024 and 2025 (% of enterprises)
- Overall EU Adoption: The share of EU enterprises using AI technologies rose from roughly 13.5% in 2024 to 20% in 2025.
- Top Adopters (2025):
- Denmark: Ranked highest in the EU at ~42% (up from ~28% in 2024).
- Finland: Second at ~38% (up from ~24%).
- Sweden: ~35% (up from ~25%).
- Belgium: ~34% (up from ~25%).
- Luxembourg: ~33% (up from ~24%).
- Netherlands: ~30% (up from ~23%; note indicates a break in time series).
- Notable Increases:
- Lithuania: More than doubled its share from ~9% in 2024 to ~21% in 2025.
- Spain: Nearly doubled from ~11% to ~20%.
- Italy: Doubled from ~8% to ~16%.
- France: Grew significantly from ~10% to ~18%.
- Lowest Adoption (2025):
- Romania: Lowest in the EU at ~5% (up from ~3% in 2024).
- Poland & Bulgaria: Tied near the bottom at ~8%.
- Greece & Cyprus: Below 10%, with Greece showing a slight dip (down to ~9% from ~10% in 2024).
- Non-EU Comparison:
·Norway: Increased from ~21% in 2024 to ~29% in 2025
Eurostat (the statistical office of the European Union)
Growth Drivers in the Europe Distributed Control Systems Market
Accelerating Industrial Automation and Digital Transformation
The increasing adoption of industrial automation, Industry 4.0, IoT, AI, and advanced analytics is one of the strongest drivers of the European DCS market. European manufacturers are increasingly upgrading traditional production environments with connected systems capable of real-time monitoring, automated decision-making, and predictive maintenance. According to the European Commission, 20% of EU enterprises with 10 or more employees used AI in 2025, compared with 13.5% in 2024. The Commission also reports that 33.2% of EU companies used data analytics and 38.9% used cloud technologies, demonstrating the broader movement toward digitally enabled operations. DCS platforms benefit directly from this transition because they connect field instruments, controllers, industrial networks, and enterprise-level analytics. European industries are therefore deploying DCS to improve production consistency, reduce manual intervention, monitor equipment performance, and optimize resource utilization. Furthermore, EU industrial ecosystems reported an average 8% productivity increase from advanced digital technologies, with robotics identified as having the greatest impact in manufacturing by 84% of respondents. This digitalization trend is expected to encourage further DCS investments across Europe.
Rising Demand for Energy Efficiency and Process Optimization
Growing energy costs, decarbonization targets, and pressure to improve industrial productivity are encouraging European companies to deploy advanced process-control technologies. DCS solutions allow operators to continuously monitor parameters such as temperature, pressure, flow, energy consumption, and production output, enabling faster adjustments and more efficient resource utilization. This is particularly important for energy-intensive industries such as chemicals, steel, cement, paper, plastics, refining, and glass.
The European Commission identifies energy-intensive industries as a major part of Europe’s industrial ecosystem, comprising almost 8 million employees and approximately €550 billion in value added based on reported ecosystem data. The EU also estimates that industry needs substantial reductions in emissions to remain aligned with climate-neutrality objectives, making digital process optimization increasingly important. In 2026, the European Commission further highlighted that AI-based operation and maintenance optimization in the energy sector could generate savings of up to €94 billion annually by 2035. These developments strengthen the business case for DCS platforms that provide real-time control, energy monitoring, process optimization, and predictive maintenance.
Expansion of Smart Energy Infrastructure and Renewable Integration
The transformation of Europe’s energy system is creating additional opportunities for distributed control technologies. Increasing penetration of wind, solar, decentralized generation, energy storage, and smart-grid infrastructure requires sophisticated monitoring and control capabilities. DCS platforms can help power-generation facilities and industrial energy users coordinate complex processes, monitor equipment, manage loads, and integrate data from multiple operational systems. According to the European Commission, EU electricity consumption is expected to increase by approximately 60% by 2030, while wind and solar generation capacity needs to increase from around 400 GW in 2022 to at least 1,000 GW by 2030. Such rapid expansion increases the need for intelligent, interconnected control infrastructure. The European Commission’s 2026 digital-energy roadmap also emphasizes real-time visibility, interoperability, AI, digital twins, and enhanced control of increasingly decentralized energy systems. Consequently, utilities and industrial energy users are increasingly evaluating advanced control architectures to improve system reliability, operational flexibility, and renewable-energy integration. This trend is expected to support DCS demand in power generation, utilities, oil and gas, and other process-intensive industries.
Market Challenges
High Initial Investment and Complex System Integration
One of the major challenges facing the European DCS market is the high upfront cost associated with system installation, modernization, engineering, and integration. DCS projects often require specialized controllers, sensors, communication infrastructure, software licenses, cybersecurity systems, engineering services, and operator training. For facilities operating legacy equipment, integrating a modern DCS with existing PLCs, SCADA systems, field instruments, and enterprise platforms can further increase project complexity and costs. This challenge is particularly relevant to Europe’s large population of SMEs. The European Commission reported that only 69% of EU SMEs had achieved at least a basic level of digital intensity in 2022, below the EU’s 2030 target of 90%. Although larger industrial companies generally have greater financial capacity for automation investments, smaller manufacturers may delay DCS upgrades because of capital constraints and uncertainty regarding return on investment. Furthermore, DCS modernization can require production shutdowns or phased implementation, potentially disrupting operations. Vendors therefore need to demonstrate measurable benefits through energy savings, productivity improvements, reduced downtime, and lower maintenance costs to accelerate adoption across cost-sensitive industrial customers.
Cybersecurity Risks and Shortage of Digital Skills
Increasing connectivity between DCS platforms, industrial networks, cloud systems, IoT devices, and enterprise applications also creates greater cybersecurity exposure. Industrial control systems are increasingly connected to digital infrastructure, making protection against unauthorized access, malware, ransomware, and operational disruption essential. A cybersecurity incident affecting a DCS could potentially interrupt production, damage equipment, compromise safety, or create significant financial losses.
At the same time, European companies face challenges in developing the workforce required to operate increasingly sophisticated digital control environments. The European Commission has identified limitations in the availability of digital skills across several industrial ecosystems. The rapid development of AI, cloud computing, industrial IoT, data analytics, and digital twins further increases the need for engineers and technicians with multidisciplinary capabilities. Europe’s digitalization strategy therefore places growing emphasis on cybersecurity, interoperability, secure data sharing, and digital skills. For DCS vendors and industrial operators, addressing cybersecurity vulnerabilities while investing in employee training will remain essential for achieving reliable and secure automation deployment.
Distributed Control Systems Launches in Europe
- ABB Ability™ Symphony® Plus – February 2023: ABB launched an updated Symphony Plus DCS with enhanced digital connectivity, secure OPC UA integration, HTML5-based mobile operations, and a new process controller for power-generation and water applications.
- Emerson DeltaV™ Bioreactor Integration – August 2023: Emerson collaborated with Sartorius to integrate bioreactors with the DeltaV DCS, supporting streamlined biopharmaceutical manufacturing and commercialization of medicines.
- ABB Ability™ System 800xA® – 2023: ABB expanded the capabilities of its System 800xA platform to support digitalization, integrated process control, electrical systems, safety, and plant-wide operational management.
- Emerson DeltaV™ Automation Platform – March 2024: Emerson evolved its DeltaV DCS into a broader automation platform incorporating SCADA, MES, operations management, DCS, and safety-system technologies for more integrated industrial operations.
- ABB Ability™ System 800xA® 6.2 – May 2024: ABB launched Version 6.2 of its flagship DCS with enhanced OPC UA capabilities, Ethernet-APL device integration, expanded PROFINET support, and improved engineering flexibility.
- Emerson DeltaV™ DCS Upgrade at Wesseling, Germany – February 2024: LyondellBasell selected Emerson’s DeltaV DCS and DeltaV Live software to modernize control systems at its Wesseling facility, covering major petrochemical processing units.
- ABB Freelance® 2024 – October 2024: ABB introduced Freelance 2024 with improved connectivity, faster device communication, Windows 11 compatibility, Microsoft Defender integration, PROFINET support, and NAMUR Open Architecture capabilities.
- ABB System 800xA® for BASF Ethernet-APL Project – 2024: BASF selected ABB’s System 800xA for its first European greenfield Ethernet-APL project, supporting modern industrial networking and process automation.
- Yokogawa CENTUM VP R7 – 2025: Yokogawa released CENTUM VP R7, marking the 50th anniversary of CENTUM and introducing enhanced cybersecurity, integrated plant data, early process-condition detection, and AI-supported autonomous-operation capabilities.
- ABB System 800xA® DCS Migration at Ravago Greece – July 2025: Ravago’s Lavrion chemical plant in Greece commissioned ABB System 800xA following a zero-downtime migration from the legacy MOD5 process control system, demonstrating demand for modernization of aging European DCS infrastructure.
Growing Adoption of Advanced Automation Software
Europe Distributed Control Systems Software Market is expanding as industrial operators increasingly adopt advanced software for process monitoring, control, analytics, optimization, and predictive maintenance. Software is a key component of modern DCS architectures, enabling operators to visualize plant operations, analyze real-time data, integrate industrial IoT devices, and improve production decisions. Europe’s DCS market is projected to grow steadily, supported by increasing Industry 4.0 adoption, modernization of aging industrial infrastructure, and demand for interconnected control platforms.
Increasing Demand for System Integration and Lifecycle Support
Europe Distributed Control Systems Services Market is benefiting from growing requirements for system engineering, installation, integration, commissioning, maintenance, upgrades, cybersecurity, and technical support. Services are particularly important as European manufacturers and process industries modernize legacy control infrastructure without disrupting continuous production. DCS service providers help organizations integrate new platforms with existing PLCs, SCADA systems, sensors, industrial networks, and enterprise software while ensuring system reliability and regulatory compliance. The European DCS market is segmented into hardware, software, and services, with services becoming increasingly important as installed systems require modernization and long-term maintenance. The European market is also supported by a large installed industrial base across Germany, France, the UK, Italy, and other manufacturing economies. Rising adoption of predictive maintenance, remote monitoring, cybersecurity services, and digital upgrades is creating additional opportunities. As DCS architectures become more connected and technologically sophisticated, customers increasingly require specialized expertise throughout the system lifecycle. Consequently, service providers are expected to benefit from recurring maintenance contracts, modernization projects, consulting services, and integration requirements.
Process Automation and Safety Requirements Driving Chemical Industry Adoption
Europe Chemicals Distributed Control Systems Market is being driven by the chemical industry’s need for precise process control, operational safety, production consistency, and energy efficiency. Chemical manufacturing involves complex continuous and batch processes where variables such as temperature, pressure, flow, and chemical composition must be monitored and controlled accurately. DCS platforms enable centralized plant visibility while distributing control functions across multiple process units, helping manufacturers improve reliability and respond quickly to process variations. Chemicals are identified as a key end-use segment within the European DCS industry, alongside power generation, oil and gas, pharmaceuticals, food and beverages, and other process industries. Industry modernization is further encouraging chemical producers to integrate DCS with industrial IoT, advanced analytics, digital twins, and predictive maintenance systems. Energy optimization is particularly significant because chemical production can be highly energy intensive. Modern DCS solutions can monitor energy consumption and optimize operating parameters to reduce waste and improve plant efficiency. The increasing emphasis on sustainability, emissions reduction, process safety, and regulatory compliance is therefore expected to strengthen DCS adoption across Europe’s chemical manufacturing facilities.
Digital Manufacturing and Stringent Quality Requirements Supporting Growth
Europe Pharmaceuticals Distributed Control Systems Market is expanding as pharmaceutical manufacturers increase automation, digitalization, and investment in highly controlled production environments. DCS platforms are particularly valuable for pharmaceutical operations because they provide real-time monitoring and control of critical parameters during manufacturing, processing, utilities, and facility operations. They can support temperature, pressure, humidity, flow, and other process variables while maintaining detailed operational records and improving production consistency. Pharmaceuticals are recognized as a major end-use segment of Europe’s DCS market, alongside chemicals, power generation, oil and gas, food and beverages, and other industries. Europe’s strong pharmaceutical manufacturing base and emphasis on quality, traceability, safety, and regulatory compliance create favorable conditions for advanced control technologies. DCS platforms are increasingly being integrated with data analytics, industrial IoT, electronic batch records, and predictive-maintenance applications. The shift toward flexible manufacturing and increasingly sophisticated production processes is also encouraging manufacturers to upgrade legacy automation systems. As pharmaceutical companies invest in smart factories and digitally connected production environments, demand for reliable, scalable, and compliant DCS software, hardware, and services is expected to increase across Europe.
Industrial Automation and Digitalization Supporting United Kingdom Market Growth
United Kingdom distributed control systems market is benefiting from continued investment in industrial automation, digital transformation, and modernization of production infrastructure. UK manufacturers and process industries are increasingly adopting connected control technologies to improve operational visibility, production efficiency, and asset performance. According to the Office for National Statistics, 69% of UK firms adopted cloud-based computing systems and applications in 2023, while AI adoption reached 9%, highlighting the country’s increasing use of digital technologies. DCS solutions are particularly relevant to energy, pharmaceuticals, chemicals, water and wastewater, food processing, and manufacturing, where continuous monitoring and precise process control are essential. UK manufacturers recorded £452.0 billion in product sales in 2025, demonstrating the substantial industrial base supporting demand for automation technologies. Furthermore, increasing emphasis on predictive maintenance, energy optimization, cybersecurity, and operational resilience is encouraging companies to replace aging control architectures with integrated DCS platforms. As UK industries pursue productivity improvements and smarter production environments, demand for scalable and digitally connected distributed control systems is expected to increase.
Industry 4.0 and Advanced Manufacturing Driving Germany Adoption
Germany represents one of Europe’s most important markets for distributed control systems, supported by its large manufacturing sector and strong emphasis on industrial automation and Industry 4.0. German manufacturers increasingly use connected control technologies to improve production efficiency, monitor equipment in real time, integrate operational data, and optimize complex industrial processes. DCS solutions have applications across chemicals, pharmaceuticals, energy, automotive manufacturing, food processing, and other process-intensive industries. The country’s industrial transformation is increasingly supported by AI, industrial IoT, robotics, cloud computing, and data analytics, creating opportunities for more intelligent process-control architectures. Germany’s advanced manufacturing environment also encourages companies to modernize legacy control infrastructure and integrate DCS platforms with plant-level and enterprise-level digital systems. Energy efficiency and decarbonization are additional considerations because industrial operators are under increasing pressure to reduce energy consumption while maintaining productivity. Consequently, DCS platforms that provide real-time monitoring, advanced process control, predictive maintenance, and centralized operational visibility are becoming increasingly valuable. Germany’s continuing focus on technological competitiveness and smart manufacturing is expected to sustain DCS investment across its industrial ecosystem.
Digital Transformation and Industrial Modernization Creating France Opportunities
France distributed control systems market is supported by industrial modernization, increasing automation, and the adoption of digital technologies across manufacturing and process industries. DCS solutions are increasingly used in energy, chemicals, pharmaceuticals, water management, food processing, and other industries requiring continuous and reliable process control. France’s industrial base is also undergoing renewed investment, with the country’s industrial barometer recording a positive balance of +19 significant factory openings and expansions in 2025, meaning openings and expansions exceeded closures and major reductions. This modernization activity creates opportunities for advanced automation and process-control systems. Digital transformation is further strengthening demand for DCS platforms capable of integrating industrial IoT, analytics, remote monitoring, and predictive maintenance. According to France’s national statistics institute INSEE, 18% of French enterprises with 10 or more employees used at least one AI technology in 2025, compared with 6% in 2023, indicating rapid growth in industrial and business digitalization. Sustainability is another important consideration, encouraging manufacturers to adopt technologies that optimize energy consumption and improve resource utilization. As French companies modernize facilities and pursue greater automation, DCS solutions are expected to remain an important component of industrial digital infrastructure.
Growing Digital Adoption and Manufacturing Modernization in Italy
Italy distributed control systems market is expanding as manufacturers and process industries increasingly invest in automation, digital technologies, and production optimization. DCS solutions are used across food and beverages, chemicals, pharmaceuticals, energy, utilities, and industrial processing to improve process consistency, equipment utilization, quality control, and operational efficiency. Italy’s digital transformation is gaining momentum: according to Istat, AI adoption among enterprises with at least 10 employees increased from 8.2% in 2024 to 16.4% in 2025, while the proportion using intermediate or advanced cloud-computing services reached 68.1%. The share of enterprises conducting data analysis also increased from 26.6% to 42.7% over the latest two-year period, demonstrating stronger use of data-driven technologies. These developments support the integration of DCS with industrial analytics, IoT platforms, cloud environments, and predictive-maintenance applications. In addition, Italy’s industrial operators are focusing on energy efficiency and sustainability, increasing demand for systems capable of monitoring resource consumption and optimizing production processes. As connected digital technologies become more embedded in Italian manufacturing, DCS adoption is expected to increase, particularly among larger process industries and companies undertaking plant modernization projects.
Recent Developments in Europe Distributed Control Systems Market
- LyondellBasell declared in February 2024 that it has chosen Emerson to update the company's software and control systems at its Wesseling facility in Germany. It is anticipated that the corporation would be able to enhance the operations of a butadiene manufacturing and ethylene cracker facility by implementing state-of-the-art automation technology. Emerson's DeltaV DCS and DeltaV Live software will be used to operate the ethylene cracker, while AMS Device Manager will assist with startup. MIMIC, a process simulation program, will be used to train operators and acquaint them with the new control system.
Europe Distributed Control Systems Market Segments
Component
- Hardware
- Software
- Services
End User
- Oil & Gas
- Power Generation
- Chemicals
- Food & Beverages
- Pharmaceuticals
- Metals & Mining
- Paper & Pulp
- Others
Countries
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Russia
- Poland
- Greece
- Norway
- Romania
- Portugal
- Rest of Europe
Companies have been covered from 5 viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- ABB
- Siemens AG
- Azbil Corporation
- Schneider Electric SE
- Valmet Oyj
- Omron Corporation
- Emerson Electric Co
- Honeywell International Inc.
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Form, Species, Distribution Channel and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.