United States Liquid Biopsy Market Report by Cancer Type, Product, Application, Biomarker, Sample Type, End User and State Forecast 2025-2034
Buy NowU.S. Liquid Biopsy Market Analysis: Clinical Adoption, Valuation, and Long-Term Forecast
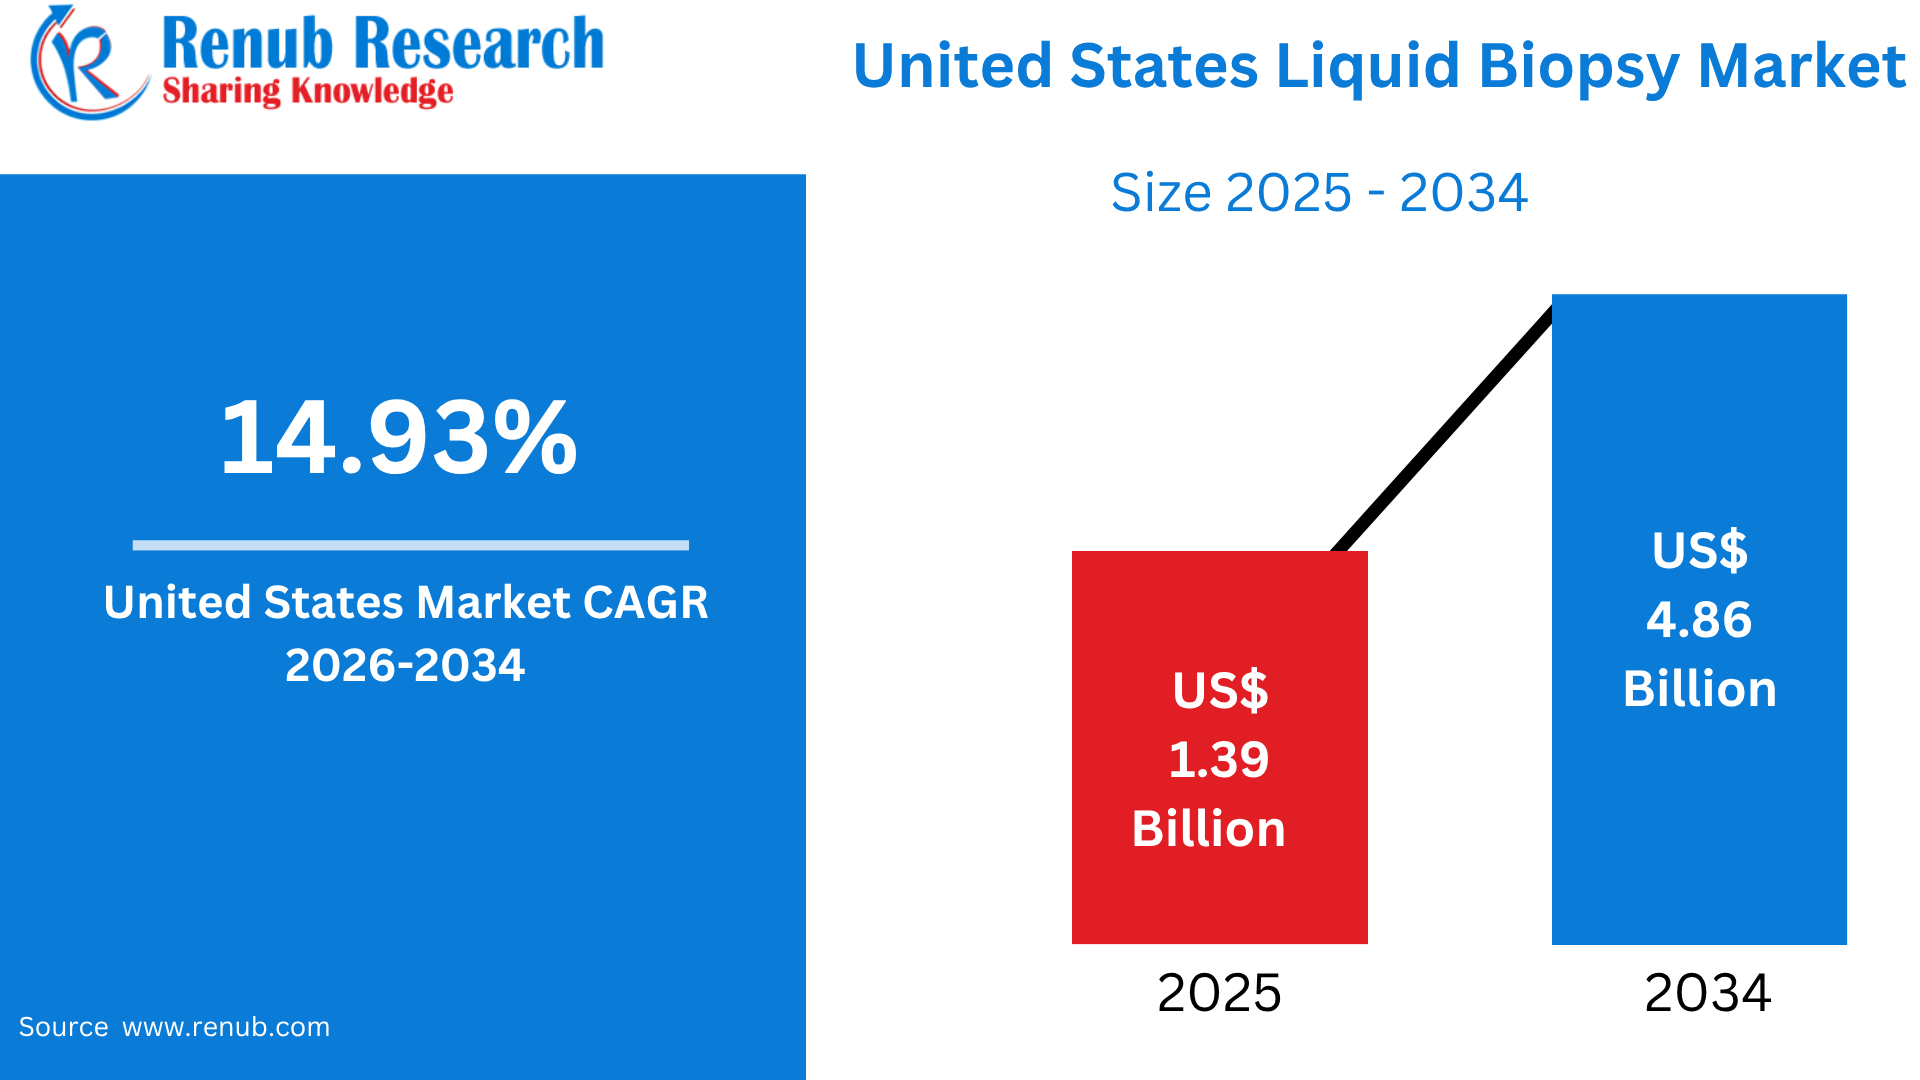
United States Liquid Biopsy Market is projected to expand from US$ 1.39 billion in 2025 to US$ 4.86 billion by 2034, registering a compound annual growth rate (CAGR) of 14.93% during the forecast period from 2026 to 2034. The market is experiencing robust growth due to the increasing demand for minimally invasive cancer diagnostic technologies and advancements in precision oncology. Liquid biopsy has emerged as a preferred diagnostic approach because it enables rapid, accurate, and non-invasive detection of cancer-related biomarkers through blood or other body fluid samples, reducing the need for conventional tissue biopsies.
What is Liquid Biopsy and Its Uses & Popularity in the United States
Liquid biopsy is an advanced molecular diagnostic technique that detects and analyzes cancer-related biomarkers from blood or other body fluids, eliminating the need for invasive tissue biopsies in many clinical situations. The test identifies circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), cell-free DNA (cfDNA), exosomes, and other molecular biomarkers that provide valuable information about the presence, progression, and genetic characteristics of cancer. Liquid biopsy is widely used for early cancer detection, companion diagnostics, treatment selection, monitoring therapeutic response, identifying minimal residual disease (MRD), detecting cancer recurrence, and tracking tumor mutations. Compared with conventional tissue biopsy, liquid biopsy offers faster results, reduced patient discomfort, lower procedural risks, and the ability to perform repeated testing throughout the course of treatment, making it particularly valuable for precision oncology.
In the United States, liquid biopsy has gained significant popularity due to the increasing burden of cancer, growing adoption of personalized medicine, and continuous advancements in genomic sequencing technologies. Leading hospitals, cancer centers, diagnostic laboratories, and pharmaceutical companies are increasingly integrating liquid biopsy into routine oncology practice for lung, breast, colorectal, prostate, and other cancers. Rising investments in cancer research, expanding clinical validation studies, and favorable regulatory support have accelerated commercialization of innovative liquid biopsy platforms. The growing use of next-generation sequencing (NGS), artificial intelligence-assisted genomic analysis, and precision medicine approaches continues to enhance diagnostic accuracy and treatment outcomes. As healthcare providers increasingly prioritize non-invasive diagnostics and personalized cancer care, liquid biopsy is becoming an essential component of modern oncology in the United States.
Cancer Statistics at a Glance: United States
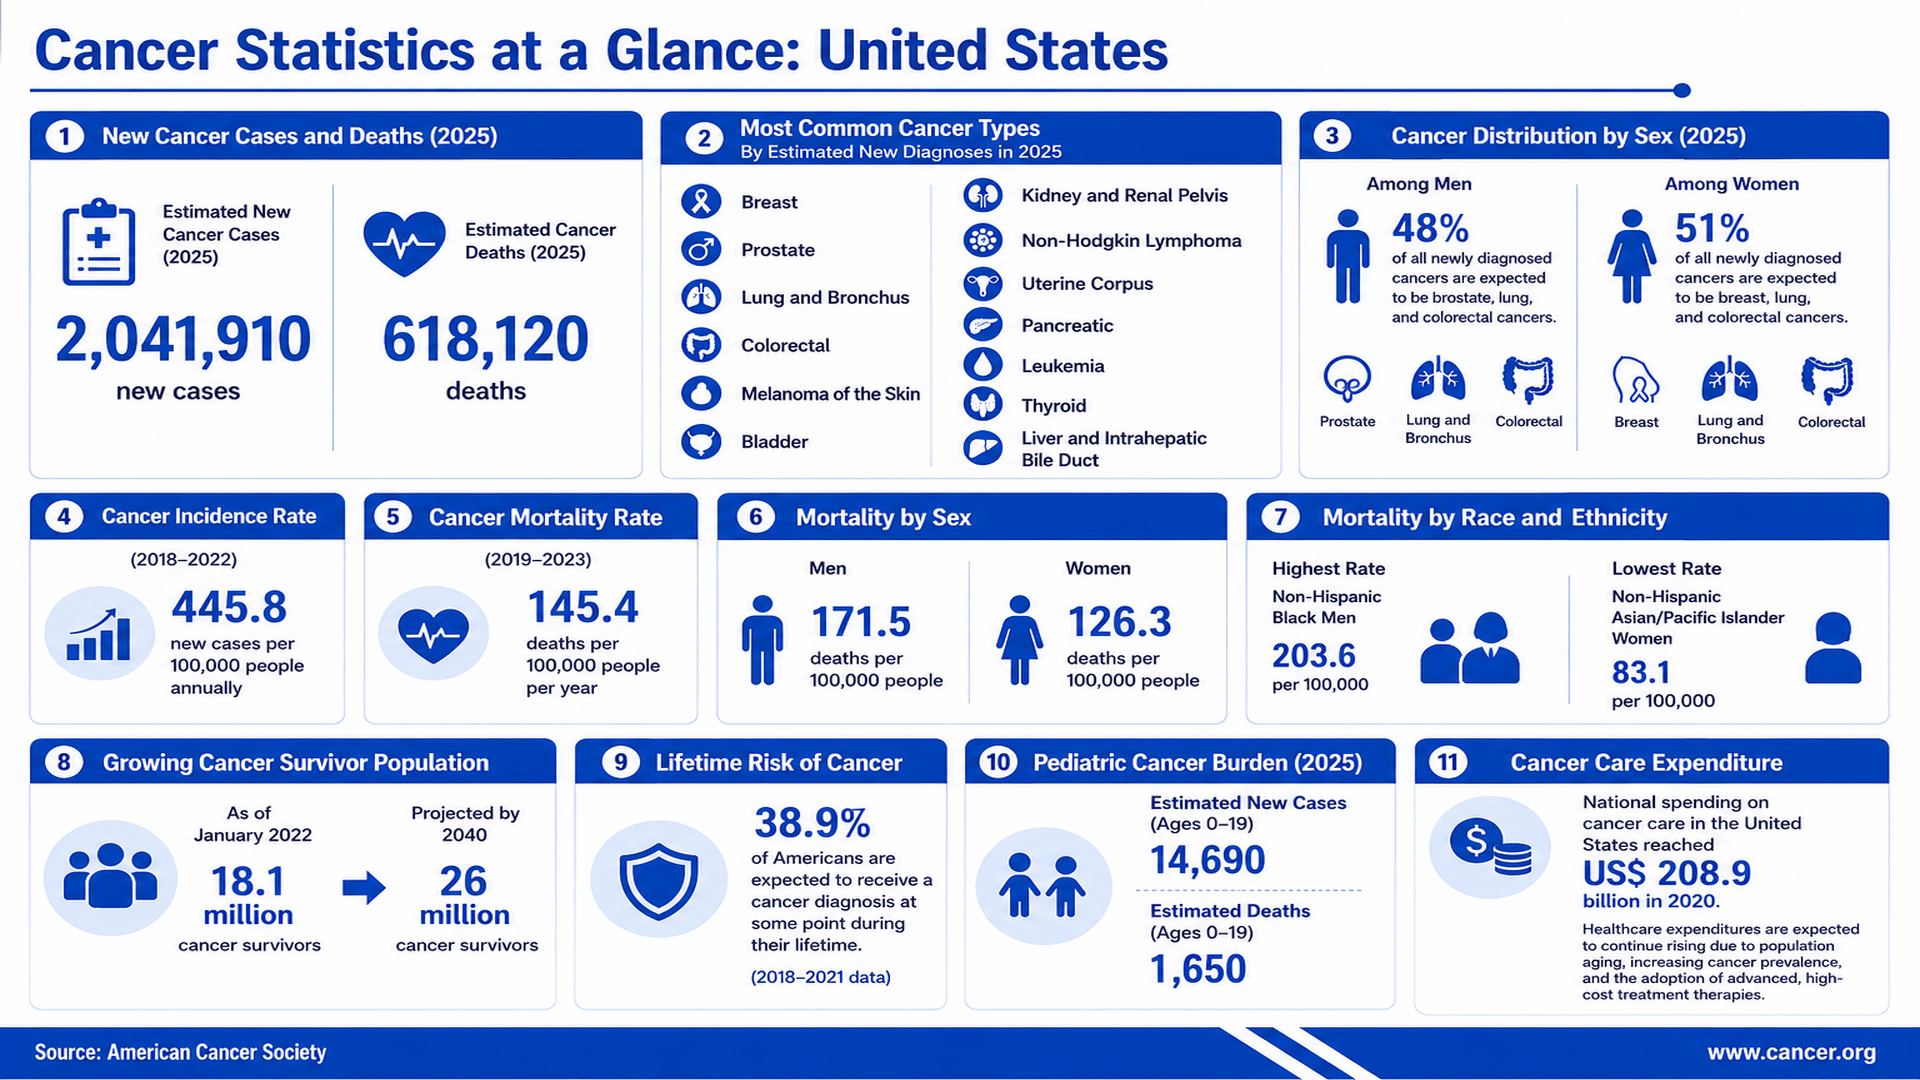
- New Cancer Cases and Deaths (2025): An estimated 2,041,910 new cancer cases are expected to be diagnosed in the United States in 2025, while approximately 618,120 people are projected to die from the disease.
- Most Common Cancer Types: The leading cancers by estimated new diagnoses in 2025 include breast, prostate, lung and bronchus, colorectal, melanoma, bladder, kidney and renal pelvis, non-Hodgkin lymphoma, uterine corpus, pancreatic, leukemia, thyroid, and liver/intrahepatic bile duct cancers.
- Cancer Distribution by Sex: Among men, prostate, lung, and colorectal cancers are expected to account for 48% of all newly diagnosed cancers in 2025. Among women, breast, lung, and colorectal cancers are projected to represent 51% of all new cancer diagnoses.
- Cancer Incidence Rate: Based on 2018–2022 data, the overall cancer incidence rate is estimated at 445.8 new cases per 100,000 people annually.
- Cancer Mortality Rate: According to 2019–2023 statistics, the overall cancer mortality rate stands at 145.4 deaths per 100,000 people per year.
- Mortality by Sex: Cancer-related mortality remains higher among men, with 171.5 deaths per 100,000, compared with 126.3 deaths per 100,000 among women.
- Mortality by Race and Ethnicity: The highest cancer mortality rate is observed among non-Hispanic Black men (203.6 per 100,000), while the lowest occurs among non-Hispanic Asian/Pacific Islander women (83.1 per 100,000).
- Growing Cancer Survivor Population: As of January 2022, the United States had an estimated 18.1 million cancer survivors, with projections indicating this number will increase to approximately 26 million by 2040.
- Lifetime Risk of Cancer: Approximately 38.9% of Americans are expected to receive a cancer diagnosis at some point during their lifetime, based on 2018–2021 data.
- Pediatric Cancer Burden: In 2025, an estimated 14,690 children and adolescents (ages 0–19) are expected to be diagnosed with cancer, while approximately 1,650 pediatric cancer-related deaths are projected.
- Cancer Care Expenditure: National spending on cancer care in the United States reached approximately US$ 208.9 billion in 2020. Healthcare expenditures are expected to continue rising due to population aging, increasing cancer prevalence, and the adoption of advanced, high-cost treatment therapies.
Cancer Statistics at a Glance: Worldwide
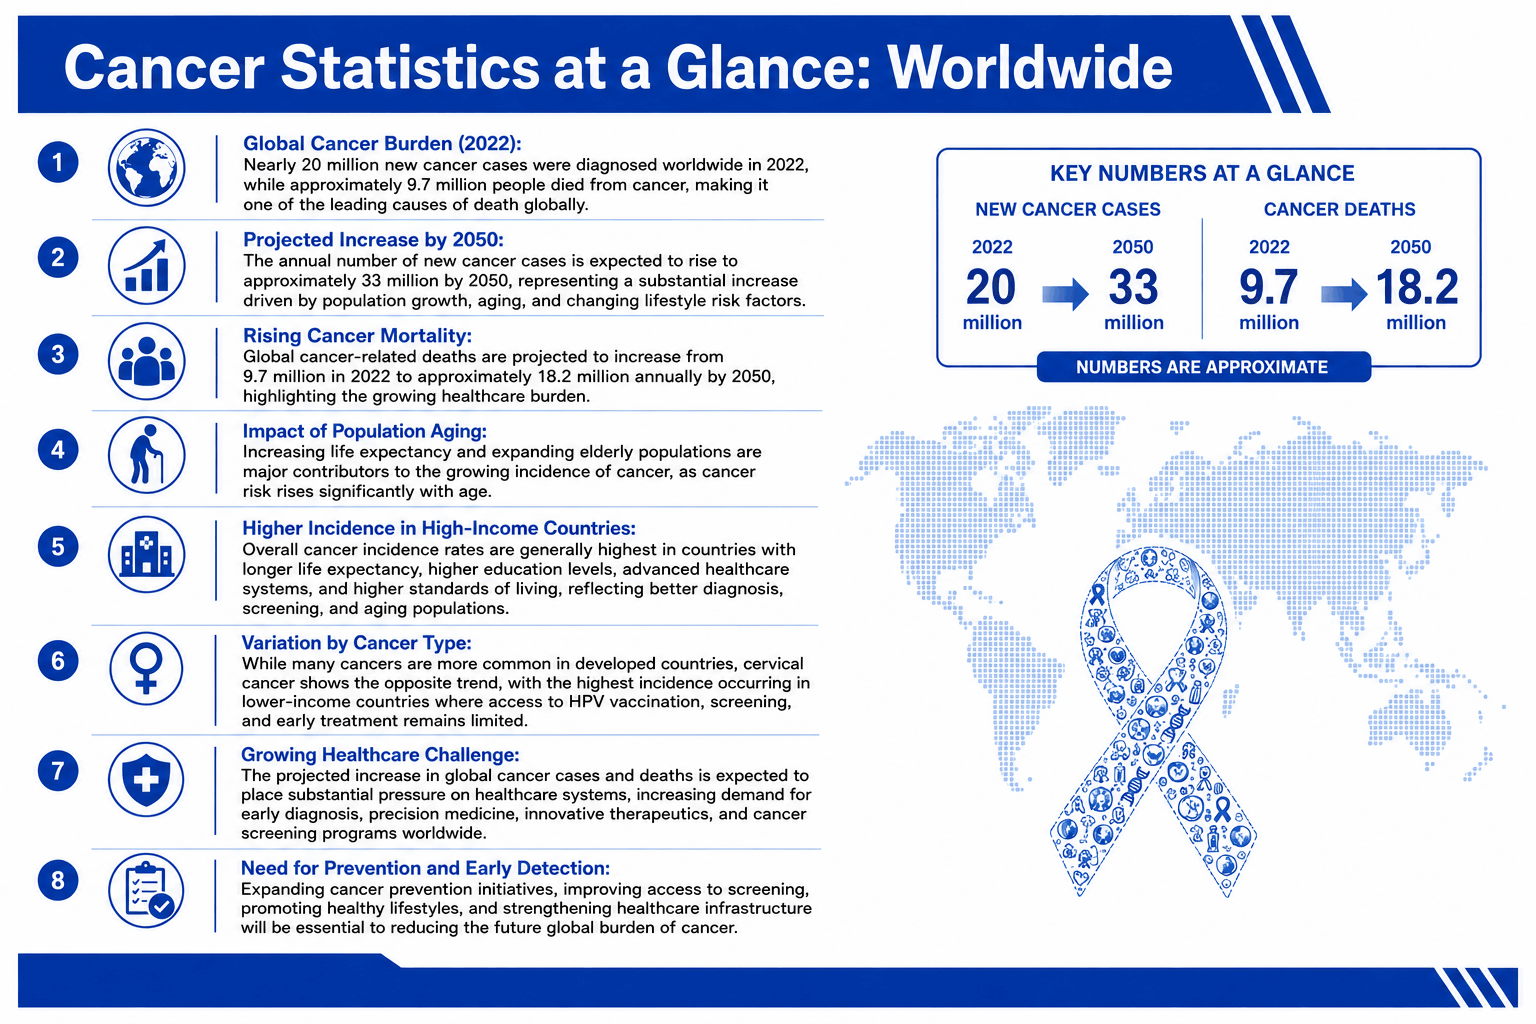
- Global Cancer Burden (2022): Nearly 20 million new cancer cases were diagnosed worldwide in 2022, while approximately 9.7 million people died from cancer, making it one of the leading causes of death globally.
- Projected Increase by 2050: The annual number of new cancer cases is expected to rise to approximately 33 million by 2050, representing a substantial increase driven by population growth, aging, and changing lifestyle risk factors.
- Rising Cancer Mortality: Global cancer-related deaths are projected to increase from 9.7 million in 2022 to approximately 18.2 million annually by 2050, highlighting the growing healthcare burden.
- Impact of Population Aging: Increasing life expectancy and expanding elderly populations are major contributors to the growing incidence of cancer, as cancer risk rises significantly with age.
- Higher Incidence in High-Income Countries: Overall cancer incidence rates are generally highest in countries with longer life expectancy, higher education levels, advanced healthcare systems, and higher standards of living, reflecting better diagnosis, screening, and aging populations.
- Variation by Cancer Type: While many cancers are more common in developed countries, cervical cancer shows the opposite trend, with the highest incidence occurring in lower-income countries where access to HPV vaccination, screening, and early treatment remains limited.
- Growing Healthcare Challenge: The projected increase in global cancer cases and deaths is expected to place substantial pressure on healthcare systems, increasing demand for early diagnosis, precision medicine, innovative therapeutics, and cancer screening programs worldwide.
- Need for Prevention and Early Detection: Expanding cancer prevention initiatives, improving access to screening, promoting healthy lifestyles, and strengthening healthcare infrastructure will be essential to reducing the future global burden of cancer.
Growth Driver
Rising Cancer Incidence and Increasing Demand for Early Detection
The growing burden of cancer in the United States is one of the primary drivers of the liquid biopsy market. According to national cancer estimates, more than 2 million new cancer cases are diagnosed annually in the U.S., while over 600,000 cancer-related deaths occur each year. Lung, breast, colorectal, prostate, and pancreatic cancers account for a significant proportion of these diagnoses, creating strong demand for accurate and minimally invasive diagnostic technologies. Liquid biopsy enables physicians to detect circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), and other cancer biomarkers using a simple blood sample, allowing earlier diagnosis and continuous disease monitoring. Unlike conventional tissue biopsy, liquid biopsy can be repeated multiple times during treatment without surgical intervention. Earlier detection significantly improves treatment planning and survival outcomes, particularly for high-risk patients. Increasing cancer screening initiatives, rising awareness of precision oncology, and growing demand for non-invasive diagnostics continue to accelerate adoption of liquid biopsy technologies across hospitals, oncology centers, and diagnostic laboratories throughout the United States.
Expansion of Precision Medicine and Next-Generation Sequencing (NGS)
The rapid expansion of precision medicine is significantly driving the United States liquid biopsy market. Precision oncology relies on genomic profiling to identify specific genetic mutations and biomarkers that help physicians select targeted therapies for individual patients. Liquid biopsy has become an important tool because it provides comprehensive molecular information without requiring invasive tissue collection. Advances in next-generation sequencing (NGS) have dramatically increased testing sensitivity, enabling simultaneous analysis of hundreds of cancer-related genes from a single blood sample. Pharmaceutical companies increasingly utilize liquid biopsy in companion diagnostics and clinical trials to identify patients most likely to benefit from targeted therapies. The growing availability of FDA-approved targeted cancer treatments has further increased demand for molecular testing. Investments in artificial intelligence, bioinformatics, and genomic analytics continue improving test accuracy and clinical utility. As personalized medicine becomes standard practice across oncology, liquid biopsy adoption is expected to expand rapidly throughout the U.S. healthcare system.
Technological Innovation and Growing Clinical Applications
Continuous technological advancements are expanding the clinical applications of liquid biopsy and supporting strong market growth in the United States. Modern liquid biopsy platforms now detect circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), exosomes, cell-free DNA (cfDNA), and circulating RNA biomarkers with high analytical sensitivity. Improvements in digital PCR, multiplex PCR, next-generation sequencing, and bioinformatics have significantly enhanced the ability to detect low-frequency mutations and minimal residual disease (MRD). Liquid biopsy is increasingly used not only for advanced cancer diagnosis but also for treatment selection, monitoring therapeutic response, recurrence surveillance, and identifying drug resistance mutations. Clinical research continues to evaluate its role in multi-cancer early detection and population-level cancer screening. Major biotechnology companies and academic research institutions are investing heavily in the development of new biomarker panels and automated testing platforms. Growing physician confidence, expanding regulatory approvals, and broader clinical validation are expected to further strengthen the adoption of liquid biopsy technologies across the United States.
Challenges
High Testing Costs and Reimbursement Limitations
Despite rapid technological progress, the high cost of liquid biopsy remains a significant challenge for widespread adoption in the United States. Comprehensive liquid biopsy tests using advanced genomic sequencing may cost several hundred to several thousand U.S. dollars per test, depending on the number of biomarkers analyzed and the complexity of genomic profiling. Although reimbursement coverage has improved for certain FDA-approved oncology applications, many emerging liquid biopsy tests continue to face inconsistent insurance reimbursement, particularly for early cancer screening and experimental clinical uses. Smaller hospitals and community healthcare providers may also face financial barriers when implementing advanced molecular diagnostic platforms. In addition, laboratories require specialized sequencing equipment, highly trained personnel, and sophisticated bioinformatics infrastructure, increasing operational expenses. Limited reimbursement can delay patient access, particularly among uninsured or underinsured populations. Expanding insurance coverage, reducing sequencing costs, and generating stronger clinical evidence demonstrating cost-effectiveness will be essential for increasing the accessibility and long-term commercial success of liquid biopsy technologies.
Sensitivity Limitations and Need for Clinical Standardization
Although liquid biopsy offers numerous clinical advantages, technical limitations and lack of universal standardization remain important challenges for the U.S. market. Detection sensitivity can vary depending on cancer type, disease stage, tumor burden, and the concentration of circulating tumor DNA in the bloodstream. Early-stage cancers often release only very small amounts of ctDNA, making accurate detection more difficult and increasing the possibility of false-negative results. Variability in sample collection, laboratory processing, sequencing platforms, biomarker selection, and analytical interpretation may also affect test consistency across different laboratories. While many liquid biopsy assays demonstrate high specificity, confirmatory tissue biopsy is still required in several clinical situations to establish definitive diagnoses. Furthermore, standardized clinical guidelines for certain emerging applications, including multi-cancer early detection and routine population screening, are still evolving. Continued clinical validation, harmonized laboratory protocols, and improvements in assay sensitivity will be critical for maximizing physician confidence and expanding the routine use of liquid biopsy in oncology practice across the United States.
Liquid Biopsy Product Launches in the United States
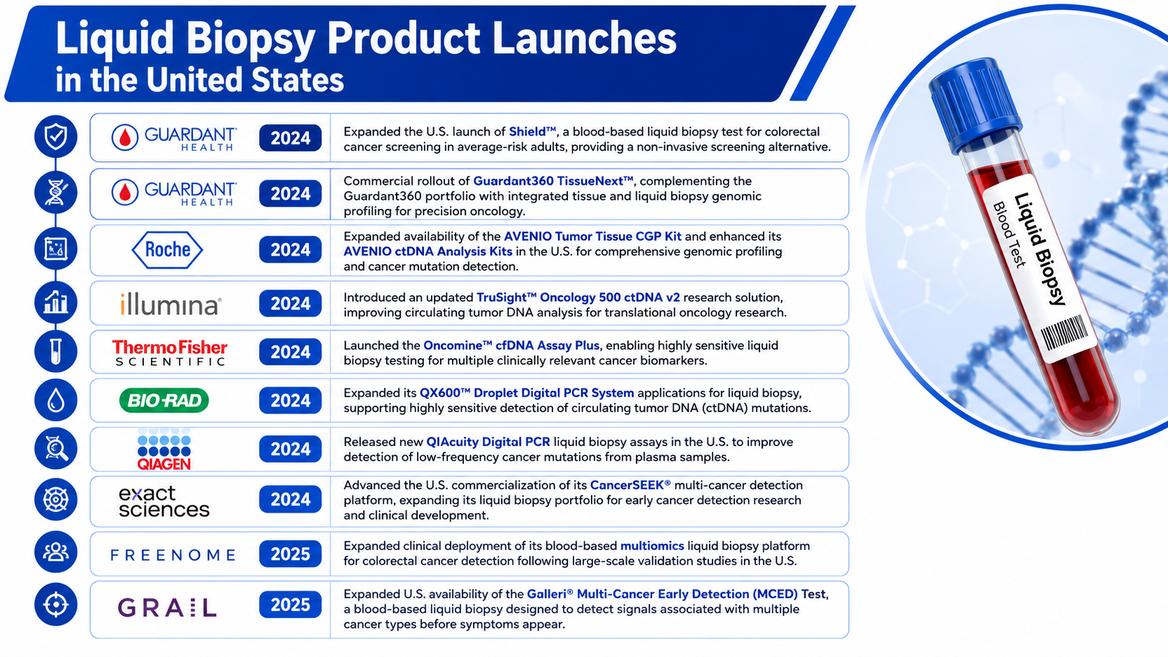
- Guardant Health (2024) – Expanded the U.S. launch of Shield™, a blood-based liquid biopsy test for colorectal cancer screening in average-risk adults, providing a non-invasive screening alternative.
- Guardant Health (2024) – Commercial rollout of Guardant360 TissueNext™, complementing the Guardant360 portfolio with integrated tissue and liquid biopsy genomic profiling for precision oncology.
- Roche (2024) – Expanded availability of the AVENIO Tumor Tissue CGP Kit and enhanced its AVENIO ctDNA Analysis Kits in the U.S. for comprehensive genomic profiling and cancer mutation detection.
- Illumina (2024) – Introduced an updated TruSight™ Oncology 500 ctDNA v2 research solution, improving circulating tumor DNA analysis for translational oncology research.
- Thermo Fisher Scientific (2024) – Launched the Oncomine™ cfDNA Assay Plus, enabling highly sensitive liquid biopsy testing for multiple clinically relevant cancer biomarkers.
- Bio-Rad Laboratories (2024) – Expanded its QX600™ Droplet Digital PCR System applications for liquid biopsy, supporting highly sensitive detection of circulating tumor DNA (ctDNA) mutations.
- QIAGEN (2024) – Released new QIAcuity Digital PCR liquid biopsy assays in the U.S. to improve detection of low-frequency cancer mutations from plasma samples.
- Exact Sciences (2024) – Advanced the U.S. commercialization of its CancerSEEK® multi-cancer detection platform, expanding its liquid biopsy portfolio for early cancer detection research and clinical development.
- Freenome (2025) – Expanded clinical deployment of its blood-based multiomics liquid biopsy platform for colorectal cancer detection following large-scale validation studies in the U.S.
- GRAIL (2025) – Expanded U.S. availability of the Galleri® Multi-Cancer Early Detection (MCED) Test, a blood-based liquid biopsy designed to detect signals associated with multiple cancer types before symptoms appear.
Growing Adoption for Precision Oncology Leads Lung Cancer Liquid Biopsy
United States lung cancer liquid biopsy market is experiencing strong growth due to the high burden of lung cancer and increasing adoption of precision medicine. Lung cancer accounts for approximately 12–13% of all new cancer cases in the U.S. and remains one of the leading causes of cancer-related mortality, creating sustained demand for rapid molecular diagnostics. Liquid biopsy enables detection of circulating tumor DNA (ctDNA) and clinically relevant genetic mutations such as EGFR, ALK, ROS1, BRAF, MET, KRAS, and RET, allowing physicians to select targeted therapies without invasive tissue sampling. Compared with conventional biopsies, liquid biopsy offers faster turnaround times and can be repeated throughout treatment to monitor therapeutic response and resistance mutations. Expanding use of next-generation sequencing (NGS), FDA-approved companion diagnostics, and personalized oncology has strengthened clinical adoption. Increasing investments in genomic research, broader reimbursement coverage for advanced cancer testing, and growing demand for minimally invasive diagnostics continue to support long-term expansion of the United States lung cancer liquid biopsy market.
Advancing Non-Invasive Disease Monitoring in Liquid Biopsy
United States prostate cancer liquid biopsy market is expanding steadily as clinicians increasingly utilize minimally invasive molecular testing to support diagnosis, treatment selection, and disease monitoring. Prostate cancer remains the most frequently diagnosed cancer among American men, with more than 300,000 new cases estimated annually. Liquid biopsy analyzes circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), and other genomic biomarkers to identify disease progression and therapeutic resistance. The technology is particularly valuable for monitoring metastatic prostate cancer and evaluating response to androgen receptor-targeted therapies and precision medicines. Compared with repeated tissue biopsies, liquid biopsy reduces patient discomfort while enabling continuous molecular surveillance throughout treatment. Advances in genomic sequencing, biomarker discovery, and artificial intelligence-based interpretation have significantly improved analytical performance. Pharmaceutical companies increasingly incorporate liquid biopsy into clinical trials for targeted oncology drugs. Rising awareness of personalized medicine, growing adoption of genomic testing, and continuous technological innovation are expected to drive sustained growth in the U.S. prostate cancer liquid biopsy market.
Increasing Demand for Molecular Diagnostic Consumables in Liquid Biopsy Kits & Reagents
United States liquid biopsy kits and reagents market is expanding rapidly due to growing adoption of molecular diagnostics across hospitals, reference laboratories, academic research institutions, and biotechnology companies. Liquid biopsy workflows require specialized consumables, including DNA extraction kits, PCR reagents, sequencing reagents, sample preservation tubes, mutation detection assays, and library preparation kits. The widespread implementation of next-generation sequencing (NGS) and digital PCR platforms has substantially increased demand for high-quality reagents with improved analytical sensitivity and reproducibility. Commercial laboratories process millions of molecular diagnostic tests annually, supporting recurring demand for consumable products. Continuous technological improvements have enhanced the detection of low-frequency mutations, enabling more accurate identification of circulating tumor DNA and other biomarkers. Biotechnology companies continue introducing automated sample preparation systems and standardized reagent kits to improve laboratory efficiency and reduce processing errors. Increasing investments in oncology research, expanding clinical laboratory capacity, and growing utilization of precision diagnostics continue to drive strong growth in the United States liquid biopsy kits and reagents market.
Liquid Biopsy Early Diagnosis Expanding Role in Cancer Screening in United States
The United States liquid biopsy early diagnosis market is gaining significant momentum as healthcare providers increasingly focus on early cancer detection and preventive oncology. Liquid biopsy allows clinicians to identify circulating tumor DNA, cell-free DNA, exosomes, and other biomarkers before clinical symptoms become apparent, enabling earlier intervention and improved patient outcomes. Cancer survival rates increase substantially when malignancies are detected during localized stages, encouraging investment in innovative screening technologies. Multi-cancer early detection (MCED) tests capable of identifying molecular signals associated with multiple cancer types from a single blood sample are attracting considerable clinical and commercial interest. Large-scale clinical studies continue evaluating the effectiveness of these technologies across high-risk populations. Artificial intelligence, machine learning, and advanced bioinformatics have further improved biomarker interpretation and diagnostic accuracy. Increasing public awareness of preventive healthcare, rising demand for non-invasive screening methods, expanding clinical validation, and continued investment in precision medicine are expected to accelerate the growth of the United States liquid biopsy early diagnosis market.
United States ctDNA Liquid Biopsy Core Technology Driving Precision Cancer Management
The United States circulating tumor DNA (ctDNA) liquid biopsy market represents one of the fastest-growing segments within molecular oncology diagnostics. ctDNA consists of small fragments of tumor-derived DNA released into the bloodstream, providing valuable genomic information without requiring invasive tissue biopsy. Modern ctDNA assays can identify clinically significant mutations, monitor treatment response, detect minimal residual disease (MRD), evaluate disease recurrence, and identify emerging drug resistance. Highly sensitive next-generation sequencing (NGS) and digital PCR technologies now enable detection of extremely low concentrations of ctDNA, improving clinical decision-making across multiple cancer types including lung, breast, colorectal, prostate, and melanoma. Pharmaceutical companies increasingly rely on ctDNA testing during clinical trials to evaluate targeted therapies and monitor molecular treatment response. Growing integration of ctDNA analysis into precision oncology programs, expanding regulatory approvals, continuous technological innovation, and increasing physician confidence in molecular diagnostics are expected to support sustained long-term growth of the United States ctDNA liquid biopsy market.
Florida Liquid Biopsy Expanding Precision Oncology Through Advanced Cancer Care
Florida’s liquid biopsy market is growing rapidly due to its large population of more than 23 million residents, rising cancer incidence, and well-established healthcare infrastructure. The state records over 150,000 new cancer diagnoses annually, creating strong demand for minimally invasive diagnostic technologies. Major cancer centers, academic hospitals, and specialized oncology clinics are increasingly adopting liquid biopsy for early cancer detection, genomic profiling, treatment selection, and disease monitoring. Liquid biopsy enables detection of circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), and other biomarkers through a simple blood sample, reducing the need for repeated tissue biopsies. Florida’s large elderly population, with over 21% of residents aged 65 years and older, further supports demand because cancer prevalence increases significantly with age. Expansion of precision medicine programs, next-generation sequencing (NGS) laboratories, and personalized oncology services continues to improve diagnostic capabilities. Growing investments in biotechnology research, increasing physician awareness, and broader clinical adoption are expected to drive sustained long-term growth of Florida’s liquid biopsy market.
New York Strong Research Infrastructure Driving Market Growth
New York represents one of the leading liquid biopsy markets in the United States due to its advanced healthcare system, world-class research institutions, and high concentration of specialized cancer centers. The state has a population exceeding 19 million people and reports well over 100,000 new cancer cases annually, supporting increasing demand for molecular diagnostic technologies. Liquid biopsy is widely utilized for genomic profiling, companion diagnostics, treatment monitoring, minimal residual disease (MRD) detection, and recurrence surveillance across multiple cancer types. Academic medical centers and biotechnology companies continue investing in next-generation sequencing (NGS), artificial intelligence, and precision oncology research to improve diagnostic accuracy. Clinical laboratories increasingly incorporate liquid biopsy into routine oncology workflows because of its rapid turnaround time and non-invasive nature. Strong collaboration between healthcare providers, pharmaceutical companies, and genomic testing laboratories continues accelerating innovation. Increasing cancer screening programs, expanding reimbursement for molecular diagnostics, and growing physician confidence are expected to support continued expansion of New York’s liquid biopsy market.
Texas Liquid Biopsy Rapid Healthcare Expansion Supporting Precision Diagnostics
Texas has become one of the fastest-growing liquid biopsy markets in the United States, driven by its population of more than 31 million residents, expanding healthcare infrastructure, and rising cancer burden. The state reports more than 140,000 newly diagnosed cancer cases annually, generating substantial demand for advanced molecular diagnostics. Major metropolitan areas including Houston, Dallas, Austin, and San Antonio host internationally recognized cancer hospitals, academic research institutions, and genomic medicine centers that increasingly utilize liquid biopsy technologies. Blood-based molecular testing is being adopted for early cancer detection, targeted therapy selection, treatment monitoring, and identification of resistance mutations across lung, colorectal, breast, and prostate cancers. Expansion of biotechnology research, precision medicine initiatives, and clinical trial activity continues strengthening market development. Investments in high-throughput sequencing platforms, digital PCR technologies, and laboratory automation have improved diagnostic performance. Rising healthcare expenditure, increasing patient awareness, and continued innovation in personalized oncology are expected to sustain long-term growth of the Texas liquid biopsy market.
California Market Driven by Biotechnology Innovation
California represents the largest liquid biopsy market in the United States due to its population approaching 40 million residents, globally recognized biotechnology industry, and leadership in precision medicine research. The state reports more than 190,000 new cancer diagnoses annually, creating significant demand for advanced cancer diagnostics. California is home to numerous biotechnology companies, genomic testing laboratories, academic medical centers, and comprehensive cancer institutes actively developing next-generation liquid biopsy technologies. Liquid biopsy is widely used for circulating tumor DNA (ctDNA) analysis, companion diagnostics, early cancer detection, treatment response monitoring, and recurrence surveillance. Extensive adoption of next-generation sequencing (NGS), artificial intelligence-assisted genomic analysis, and precision oncology has strengthened clinical utilization throughout the state. California also leads in clinical research evaluating multi-cancer early detection tests and novel biomarker discovery. Continuous investment in biotechnology innovation, expanding personalized medicine programs, and strong collaboration between healthcare providers and life science companies position California as the leading state market for liquid biopsy in the United States.
Market Segments
Cancer Types
- Lung Cancer
- Breast Cancer
- Colorectal Cancer
- Prostate Cancer
- Liver Cancer
- Other Cancer
Products
- Kits & Reagents
- Platforms & Instruments
- Services
Application
- Early Diagnosis
- Patient Monitoring
- Recurrence Monitoring
Biomarkers
- Circulating Tumor Cells (CTCs)
- Circulating Tumor DNA (ctDNA)
- Extracellular Vesicles (EVs)
Sample Types
- Blood
- Urine
- Others
End-Users
- Hospitals & Laboratories
- Governments & Academic Research Centers
Top States
- California
- Texas
- New York
- Florida
- Illinois
- Pennsylvania
- Ohio
- Georgia
- New Jersey
- Washington
- North Carolina
- Massachusetts
- Virginia
- Michigan
- Maryland
- Colorado
- Tennessee
- Indiana
- Arizona
- Minnesota
- Wisconsin
- Missouri
- Connecticut
- South Carolina
- Oregon
- Louisiana
- Alabama
- Kentucky
- Rest of United States
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Company Analysis:
- Thermo Fisher Scientific Inc.
- Roche Diagnostics
- Bio-Rad Laboratories Inc.
- Biocept, Inc.
- Biocartis
- Myriad Genetics, Inc.
- Exact Sciences (Genomic Health)
- NeoGenomics Laboratories
- Quest Diagnostic Inc.
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Cancer Types, Product, Biomarkers, Application, Sample Types & End User and States |
| States Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.