North America Gluten Free Food Market Report by Product Type, Form, Source, Plant Sources, Distribution Channel, Countries and Companies Analysis 2026-2034
Buy NowNorth America Gluten Free Food Market Size and Forecast
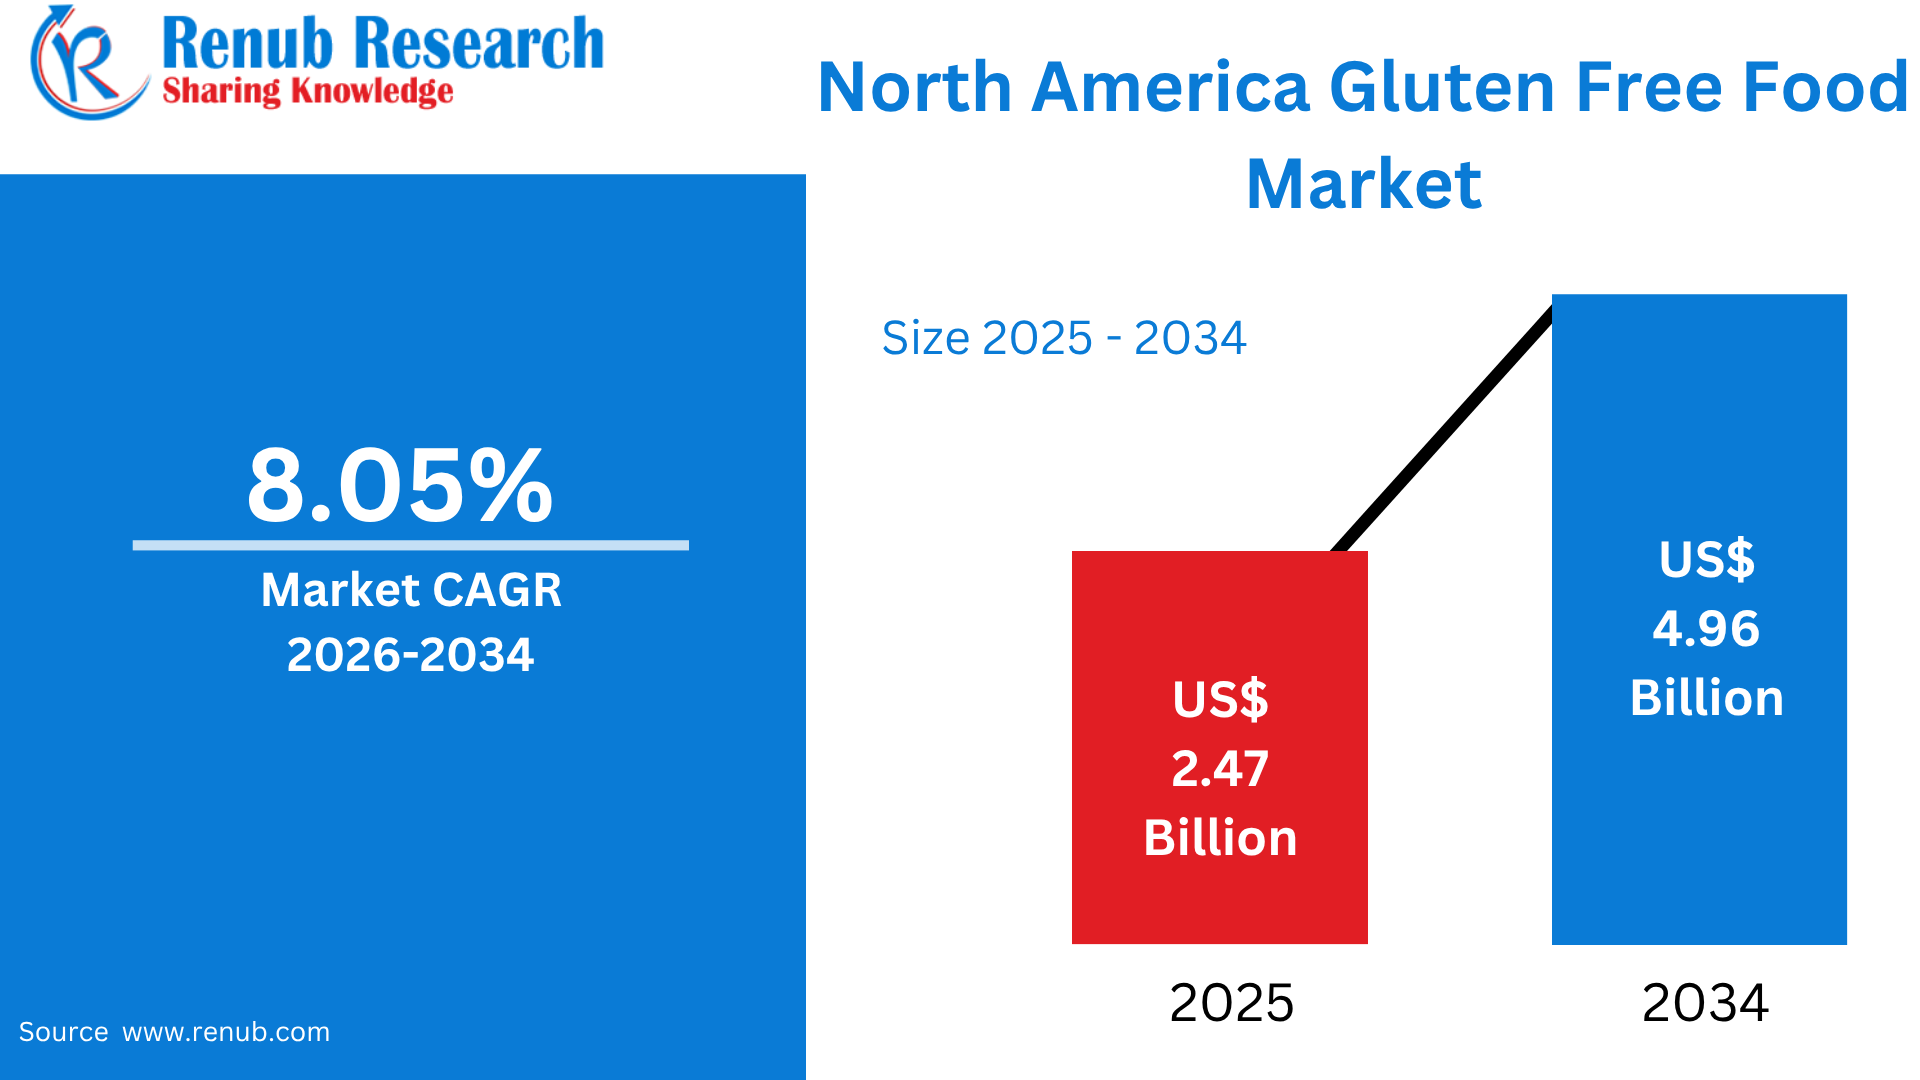
North America gluten-free food market is projected to reach US$ 4.96 billion by 2034, rising from US$ 2.47 billion in 2025, at a CAGR of 8.05% during 2026–2034. The market is poised for consistent expansion, supported by growing awareness of celiac disease and gluten sensitivity, increasing health and wellness consciousness, evolving dietary preferences, and continuous innovation in gluten-free products. In addition, wider availability through supermarkets, specialty stores, and online retail platforms is improving consumer accessibility. Manufacturers are also expanding product portfolios across bakery products, snacks, pasta, ready-to-eat meals, and beverages, further strengthening demand across North America.
What is Gluten-Free Food and Its Uses & Popularity in North America
Gluten-free food refers to products formulated without gluten, a group of proteins naturally present in wheat, rye, barley, and related grains. These foods are particularly important for people with celiac disease, wheat-related disorders, or non-celiac gluten sensitivity, while they are also increasingly consumed by individuals seeking specific dietary and wellness benefits. In the United States, the FDA permits the “gluten-free” claim when unavoidable gluten levels remain below 20 parts per million (ppm), providing a standardized benchmark for manufacturers and consumers.
Gluten-free products are used across numerous categories, including bread, bakery products, pasta, cereals, snacks, sauces, frozen foods, ready-to-eat meals, beverages, and desserts. Their popularity in North America is supported by growing awareness of celiac disease and gluten sensitivity. Approximately 1 in 133 Americans, or about 1% of the population, is estimated to have celiac disease, while up to 6% may experience non-celiac gluten sensitivity. The expanding availability of gluten-free products in supermarkets, specialty stores, restaurants, and e-commerce platforms is further strengthening consumer adoption.
Growth Driver
Rising Prevalence and Awareness of Celiac Disease and Gluten Sensitivity
The increasing recognition of celiac disease, non-celiac gluten sensitivity, and wheat-related dietary concerns is a major growth driver for the North American gluten-free food market. An estimated 1 in 133 Americans, or approximately 1% of the U.S. population, has celiac disease, while recent screening studies suggest prevalence could be higher. In addition, up to 6% of Americans may have non-celiac gluten sensitivity, creating a broader consumer base for gluten-free products. Greater awareness among consumers, healthcare professionals, nutritionists, and patient organizations is encouraging more people to identify gluten-related dietary requirements and seek appropriate alternatives. Since there is currently no pharmaceutical cure for celiac disease and maintaining a strict gluten-free diet remains the principal management approach, demand for safe and convenient food alternatives is structurally supported. Food manufacturers are responding by introducing gluten-free versions of mainstream products, including breads, pasta, cereals, snacks, and frozen meals. As diagnosis and awareness improve, demand is expected to expand beyond medically necessary consumers toward households seeking reliable gluten-free options for family members.
Stronger Regulatory Standards and Consumer Confidence in Gluten-Free Labels
The establishment of standardized gluten-free labeling requirements in the United States has strengthened consumer confidence and supported market development. The FDA requires foods carrying the “gluten-free,” “free of gluten,” “without gluten,” or “no gluten” claim to contain less than 20 ppm of gluten. Manufacturers must also ensure that gluten-containing grains such as wheat, rye, and barley are not used in ways that violate the regulatory definition. This standardized threshold reduces uncertainty for consumers, particularly those with celiac disease who need to avoid gluten consistently. FDA surveillance has also demonstrated a high level of compliance: an analysis of 702 samples from more than 250 gluten-free products found that more than 99.5% complied with the applicable gluten requirement. Such regulatory credibility helps differentiate compliant products from misleading claims and encourages manufacturers to invest in testing, quality control, ingredient traceability, and dedicated production practices. As consumers increasingly examine labels and expect transparency, companies that provide clearly verified gluten-free products can strengthen brand trust and capture greater shelf space across supermarkets, specialty retailers, foodservice channels, and online marketplaces.
Product Innovation and Expansion Across Mainstream Food Categories
Product innovation is expanding the addressable market for gluten-free foods across North America. Instead of being concentrated primarily in specialty bakery products, gluten-free offerings are increasingly available across bread, pasta, breakfast cereals, snacks, desserts, sauces, frozen meals, beverages, and ready-to-eat products. This diversification allows consumers to maintain familiar eating habits while replacing conventional wheat-based products with gluten-free alternatives. The FDA notes that naturally gluten-free foods can also carry a gluten-free claim when they meet the applicable requirements, while grains such as rice, buckwheat, and oats may qualify when unavoidable gluten remains below the regulatory threshold. This creates opportunities for manufacturers to develop products using alternative ingredients such as rice, corn, quinoa, buckwheat, legumes, and other specialty grains. Companies are also focusing on improving taste, texture, nutritional value, protein content, fiber, and convenience because earlier gluten-free products were often criticized for sensory and nutritional limitations. Innovation is therefore helping move gluten-free food from a niche dietary category toward mainstream packaged food. Wider product choice, improved formulations, premium positioning, and new retail formats are expected to sustain market growth through the forecast period.
Challenge
Higher Production Costs and Pricing Pressure
Higher production and formulation costs remain an important challenge for the North American gluten-free food market. Manufacturers often need specialized ingredients, alternative flours, additional testing, dedicated processing controls, and stringent measures to prevent gluten cross-contact. These requirements can increase manufacturing expenses compared with conventional wheat-based products. Gluten-free manufacturers also need to manage supplier verification and quality-control procedures carefully because ingredients and production environments can introduce unintended gluten. The FDA specifically highlights cross-contact as an important consideration and requires unavoidable gluten in foods carrying a gluten-free claim to remain below 20 ppm. Manufacturers may therefore incur additional costs through laboratory testing, supplier certificates, cleaning procedures, segregated production areas, employee training, and quality assurance systems. These expenses can translate into higher retail prices, potentially limiting adoption among price-sensitive consumers. Premium pricing may be acceptable for consumers with medically necessary dietary requirements, but it can discourage broader mainstream consumption. Companies consequently face pressure to improve manufacturing efficiency, optimize ingredient sourcing, increase production scale, and develop cost-effective formulations while maintaining product quality and regulatory compliance.
Cross-Contact Risks, Supply-Chain Complexity and Consumer Trust
Managing gluten cross-contact is a persistent operational challenge because even products formulated with gluten-free ingredients can become contaminated during processing, storage, transportation, or food preparation. Shared manufacturing equipment, inadequate cleaning, incorrect ingredient handling, and inconsistent supplier controls can create risks for consumers who require strict gluten avoidance. The FDA specifically identifies cross-contact as an important issue addressed by the gluten-free labeling framework. The challenge extends beyond packaged foods into restaurants and foodservice establishments, where kitchen surfaces, utensils, fryers, and preparation areas may be shared between gluten-containing and gluten-free meals. Consumers with celiac disease therefore need greater assurance that products and meals are genuinely safe. Manufacturers must invest in supplier qualification, ingredient traceability, testing, sanitation, employee training, and documented quality-control systems. The complexity becomes greater as companies expand product portfolios and source ingredients from multiple suppliers or international markets. Maintaining consistent standards across the supply chain is essential for protecting brand reputation and consumer confidence. Companies that fail to manage cross-contact risks may face recalls, regulatory action, reputational damage, and loss of customer loyalty.
Gluten-free food launches in North America
- Cheez-It Original Gluten Free Crackers – 2026: Cheez-It launched its first-ever Original Gluten Free crackers in January 2026, with nationwide U.S. retail availability beginning in February.
- Nature’s Path Love Crunch Gluten Free Strawberry Cheesecake – 2026: Nature’s Path introduced a gluten-free Strawberry Cheesecake variant to its organic Love Crunch granola portfolio in January 2026.
- Eshbal Gluten-Free Pita Bread – 2026: Eshbal Functional Foods completed its first North American production run of its signature gluten-free pita in partnership with Queen Street Bakery, supporting local Canadian production.
- Bob’s Red Mill Gluten Free 1-to-1 Baking Flour – 2026: Bob’s Red Mill expanded its gluten-free baking portfolio with a redesigned Gluten Free 1-to-1 Baking Flour, positioned for easy substitution in non-yeast recipes.
- Tate’s Bake Shop Gluten Free Double Chocolate Chip Cookies – 2026: Tate’s introduced its Gluten Free Double Chocolate Chip flavor as part of a two-product gluten-free cookie expansion.
- Tate’s Bake Shop Gluten Free Oatmeal Raisin Cookies – 2026: Alongside the chocolate chip variant, Tate’s launched Gluten Free Oatmeal Raisin cookies, expanding its presence in the U.S. gluten-free cookie segment.
- Kroma Super Ramen – 2024: Kroma introduced Super Ramen, described as a gluten-free bone-broth ramen made with mung-bean noodles, providing 15 grams of protein per serving.
- Tirlán Truly Gluten Free Oat Drinks – 2024: Tirlán launched its Truly Gluten Free oat drinks in the U.S., including classic and barista variants made with Irish gluten-free oats.
- Gluten Free Easy Retail Frozen Dough Line – 2023: Brooklyn-based Gluten Free Easy expanded from direct-to-consumer sales into retail with gluten-free puff pastry, pita dough, and pizza dough products.
- SOLENZI Organic Artisan Gluten-Free Pasta – 2023: Canadian brand SOLENZI entered the U.S. Northeast market with organic artisan gluten-free pasta containing up to 26 grams of plant-based protein, alongside vegan sauces and antipasti.
Strong Consumer Demand for Gluten-Free Bakery Products
The North America gluten-free bakery market is expanding as consumers increasingly seek bread, cakes, cookies, pastries, muffins, and other baked products that meet gluten-free dietary requirements. Bakery products accounted for approximately 35% of North America’s gluten-free food and beverage market revenue in 2025, making the category one of the largest product segments. Demand is supported by increasing awareness of celiac disease, gluten sensitivity, digestive health, and allergen-free diets. Manufacturers are improving product texture, taste, shelf life, and nutritional value through formulations based on rice flour, almond flour, sorghum, tapioca, corn, and other alternative ingredients. Bread remains particularly important because it is a staple food in North American households.
Rising Demand for Gluten-Free Dairy and Dairy-Based Products
The North America gluten-free dairy food market is benefiting from growing consumer interest in specialized, allergen-friendly, and convenient food products. Gluten-free dairy products include milk, yogurt, cheese, cream, butter, flavored dairy beverages, desserts, and other processed dairy foods formulated or labeled to meet gluten-free requirements. Demand is being supported by consumers managing gluten sensitivity while continuing to seek familiar dairy-based foods. Manufacturers are also introducing products with additional attributes such as high protein, low sugar, organic positioning, lactose-free formulations, and clean-label ingredients. At the same time, plant-based dairy substitutes made from almond, oat, coconut, and other ingredients are creating opportunities for products that combine gluten-free and dairy-free positioning. The increasing presence of gluten-free dairy products across supermarkets, hypermarkets, convenience stores, and online retailers is improving accessibility and supporting category expansion throughout the United States and Canada.
Growing Use of Pulses as Nutritious Gluten-Free Ingredients
The North America gluten-free pulses food market is gaining importance as consumers increasingly seek plant-based, protein-rich, fiber-rich, and naturally gluten-free ingredients. Pulses such as chickpeas, lentils, peas, beans, and other legumes can be incorporated into gluten-free pasta, snacks, bakery products, crackers, flour blends, ready-to-eat meals, and meat alternatives. Pulses are particularly attractive because they can improve the nutritional profile of gluten-free products by providing protein, dietary fiber, vitamins, and minerals. Manufacturers are increasingly using chickpea flour, lentil flour, pea protein, and other pulse-derived ingredients to replace conventional wheat-based components. Rising interest in vegetarian, vegan, flexitarian, clean-label, and high-protein diets is further strengthening demand. Innovation in pulse-based pasta, snacks, baked foods, and meat substitutes is expanding applications, while mainstream supermarket distribution is helping move pulse-based gluten-free products from specialty categories toward everyday consumption.
Supermarkets and Hypermarkets Remain the Primary Distribution Channel
Conventional stores represent the dominant distribution channel for gluten-free foods in North America because they provide consumers with convenient access to a broad selection of mainstream and specialty products. Conventional stores include supermarkets, hypermarkets, mass retailers, grocery stores, and major online retail platforms in 2025. Large retailers are increasingly allocating dedicated shelf space to gluten-free bread, bakery products, snacks, pasta, cereals, dairy products, frozen meals, and beverages. This wider availability has helped normalize gluten-free products beyond consumers with medically required diets. Private-label products are also contributing to category growth by providing more affordable alternatives to premium branded products. In addition, supermarkets are increasingly combining physical-store availability with e-commerce ordering and home delivery, allowing consumers to purchase specialized gluten-free products conveniently. Strong retail penetration is therefore expected to remain a major factor supporting the North American gluten-free food market.
United States Mature Market Supported by Strong Consumer Awareness and Product Innovation
United States gluten-free food market represents a mature and highly developed segment of the North American food industry, supported by strong consumer awareness, extensive product availability, and continuous innovation. Demand is driven by consumers managing celiac disease and gluten sensitivity as well as those adopting health-focused, plant-based, organic, and clean-label dietary patterns. The market covers a wide range of categories, including bakery products, snacks, cereals, pasta, beverages, frozen foods, and prepared meals. Manufacturers are increasingly focusing on improved taste, texture, convenience, nutritional value, and ingredient transparency to attract both medically required and lifestyle-oriented consumers. The increasing popularity of vegetarian, vegan, and organic lifestyles is creating additional opportunities for gluten-free food manufacturers in the United States. According to a May 2024 analysis by Awesome Health, approximately 88 million people globally and 9.7 million people in the United States identify as vegan or vegetarian. This expanding consumer base is encouraging manufacturers to combine gluten-free positioning with plant-based proteins, organic ingredients, and minimally processed formulations. Products made from ingredients such as chickpeas, peas, quinoa, rice, almonds, oats, and other plant-based sources are gaining attention. Retailers are also expanding dedicated gluten-free and plant-based sections, while e-commerce platforms provide access to specialized products that may not be available in conventional stores. The convergence of gluten-free, organic, vegan, and clean-label trends is therefore broadening the U.S. consumer base and supporting continued market development.
Growing Canada Demand for Specialized and Health-Oriented Food Products
Canada gluten-free food market is expanding as consumers become increasingly attentive to dietary health, food sensitivities, ingredient quality, and nutritional well-being. Demand extends beyond consumers with medically diagnosed gluten-related conditions to include individuals pursuing specialized, plant-based, organic, and wellness-oriented diets. Canadian manufacturers and food brands are responding by expanding gluten-free product portfolios across bakery products, snacks, cereals, beverages, dairy alternatives, frozen foods, and ready-to-eat meals. A well-developed grocery and retail infrastructure provides consumers with broad access to both domestic and international gluten-free brands. Increasing attention to ingredient transparency, nutritional composition, sustainability, and product certifications is also influencing purchasing decisions. Online retail has further improved accessibility, particularly for specialty products and emerging brands. Plant-based beverages are an important area of innovation within Canada’s gluten-free food industry. In March 2024, Montreal-based Natura launched a line of organic gluten-free oat beverages made from Canadian oats, initially offering Original, Vanilla, and Chocolate varieties. The products were introduced through Canadian retailers and online channels, demonstrating how manufacturers are combining gluten-free, organic, plant-based, and Canadian-origin positioning. Natura’s current portfolio has expanded to include additional oat formats such as Oat Simple and Barista Premium. The company describes its oat beverages as certified organic and gluten-free and made from oats sourced from the Canadian Prairies. This type of product innovation illustrates the growing convergence between gluten-free and plant-based consumption in Canada. Consumers increasingly expect specialized dietary products to provide not only gluten-free credentials but also nutritional value, sustainability, convenience, and appealing taste, creating opportunities for further innovation in beverages and other food categories.
Increasing Awareness of Health and Specialized Dietary Products in Mexico
Mexico gluten-free food market is gradually expanding as consumers become more aware of nutrition, food sensitivities, wellness, and specialized dietary requirements. Exposure to international food trends, urbanization, changing lifestyles, and growing interest in healthier eating patterns is encouraging demand for gluten-free alternatives. The market includes bakery products, snacks, cereals, beverages, pasta, prepared foods, and products formulated using naturally gluten-free grains and plant-based ingredients. Urban consumers and younger demographics are increasingly interested in products positioned around health, natural ingredients, protein, fiber, and clean-label characteristics. Retailers are consequently expanding the availability of imported and locally manufactured gluten-free products, particularly through supermarkets, specialty retailers, and e-commerce platforms. However, affordability and consumer awareness remain important considerations for market development. Manufacturers that can combine competitive pricing with attractive nutritional profiles, local ingredients, convenient formats, and clear labeling are likely to gain stronger acceptance as Mexico’s specialized food market develops. Mexico has a strong opportunity to differentiate its gluten-free food industry through the use of traditional and nutrient-dense ingredients such as amaranth, chia, quinoa, and other ancient grains and seeds. These ingredients can be incorporated into gluten-free bakery products, cereals, snacks, flour blends, protein products, and functional foods while providing protein, fiber, minerals, and other nutrients. Amaranth is particularly significant because of its cultural heritage and nutritional characteristics. In 2024, Mexico was selected as a demonstration country under the FAO’s One Country, One Priority Product (OCOP) initiative, with amaranth identified as its priority product. By 2025, Mexico had strengthened implementation of the initiative, with more than 280 producers participating across five states and five state-level amaranth committees established. The initiative emphasizes sustainable production, value-chain development, research, and improved market opportunities. This focus can support the development of locally sourced gluten-free foods while strengthening connections between farmers, food processors, retailers, and consumers. The combination of traditional ingredients and modern gluten-free formulations provides Mexico with an opportunity to build differentiated products for both domestic and international markets.
Recent Developments in North America Gluten Free Food Market
- Sorghum, a nutrient-dense, gluten-free grain, was added to Gerber's Puffs and Teether Wheels mix in April 2026. The action is in line with the growing demand for baby foods that are allergy-friendly and clean-label trends.
- Chocolate Chip Instant Oatmeal Packets and Chocolate Hazelnut Overnight Protein Oats were added to Bob's Red Mill's oat line in February 2026. The introduction capitalizes on trends for decadent, high-protein breakfasts while bolstering its line of gluten-free and non-GMO instant oatmeal.
- General Mills introduced a variety of new granola snacks and cereals in January 2026, with an emphasis on flavorful and protein-enriched products. Additionally, the brand leveraged nostalgia and health-conscious innovation to relaunch two formerly well-liked flavors.
North America Gluten Free Food Market Segments
Product Type
- Bakery
- Confectionery
- Snacks
- Beverages
- Dairy Products
- Ready Meals
- Baby Food
- Others
Form
- Liquid Form
- Solid Form
Sources
- Animal Sources
- Dairy
- Meat
Plant Sources
- Pulses
- Oilseed
- Rice
- Corn
- Others
Distribution Channel
- Conventional stores
- Hotels & restaurants
- Educational institutes
- E-retailers
- Specialty services
- Hospitals & drug stores
Countries
- United States
- Canada
- Mexico
- Rest of North America
Companies have been covered from 5 viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Conagra Brands, Inc.
- The Hain Celestial Group Inc.
- General Mills Inc.
- Kellogg co.
- The kraft Heinz co.
- DuPont de Nemours, Inc.
- PepsiCo Inc.
- Dawn Food Products, Inc.
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Product Type, Form, Source, Distribution Channel and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.