Europe Plant-Based Meat Market Report by Source, Meat Type, Product Type, Distribution Channel, Storage, Countries and Companies Analysis 2026-2034
Buy NowEurope Plant-Based Meat Market Size & Forecast
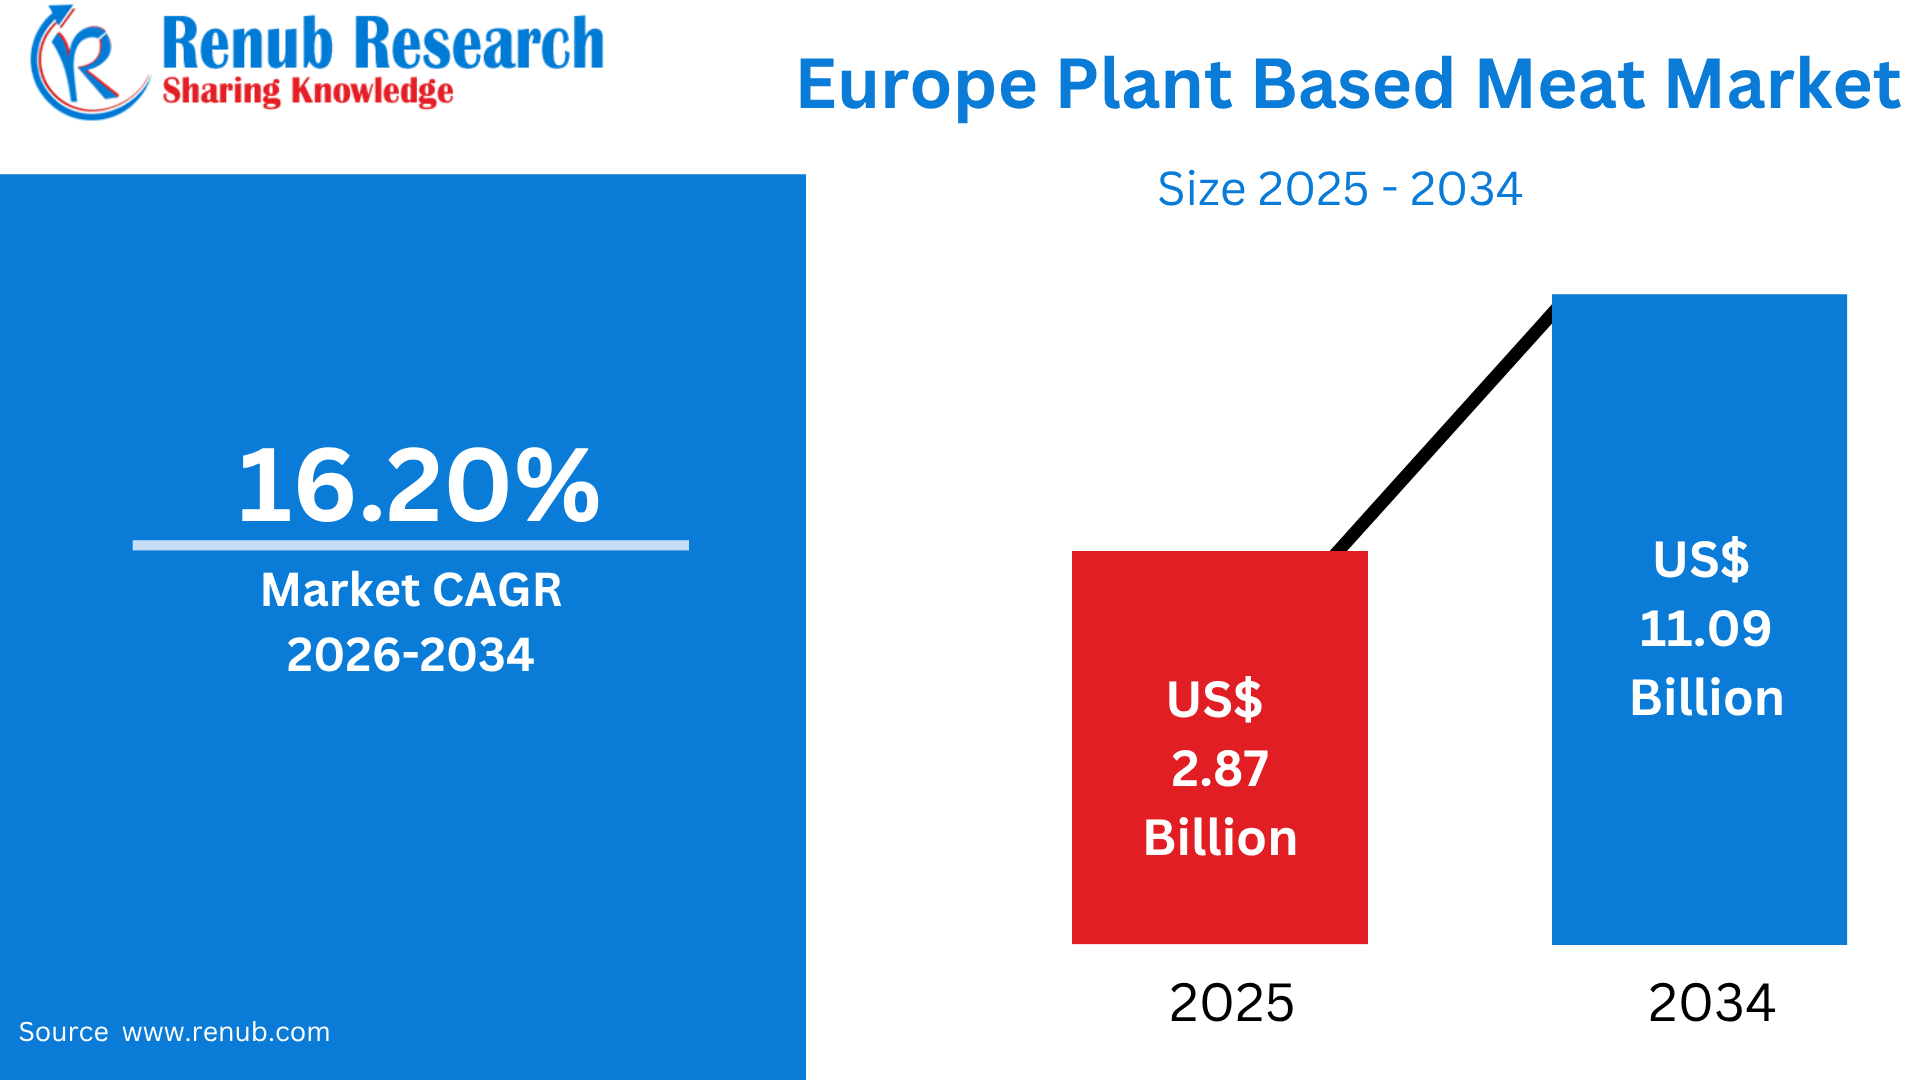
European plant-based meat market is expected to expand from US$ 2.87 billion in 2025 to US$ 11.09 billion by 2034, registering a CAGR of 16.20% during 2026–2034. This substantial growth is supported by increasing consumer demand for sustainable, nutritious, and animal-free meat alternatives, along with greater awareness of animal welfare and environmental concerns. The growing adoption of vegan and flexitarian lifestyles is also strengthening market demand across Europe.
What is Plant-Based Meat and its Uses & Popularity in Europe
Plant-based meat refers to food products made primarily from plant-derived ingredients such as soy, peas, wheat, beans, lentils, mushrooms, and other plant proteins, designed to replicate the taste, texture, appearance, and cooking characteristics of conventional meat. Products include plant-based burgers, sausages, mince, nuggets, meatballs, and ready-to-cook alternatives. In Europe, these products are increasingly consumed by vegans, vegetarians, and flexitarian consumers seeking to reduce their intake of animal-based meat without eliminating familiar foods.
People use plant-based meat in household cooking, restaurants, fast-food outlets, ready meals, sandwiches, and foodservice applications. Its popularity is supported by growing interest in health, animal welfare, environmental sustainability, and dietary diversification. GFI Europe reported that 51% of consumers across 10 European countries had reduced their meat consumption in 2023, while 27% identified as flexitarian. Germany and the UK are particularly important markets, with 32% of households in each country purchasing plant-based meat at least once in 2024.
United Kingdom Vegan Key Facts & Figures
- At the end of 2025, around 14% of the UK population followed a meat-free diet, equivalent to approximately 7.7 million people.
- The proportion of people following meat-free diets increased from 12% in 2024, compared with approximately 7.2 million people at the beginning of 2023, highlighting sustained growth.
- Vegetarians account for approximately 5.5% of UK adults, representing around 3 million people.
- Approximately 3.1% of UK adults identify as vegan, corresponding to an estimated 1.7–2.5 million people.
- Around 3 million UK consumers are pescetarian, meaning they eat fish but avoid other types of meat.
- Approximately 27% of British consumers are either currently meat-free or considering adopting a meat-free diet in 2026.
- Among younger consumers, 41% of Gen Z and 32% of millennials indicate an intention to follow a meat-free diet in 2026.
- The UK represents the largest meat-free market in Europe, with dedicated meat-free products valued at approximately £437 million.
- Vegan food orders at UK quick-service restaurants (QSRs) rose by 56% in 2024, according to Restroworks and UKHospitality data.
- During the same period, vegetarian orders at UK QSRs increased by 64%, demonstrating growing demand for meat-free choices in foodservice.
- Veganuary attracted 25.8 million participants globally in January 2025, representing a 35% increase from 2024. More than 1,000 restaurants and brands introduced vegan menus during the campaign.
- According to Mintel, approximately 49% of British consumers are reducing their meat consumption or have eliminated meat from their diets entirely.
- Animal welfare is a major motivation for UK vegan consumers, cited by approximately 70%, followed by environmental concerns at 53% and personal health at 27%.
- The global vegan food market was valued at approximately US$16 billion in 2021 and was projected to surpass US$24 billion by 2026, reflecting expanding worldwide demand for plant-based foods.
- Across consumer motivations, animal welfare ranks highest at 57%, followed by health at 52% and environmental considerations at 48%.
Source: Level 3 Food Hygiene Certificate.
Growth Drivers of the Europe Plant-Based Meat Market
Rising Adoption of Flexitarian and Meat-Reducing Diets
The growing adoption of flexitarian and meat-reduction diets is a major factor supporting the European plant-based meat market. Consumers increasingly seek to reduce conventional meat consumption while retaining meat-like foods in their diets, creating demand for burgers, sausages, mince, nuggets, and other plant-based alternatives. GFI Europe reported that 27% of consumers across 10 European countries identified as flexitarian in 2023, while 5% were vegetarian and 3% vegan. Furthermore, 51% of respondents said they had reduced their meat consumption compared with the previous year, compared with 46% in 2021. Health was the most frequently cited reason, at 47%, followed by animal welfare at 29% and environmental concerns at 26%. Germany and the UK demonstrate particularly strong potential: in 2024, 47% of German adults and 41% of UK adults reported either actively reducing meat consumption or following a meatless diet. These changing dietary habits are expanding the potential customer base beyond traditional vegan and vegetarian consumers.
Growing Focus on Health, Sustainability, and Animal Welfare
Increasing consumer awareness of health, environmental sustainability, and animal welfare is encouraging European shoppers to explore alternatives to conventional meat. Plant-based meat provides consumers with an option to diversify protein sources while reducing reliance on animal-derived products. According to GFI Europe, 47% of European meat reducers cited health as a motivation, while animal welfare and environmental concerns were cited by 29% and 26%, respectively. The market is also benefiting from broader efforts to diversify European protein consumption and develop more sustainable food systems. The European plant-based sector is increasingly moving beyond a niche vegan market toward mainstream consumers who combine plant-based and conventional foods. Circana reported that plant-based food and beverage sales across six major European markets reached €16.3 billion in 2025, representing 2.4% of total food and beverage sales. Although meat and seafood alternatives accounted for only 4% of this broader category, the figures demonstrate a substantial consumer base for plant-based products.
Product Innovation and Expanding Retail Availability
Continuous product innovation and wider retail distribution are making plant-based meat increasingly accessible to European consumers. Food manufacturers are improving the taste, texture, appearance, nutritional profile, and cooking performance of products, while supermarkets are expanding private-label and branded plant-based ranges. These developments are helping plant-based meat move from a specialist product toward an everyday food option. Germany illustrates this trend particularly well. In 2025, Germany remained Europe’s largest plant-based market, with sales across six plant-based categories reaching €1.71 billion, while 31% of German households purchased plant-based meat at least once during the year. France also recorded strong momentum: plant-based meat sales volume increased 16.8% in 2025, while its price declined 2.8%. Across Europe, manufacturers are increasingly developing products that replicate familiar meat formats, while retailers are introducing more affordable private-label alternatives. This combination of innovation, product variety, and improved accessibility is supporting wider consumer adoption and market expansion.
Challenges of the Europe Plant-Based Meat Market
High Prices and Affordability Concerns
The relatively high price of many plant-based meat products remains a significant challenge to broader adoption in Europe. Consumers increasingly compare plant-based alternatives with conventional meat, and substantial price differences can discourage regular purchasing, particularly among price-sensitive households. GFI Europe’s 2025 data shows that price remains an important determinant of plant-based food sales across major European markets. In France, plant-based meat prices declined 2.8% in 2025, while sales volume increased 16.8%, indicating a relationship between improved affordability and stronger demand. Conversely, in Germany, plant-based meat prices increased 2.0% while sales volume declined 1.7%; in the UK, prices rose 2.3% while volume fell 9.4%. Price pressures are therefore particularly important as the category attempts to reach mainstream consumers. Manufacturers face the challenge of lowering production and distribution costs while maintaining product quality, nutritional value, and appealing taste. Greater private-label availability and economies of scale may help reduce the price gap over time.
Taste, Texture, Processing Perceptions, and Consumer Acceptance
Consumer expectations regarding taste, texture, nutritional quality, and ingredient composition represent another challenge for the European plant-based meat market. Although product technology has improved significantly, some consumers remain reluctant to switch from conventional meat if plant-based alternatives do not sufficiently replicate familiar eating experiences. Recent European retail data highlights the importance of product performance. GFI Europe reported that taste and price are key factors determining success across European plant-based markets. In 2025, France recorded strong plant-based meat volume growth of 16.8%, alongside a 2.8% price reduction, while several other markets experienced volume declines. Consumer perceptions about highly processed ingredients can also influence purchasing decisions. GFI Europe noted that growing sales of tofu, tempeh, and seitan in Germany and the Netherlands may reflect consumer concerns about processing. Consequently, manufacturers must balance meat-like taste and texture with recognizable ingredients, attractive nutritional profiles, clear labeling, and competitive prices. EU food-labeling rules also require prepacked foods to provide ingredient, allergen, nutrition, and other mandatory information, increasing the importance of transparent product communication.
Plant-Based Meat Product Launches in Europe
1.Aoste Better Balance Range – France (March 2024)
- Aoste launched its Better Balance plant-based range.
- Products include burgers, sausages, breaded cutlets, and plant-based chunks.
- Formulated with soy, peas, wheat, and vegetable oils.
- Available through retail and foodservice channels.
2.Redefine Meat Flank Steak – Europe (July 2024)
- Redefine Meat introduced its plant-based Flank Steak.
- Expanded into retail markets including the UK, Switzerland, and the Netherlands.
- Positioned as a premium whole-cut plant-based steak.
3.Planted Fermented Steak – Switzerland/Europe (March 2024)
- Planted Foods launched planted.steak.
- Fermented whole-cut plant-based steak designed to replicate beef-like texture and flavor.
- Focuses on a clean-label ingredient profile.
4.Beyond Meat Chicken-Style Products – UK (April 2023 Expansion)
- Beyond Meat expanded its UK product portfolio.
- Products included Beyond Burger Chicken-Style, Beyond Fillet, and Beyond Nuggets.
- Distribution was expanded through major supermarket chains.
5.BENEO Meatless® Beef Bites – Europe (2024)
- BENEO introduced Meatless® Beef Bites.
- Designed as a plant-based beef alternative for food manufacturers.
- Offers meat-like texture with a simplified ingredient profile.
6.BENEO Meatless® Minced Meat – Europe (2024)
- BENEO introduced plant-based minced-meat solutions.
- Designed for applications including burgers, meatballs, and ready meals.
- Supports manufacturers seeking scalable plant-based meat formulations.
7.Redefine Beef Flank Retail Launch – UK & Switzerland (2024)
- Redefine Meat expanded its Redefine Beef Flank product from foodservice into retail.
- The product became available through European retailers, including Ocado and Coop.
- The launch strengthened the availability of premium whole-cut alternatives.
8.Planted Whole-Muscle Steak Platform – Europe (2024)
- Planted’s planted.steak launch established a new whole-muscle product platform.
- The technology is designed for premium plant-based meat cuts.
- It provides a foundation for developing additional whole-cut products for European consumers.
9.MATR Foods Clean-Label Meat Alternatives – Denmark (2024)
- Danish food-tech company MATR Foods expanded its fermented plant-based meat portfolio.
- Products emphasize clean-label formulations and fermentation technology.
- The company also secured funding to increase commercial production capacity in Europe.
10.Beyond Meat Health-Focused Burger Reformulation – Europe (2024)
- Beyond Meat rolled out a reformulated burger targeting health-conscious consumers.
- The product incorporated avocado oil and reduced saturated fat.
- A shorter ingredient list supported growing demand for simpler and more health-oriented plant-based meat products.
Complete Protein Profile and Established Consumer Acceptance
Soy protein remains an important ingredient in Europe’s plant-based meat market because it provides a complete protein containing all nine essential amino acids and offers strong functional properties for meat-alternative formulations. It is widely used in burgers, nuggets, meat-free strips, mince, and deli-style products. Soy also benefits manufacturers through its established processing infrastructure, comparatively efficient production, and ability to deliver desirable texture. According to the European Commission, EU-27 soybean production was approximately 3.2 million tonnes in 2023, demonstrating the established presence of soy within the European agricultural and food system. However, allergen considerations remain relevant because soy is one of the major allergens requiring declaration under EU food-labeling rules. Concerns about genetically modified soy and preferences for simpler ingredient lists are also encouraging some consumers and manufacturers to investigate pea, wheat, fava bean, and other proteins. Nevertheless, soy’s nutritional profile, versatility, and established supply chain continue to support its use across Europe’s plant-based meat industry.
Allergen-Friendly and High-Protein Alternative
Pea protein is gaining importance in Europe’s plant-based meat industry as manufacturers seek alternatives to soy and other conventional protein sources. Pea protein is naturally free from soy and gluten, although finished products can contain other allergens depending on the formulation and manufacturing environment. Its functional properties, including water retention, emulsification, and protein concentration, make it suitable for burgers, sausages, mince, nuggets, and meatballs. Demand is being supported by consumers seeking high-protein and recognizable plant-based ingredients. According to the European Commission, EU production of dry peas was approximately 2.4 million tonnes in 2023, providing an established agricultural base for pea-based food applications. Northern and Western European markets have been particularly receptive to pea-protein products as food manufacturers diversify their alternative-protein portfolios. Continued investment in extrusion, fermentation, and texturization technologies is improving the sensory characteristics of pea-based meat alternatives. As manufacturers focus on cleaner labels, nutritional value, and diversified protein sourcing, pea protein is positioned for continued expansion across European retail and foodservice channels.
Growing Demand for Familiar Poultry Alternatives
Plant-based chicken is becoming an increasingly visible category within Europe’s alternative-protein market as consumers look for convenient substitutes that resemble familiar poultry products. Nuggets, fillets, strips, tenders, and chicken-style burgers are among the most common formats because they can be prepared easily at home and adapted to restaurant and fast-food menus. Improvements in extrusion, plant-protein structuring, flavor systems, and coating technologies are helping manufacturers achieve more chicken-like texture and appearance. The category also benefits from the expansion of flexitarian diets, where consumers reduce rather than completely eliminate animal meat. In 2024, GFI Europe reported that 27% of consumers across 10 European countries identified as flexitarian, while 51% said they had reduced their meat consumption compared with the previous year. The UK, Germany, and Benelux countries remain important markets for alternative poultry products, supported by supermarket distribution and foodservice innovation. Restaurant chains are increasingly incorporating plant-based chicken into burgers, wraps, salads, and snack menus, creating additional consumption occasions and strengthening category visibility.
Sustainable Seafood Alternatives Gain Attention
Plant-based fish represents an emerging segment of Europe’s alternative-protein industry, addressing consumer interest in seafood alternatives while responding to concerns surrounding marine ecosystems. Products include fish-free fillets, plant-based tuna, seafood-style burgers, fish fingers, and fish cakes. Manufacturers are experimenting with ingredients such as algae, seaweed, legumes, soy, wheat, and pea protein to reproduce seafood’s texture, flavor, color, and nutritional characteristics. Environmental considerations provide an important opportunity because the European seafood industry faces ongoing sustainability challenges. The European Commission reported that EU aquaculture production reached approximately 1.1 million tonnes in 2022, while the EU remains a major seafood market dependent partly on imports. Plant-based seafood can therefore provide an additional option for consumers seeking to diversify their protein sources. Scandinavian countries and the Netherlands have strong sustainability-oriented food cultures, creating opportunities for category development. However, manufacturers must improve the sensory characteristics and nutritional functionality of products, particularly the ability to replicate seafood texture and provide nutrients such as omega-3 fatty acids.
Traditional Sausage Culture Supports Product Innovation
Plant-based sausages have established a significant position within Europe’s meat-alternative category because sausages are deeply embedded in the region’s food culture. Manufacturers develop products inspired by traditional varieties such as German bratwurst, Spanish chorizo, Italian-style sausages, and other regional recipes. Soy, pea, wheat, and other plant proteins are combined with vegetable oils, herbs, spices, and natural flavorings to reproduce the texture and taste of conventional sausages. Demand is supported by flexitarian consumers who want to reduce meat intake while continuing to eat familiar formats. Germany is particularly significant: GFI Europe reported that 31% of German households purchased plant-based meat at least once in 2025. Supermarkets, discount retailers, restaurants, and foodservice operators are expanding their offerings, while seasonal grilling occasions create additional demand. Product developers are increasingly focusing on protein content, reduced saturated fat, recognizable ingredients, and improved cooking performance. Continued innovation in casing technology, texture, and flavor is expected to broaden consumer acceptance of plant-based sausages across European markets.
Versatile Format for Everyday Cooking
Plant-based ground meat is gaining popularity in Europe because of its flexibility across numerous recipes and cuisines. Products can be used in pasta sauces, lasagna, tacos, meatballs, burgers, stuffed vegetables, casseroles, and ready meals, allowing consumers to replace conventional minced meat without substantially changing familiar recipes. Soy and pea proteins are commonly used because they provide suitable protein content and textural characteristics. Convenience is another important driver, particularly among urban consumers seeking quick meal preparation. The category also benefits from growing availability in chilled and frozen formats, as well as increasing incorporation into ready-to-eat and ready-to-cook meals. GFI Europe’s European retail data indicates that plant-based meat remains a meaningful component of the broader plant-based food category, although performance differs considerably between countries. Manufacturers are therefore focusing on improved flavor, texture, affordability, and nutritional composition. Partnerships between plant-based brands, meal-kit companies, restaurants, and retailers are creating additional consumption occasions. The versatility of minced formats makes them particularly suitable for mainstream consumers who are reducing meat without adopting exclusively vegan diets.
Supermarkets Remain a Major Distribution Channel
Food retail continues to be a crucial channel for distributing plant-based meat products across Europe. Supermarkets, hypermarkets, discounters, and convenience stores have expanded their ranges through branded products and private-label alternatives, increasing accessibility for mainstream consumers. Greater shelf visibility, promotional campaigns, product placement alongside conventional meat, and expanding chilled and frozen selections have helped normalize plant-based products. According to GFI Europe, 31% of German households purchased plant-based meat in 2025, demonstrating substantial household penetration in one of Europe’s largest markets. France also recorded notable momentum, with plant-based meat sales volume increasing 16.8% in 2025, while prices declined 2.8%. Retailers are increasingly competing on affordability as consumers become more price-sensitive. Private-label products can support category expansion by offering lower-priced alternatives, while premium brands differentiate themselves through ingredients, protein content, taste, and sustainability claims. Continued expansion of retail distribution is expected to remain important because convenient physical availability directly affects trial and repeat purchasing among flexitarian consumers.
Digital Grocery Expands Product Accessibility
E-commerce is becoming an increasingly important channel for European plant-based meat brands, particularly for products targeting niche dietary preferences. Online supermarkets, specialist vegan retailers, direct-to-consumer websites, and food-delivery platforms enable consumers to access a broader selection than may be available in local stores. Digital channels are particularly useful for smaller brands because they can reach customers without requiring extensive physical retail distribution. Online shopping also allows consumers to compare nutritional information, ingredients, prices, and product reviews before purchasing. The expansion of digital grocery services following the COVID-19 pandemic further strengthened online food purchasing habits across Europe. Germany, the UK, and the Netherlands are among the markets where consumers have access to well-developed online grocery and specialist food platforms. Subscription services can also encourage repeat purchases of refrigerated and frozen plant-based products. However, logistics remain important because temperature-controlled transportation can increase distribution costs. As European consumers increasingly combine physical and digital grocery shopping, e-commerce is expected to complement supermarket distribution and provide plant-based brands with additional opportunities for market penetration.
Convenience and Extended Shelf Life Drive Demand
Frozen plant-based meat products are attracting European consumers because they offer convenience, longer storage life, and flexible meal preparation. Common products include frozen burgers, nuggets, sausages, meatballs, fillets, and other ready-to-cook alternatives. Frozen formats are particularly useful for households that want to keep plant-based products available without purchasing them frequently. Advances in freezing and formulation technologies have also helped manufacturers preserve texture, flavor, and cooking performance during storage. The format is gaining attention from both retail consumers and foodservice operators, where frozen products can simplify inventory management and preparation. Price remains an important consideration, and frozen products can provide manufacturers with opportunities to reduce food waste and improve distribution efficiency. Europe’s expanding flexitarian population is creating additional demand for convenient alternatives that can be incorporated into familiar meals. Retailers are consequently increasing freezer space and introducing more private-label options. As manufacturers continue to improve sensory quality and affordability, frozen plant-based meat products can support broader adoption among consumers who prioritize convenience alongside sustainability and dietary diversification.
France Health, Sustainability, and Product Innovation Support Expansion
France’s plant-based meat market is developing as consumers increasingly consider health, environmental sustainability, animal welfare, and dietary diversification. Although traditional French cuisine has historically featured substantial animal-based foods, younger consumers and flexitarians are increasingly exploring meat alternatives. French shoppers often show interest in premium quality, taste, organic ingredients, clean-label formulations, and locally sourced raw materials. Retail supermarkets and specialist stores are expanding plant-based ranges, particularly in larger urban centers. GFI Europe reported that plant-based meat sales volume in France increased 16.8% in 2025, while prices declined 2.8%, indicating stronger demand alongside improved affordability. In March 2024, French charcuterie company Aoste expanded into plant-based products through its Better Balance range, comprising burgers, sausages, breaded products, and plant-based chunks formulated with soy, peas, wheat, and vegetable oils. The products were developed without palm oil and distributed through retail and foodservice channels. Such launches demonstrate how established food companies are entering the alternative-protein segment and contributing to greater product variety and consumer awareness in France.
Germany Strong Consumer Base and Expanding Production Capacity
Germany is one of Europe’s most important plant-based meat markets, supported by substantial demand from vegetarians, vegans, flexitarians, and meat-reducing consumers. Health, sustainability, animal welfare, and dietary diversification are among the factors supporting market development. Retailers have significantly expanded plant-based ranges, while German food manufacturers and international brands continue to introduce burgers, sausages, mince, nuggets, and other alternatives. GFI Europe reported that Germany’s plant-based food market across six categories reached €1.71 billion in sales in 2025, while 31% of German households purchased plant-based meat during the year. Manufacturing investment is also supporting the country’s role in European alternative-protein production. In September 2024, Swiss food-tech company Planted announced plans for a new production facility in Memmingen, Bavaria, its largest export market. The proposed site was intended to increase production capacity for plant-based meat products and support regional expansion. Germany’s combination of consumer demand, developed retail infrastructure, food-tech innovation, and manufacturing investment continues to make it a significant European market for plant-based meat.
UK Mature Retail Market and Strong Foodservice Demand
United Kingdom has developed into a major European market for plant-based meat, supported by widespread consumer awareness, established retail distribution, and a sizeable population of vegans, vegetarians, and flexitarians. Supermarkets have expanded branded and private-label ranges, while restaurants and quick-service chains increasingly provide plant-based choices. GFI Europe data indicates that 32% of UK households purchased plant-based meat in 2024, demonstrating substantial household penetration. Consumer interest is further supported by initiatives such as Veganuary and growing awareness of environmental and animal-welfare issues. In April 2023, Beyond Meat expanded its UK offering with plant-based poultry alternatives, including chicken-style burgers, fillets, and nuggets, increasing the availability of meat-free chicken products through major retail channels. Foodservice is another important opportunity, particularly as consumers seek convenient plant-based versions of familiar fast-food products. The UK market is also characterized by strong competition among international brands, domestic manufacturers, retailers, and foodservice operators. Continued product innovation, competitive pricing, and improvements in taste and texture are likely to remain important factors shaping future category development.
Europe Plant-Based Meat Market Segments
Source
- Soy
- Pea
- Wheat
- Others
Meat Type
- Chicken
- Pork
- Beef
- Fish
- Others
Product Type
- Burger and Patties
- Sausages
- Nuggets and Strips
- Ground Meat
- Meatballs
- Others
Distribution Channel
- Food Retail
- Food Service
- E-Commerce
Storage
- Refrigerated Plant Based
- Frozen Plant Based
- Shelf Stable Plant Based
Countries
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Russia
- Poland
- Greece
- Norway
- Romania
- Portugal
- Rest of Europe
Companies have been covered from 5 viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Hormel Foods Corporation
- Beyond Meat Inc.
- Danone S.A.
- Taifun-Tofu GmbH
- Kellanava
- Berief Food GmbH
- Archer Daniels Midland
- Tyson Foods Inc.
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Source, Meat Type, Product Type, Distribution Channel Storage and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.