Energy Drinks Market Report by Type, Product, Packaging, End User, Gender, Distribution Channel, Countries and Companies Analysis 2026-2034
Buy NowEnergy Drinks Market Size and Forecast
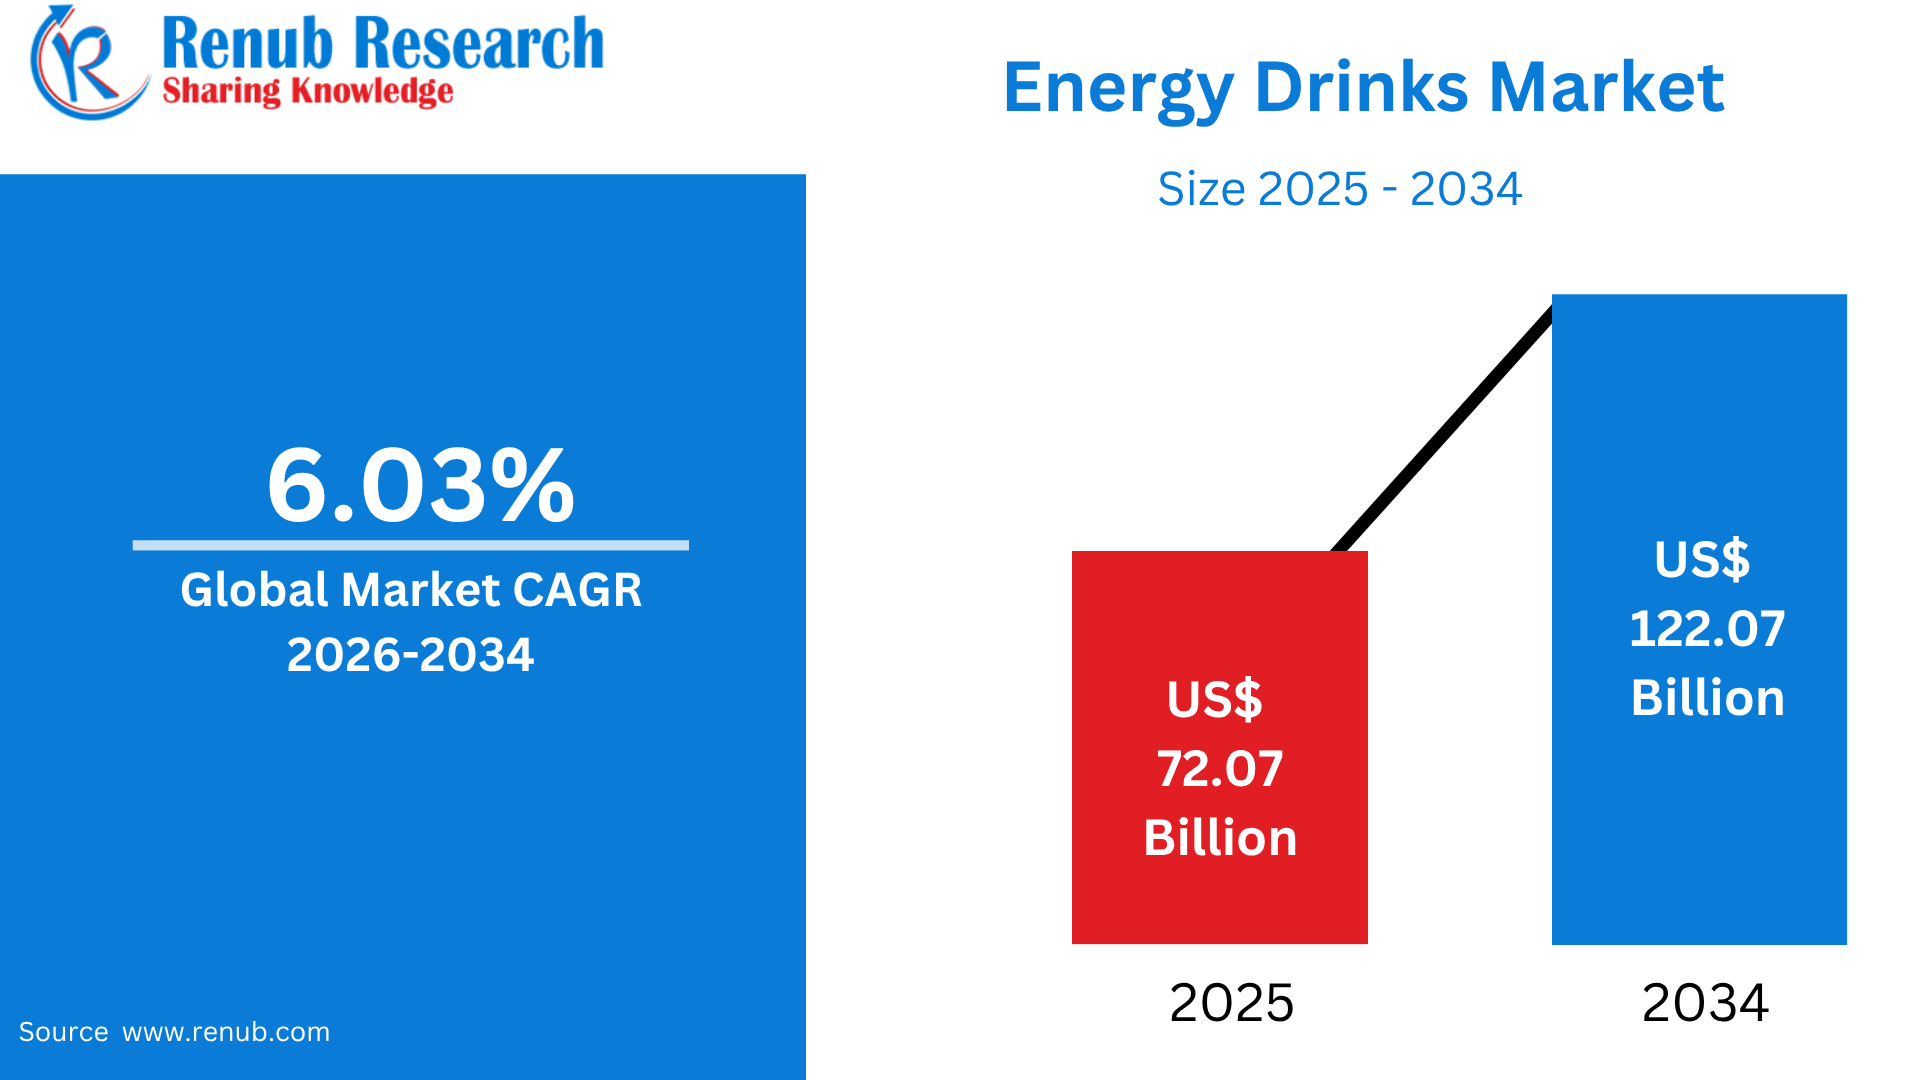
Energy Drinks Market is projected to reach US$ 122.07 billion by 2034, rising from US$ 72.07 billion in 2025, at a CAGR of 6.03% during 2026–2034. The market is expected to maintain steady expansion as consumers increasingly seek convenient beverages that provide energy, alertness, and performance support. Growing participation in sports and fitness activities, particularly among younger consumers and working professionals, is strengthening demand for energy drinks. In addition, the broader functional beverages market is benefiting from rising health consciousness and consumer interest in products offering benefits beyond basic hydration. Product innovation is further accelerating market development, with manufacturers introducing sugar-free, low-calorie, natural-caffeine, and functional-ingredient formulations.
What Are Energy Drinks? Uses and Popularity Worldwide
Energy drinks are functional beverages formulated to provide a temporary boost in energy, mental alertness, concentration, and physical performance. They commonly contain caffeine along with ingredients such as taurine, B vitamins, guarana, ginseng, amino acids, and sugars or alternative sweeteners. Products are available in conventional beverages, sugar-free and low-calorie variants, energy shots, and increasingly in formulations positioned around fitness, focus, and wellness. Energy drinks are widely consumed by students, working professionals, athletes, gamers, travelers, and consumers seeking convenient stimulation during demanding schedules. Their popularity has expanded globally because of busy lifestyles, increasing participation in sports and fitness, urbanization, and growing interest in functional beverages. Consumer demand is also shifting toward sugar-free, clean-label, natural-caffeine, and functional formulations, encouraging manufacturers to diversify flavors, ingredients, packaging, and product positioning.
Top 10 Countries by Energy Drinks Consumption
United States – The United States remains the world’s leading energy-drink market on a per-capita basis. Available 2022 data put consumption at approximately 28.4 liters per person, substantially above other major markets.
United Kingdom – The UK has one of Europe’s highest levels of energy-drink consumption, with approximately 12 liters per person reported in 2022. Consumption remains supported by convenience-store availability, younger consumers, sports marketing, and strong demand for zero-sugar products.
Japan – Japan is a major Asian energy-drink market, with approximately 10.5 liters per person reported in 2022. Functional beverages have strong cultural acceptance, while demand is supported by long working hours, convenience-store penetration, and interest in energy and wellness products.
Spain – Spain recorded approximately 8.8 liters per person in the available 2022 per-capita comparison, placing it among the higher-consumption countries. Energy drinks are increasingly associated with sports, nightlife, younger consumers, and convenience retail.
Germany – Germany is one of Europe’s most mature energy-drink markets and has high per-capita consumption alongside strong off-trade penetration.
South Korea – South Korea is recognized as a high-consumption Asian market, particularly among young adults and urban consumers. Energy-drink sales benefited from PC-bang/gaming channels in 2024, while changing consumer preferences are encouraging milder flavors and lower-caffeine options.
Turkey – Turkey is another country frequently identified as having relatively high per-capita energy-drink consumption.
Australia – Australia has a well-established functional and energy-beverage culture, with energy drinks widely available through supermarkets, convenience stores, petrol stations, and foodservice outlets. Statista maintains country-level per-capita energy-drink volume-sales data for 2024, placing Australia among the markets tracked for high consumption.
Canada – Canada represents another important high-consumption North American market, benefiting from strong penetration of energy drinks among young adults, athletes, students, and professionals.
Saudi Arabia – Saudi Arabia has become one of the leading energy-drink markets in the Middle East, supported by its young population, sports culture, hot climate, and widespread retail distribution.
Growth Drivers for the Energy Drinks Market
Growing Fitness Culture and Demand for Performance Beverages
The expansion of fitness, sports, and active lifestyles is a major growth driver for the global energy drinks market. Consumers increasingly seek convenient beverages that can support alertness, endurance, and perceived physical performance before or during demanding activities. Energy drinks are therefore becoming increasingly visible in gyms, sporting events, convenience stores, and fitness-oriented retail channels. Recent industry research identifies expansion of sports, fitness, and active-lifestyle culture as a crucial factor accelerating energy drink consumption. Product manufacturers are also targeting active consumers through formulations containing caffeine, electrolytes, vitamins, amino acids, and other functional ingredients. The development of energy shots and portable cans further supports consumption around workouts and outdoor activities. As health-conscious consumers increasingly combine exercise with functional nutrition, brands are positioning energy beverages as convenient tools for maintaining energy and performance throughout active routines.
Busy Lifestyles and Rising Demand for Instant Energy
Changing lifestyles, longer working hours, studying demands, commuting, and increasing screen-based activities are supporting demand for beverages that provide rapid stimulation and convenience. Energy drinks are particularly attractive because they combine portability with caffeine-based mental alertness, making them popular among working professionals, students, gamers, drivers, and consumers with demanding schedules. Recent market research highlights urbanization, longer working hours, and growing demand for mental alertness as important factors supporting global energy drink consumption. The category is also benefiting from the broader expansion of functional beverages, as consumers increasingly seek products offering benefits beyond basic refreshment. Manufacturers are responding with smaller energy shots, ready-to-drink cans, zero-sugar products, and formulations targeting focus and productivity. Expanding convenience-store, supermarket, vending, and e-commerce networks is further improving accessibility and encouraging frequent consumption across developed and emerging economies.
Product Innovation and Expansion of Sugar-Free & Functional Formulations
Continuous product innovation is strengthening the energy drinks market by allowing manufacturers to reach consumers with different dietary preferences, lifestyles, and functional requirements. Traditional high-sugar beverages are increasingly being complemented by zero-sugar, low-calorie, natural-caffeine, clean-label, vitamin-enriched, and specialty formulations. This diversification helps brands appeal to health-conscious consumers while retaining the core benefits associated with energy and alertness. Recent industry research identifies sugar reduction, clean-label positioning, natural caffeine, and diversified flavor offerings as important trends shaping market expansion. Energy drink companies are also experimenting with botanical ingredients, electrolytes, adaptogen-oriented formulations, new flavor combinations, and convenient packaging formats. These innovations enable manufacturers to premiumize products, differentiate brands, and enter new consumer segments. Increasing online retail and direct-to-consumer distribution further provide companies with opportunities to launch niche products rapidly across international markets.
Challenges in the Energy Drinks Market
Health Concerns and Regulatory Restrictions
Health concerns surrounding high caffeine and sugar consumption represent a significant challenge for the energy drinks industry. Excessive intake can raise concerns related to sleep disruption, cardiovascular effects, anxiety, and excessive sugar consumption, particularly among children and adolescents. These concerns are encouraging governments and health authorities to introduce tighter marketing, labeling, taxation, and age-related sales restrictions in some markets. For example, Kazakhstan introduced a ban on the sale of energy drinks to individuals under 21 in January 2025. WHO reported that more than 40% of school-aged children in Kazakhstan consumed energy drinks regularly, highlighting the public-health concerns surrounding youth consumption. Such regulatory actions can restrict market access, increase compliance costs, and limit advertising opportunities for manufacturers. At the same time, growing consumer awareness of sugar intake is pushing brands toward reformulation and zero-sugar alternatives. Companies must therefore balance caffeine levels, taste, functionality, and regulatory requirements while maintaining consumer acceptance. Failure to address health concerns could increase reputational risks and encourage consumers to shift toward alternative functional beverages, coffee, tea, or lower-stimulant products.
High Competition and Changing Consumer Preferences
Intense competition and rapidly changing consumer preferences create another challenge for energy drink manufacturers. The market includes major international beverage companies as well as regional and emerging brands, creating pressure on pricing, advertising, product differentiation, shelf visibility, and innovation. Leading companies such as Red Bull, Monster Beverage, PepsiCo, The Coca-Cola Company, and Lucozade Ribena Suntory compete across multiple markets and product categories. Consumer preferences are also moving beyond traditional high-sugar energy drinks toward sugar-free, natural, functional, and wellness-oriented beverages. This transition requires companies to continually invest in research, reformulation, packaging, flavors, and marketing. The challenge is particularly important because functional beverage consumers have a growing range of alternatives, including sports drinks, enhanced waters, coffee-based products, nutraceutical beverages, and energy shots. Moreover, premium functional formulations can increase manufacturing and ingredient costs, potentially affecting affordability. Companies must therefore maintain competitive pricing while investing in innovation and brand building. Successfully responding to evolving consumer expectations will be essential for protecting market share and sustaining long-term growth.
Energy Drinks Launches Worldwide
- Celsius Fruit-Forward Flavors – UK & Ireland, 2026: Celsius introduced four zero-sugar flavors—Sparkling Raspberry Peach, Sparkling Mango Lemonade, Sparkling Kiwi Guava, and Sparkling Strawberry Watermelon—to the UK and Ireland as part of its international expansion.
- Monster Energy Ultra Violet – Hong Kong & Taiwan, 2026: Monster launched its Ultra Violet Grape zero-sugar variant in Hong Kong and Taiwan, responding to growing demand for lower-sugar and lower-calorie energy beverages.
- Monster Energy Strawberry Shot – Worldwide Markets, 2025: Monster added Strawberry Shot to its portfolio, including a zero-sugar version, expanding its range of compact, fruit-flavored energy products.
- Monster Energy Ultra Punk Punch – United States, 2025: Monster introduced Ultra Punk Punch, a zero-sugar flavor that was initially offered through Circle K stores before broader availability.
- Monster Energy Lando Norris Zero Sugar – International Markets, 2025: Monster launched the Lando Norris Zero Sugar variant as part of its motorsport-focused product portfolio and international flavor innovation strategy.
- Monster Energy Electric Blue – International Markets, 2025: Monster expanded its portfolio with Electric Blue, adding another distinctive flavor to its global energy drink lineup.
- Red Bull Summer Edition White Peach – Global Markets, 2025: Red Bull expanded its flavored Editions portfolio with the Summer Edition White Peach, targeting consumers seeking fruit-forward energy drink flavors.
- ZOA Energy Green Apple – United States, 2024: ZOA introduced Green Apple to its zero-sugar lineup, combining B and C vitamins and electrolytes while adding a new fruit flavor to its portfolio.
- Red Bull Curuba Elderflower – Global Markets, 2024: Red Bull launched its 2024 Summer Edition Curuba Elderflower, combining curuba with elderflower and tropical fruit notes, strengthening the brand’s seasonal flavor strategy.
- Monster Energy Ultra Red White & Blue Razz – International Markets, 2025: Monster introduced Ultra Red White & Blue Razz, a zero-sugar variant designed around fruit-forward flavor preferences and the continuing expansion of its Ultra portfolio.
Strong Consumer Preference for Caffeine-Based Functional Beverages
Non-alcoholic energy drinks represent the core of the worldwide energy beverage industry, offering consumers a convenient source of caffeine, energy, and mental alertness without alcohol. The segment includes carbonated energy drinks, energy shots, sugar-free beverages, low-calorie formulations, and functional drinks enriched with vitamins, taurine, amino acids, and botanical ingredients. Their popularity is supported by increasing demand from students, working professionals, athletes, gamers, and consumers with demanding lifestyles. Growing fitness participation and the expansion of functional beverages are further encouraging consumption. Manufacturers are increasingly introducing zero-sugar, low-calorie, natural-caffeine, and plant-based formulations to attract health-conscious consumers. Convenient single-serve cans and bottles also support on-the-go consumption through supermarkets, convenience stores, gyms, vending machines, and online platforms. Rising urbanization, longer working hours, and consumer interest in quick energy solutions are expected to sustain strong demand for non-alcoholic energy drinks worldwide.
Rising Demand for Natural and Clean-Label Energy Products
Organic energy drinks are gaining popularity as consumers increasingly seek beverages made with natural, minimally processed, and organically sourced ingredients. These products generally emphasize organic caffeine sources, plant extracts, natural flavors, vitamins, and reduced use of artificial additives. Growing health awareness is encouraging consumers to examine ingredient labels, sugar content, artificial additives, and the origin of functional ingredients before purchasing beverages. Brands are responding by using green tea, yerba mate, guayusa, ginseng, coconut water, and other botanical ingredients as alternatives to conventional stimulant formulations. Organic certification and clean-label positioning also enable manufacturers to command premium prices. The segment is particularly attractive to millennials, Generation Z, fitness enthusiasts, and wellness-oriented consumers. Expansion through supermarkets, specialty retailers, natural-food stores, cafés, and e-commerce platforms is improving availability and supporting international market penetration.
Metal Cans Dominate Portable Energy Beverage Packaging
Metal cans are the leading packaging format for energy drinks because they combine portability, durability, recyclability, attractive branding, and efficient cold storage. The popularity of cans is strongly linked to single-serve consumption, particularly among commuters, students, drivers, athletes, and consumers purchasing beverages from convenience stores and vending machines. Aluminum cans are lightweight and can be transported efficiently, while their large printable surfaces provide manufacturers with substantial space for distinctive colors, graphics, nutritional information, and brand messaging. Manufacturers are also increasingly focusing on recyclable aluminum and lightweight-can technologies to reduce packaging material usage and improve sustainability credentials. Different sizes, including small energy shots and standard single-serve cans, allow brands to target different consumption occasions. Continued expansion of convenience retail, sports events, entertainment venues, and on-the-go consumption is expected to maintain strong demand for metal-packaged energy drinks worldwide.
Working Professionals and Active Adults Drive Consumption
Adults represent one of the most important consumer groups in the global energy drinks industry, supported by demanding work schedules, commuting, fitness activities, travel, and growing interest in functional beverages. The adult category includes working professionals, shift workers, drivers, athletes, fitness enthusiasts, and consumers seeking greater alertness or an energy boost during the day. Manufacturers are increasingly targeting adult consumers with products positioned around productivity, concentration, exercise performance, endurance, and convenience. Sugar-free and low-calorie products are particularly important because many adults are becoming more conscious of calorie and sugar intake. Brands are also introducing beverages containing electrolytes, B vitamins, amino acids, adaptogen-oriented ingredients, and natural caffeine to broaden their appeal. Gyms, offices, convenience stores, supermarkets, vending machines, and e-commerce platforms provide important access points. As working populations become increasingly urbanized and time-constrained, demand for convenient functional beverages is expected to remain strong.
High-Frequency Retail Channel Supports Impulse Purchases
Convenience stores are one of the most important distribution channels for energy drinks because they provide immediate product access to consumers seeking portable, ready-to-drink beverages. The convenience-store channel benefits from high-frequency shopping, extended operating hours, strategic refrigerator placement, checkout visibility, and strong demand from commuters and travelers. Single-serve cans are particularly successful in convenience retail because consumers can purchase and consume products immediately without requiring additional preparation. Fuel stations, roadside stores, urban convenience outlets, and transportation hubs further strengthen the channel’s reach. Retailers also use promotional pricing, multi-pack offers, loyalty programs, and prominent chilled displays to increase energy drink sales. The rapid introduction of new flavors, zero-sugar products, functional formulations, and limited editions creates additional shelf opportunities. Continued urbanization, rising mobility, and on-the-go consumption are expected to support the channel’s importance in global energy drink distribution.
Innovation, Convenience, and Performance Positioning Drive United States Demand
The United States energy drinks market is one of the world’s largest and most developed, supported by strong consumer demand, extensive retail availability, and continuous product innovation. Energy drinks are increasingly positioned not only as sources of physical energy but also as beverages supporting mental alertness, concentration, and performance. Young adults, working professionals, athletes, gamers, and consumers with demanding schedules represent important consumer groups. Convenience retailers remain a particularly important channel because they provide immediate access to ready-to-drink products, while e-commerce continues to expand the category’s reach. Manufacturers are increasingly introducing zero-sugar, low-calorie, natural-caffeine, and functional formulations to respond to health-conscious consumers. In addition, sports sponsorships, gaming partnerships, entertainment marketing, and influencer campaigns strengthen brand visibility. The growing emphasis on “clean caffeine” and cognitive support is creating new opportunities, although concerns regarding caffeine consumption and tighter regulation remain important market considerations. Product launches and distribution partnerships are further expanding the U.S. market. In February 2026, Mocean partnered with wholesale marketplace Faire to increase access to its functional energy drinks among independent retailers and shop owners. In October 2025, Grupo Jumex and AriZona Beverages introduced Jumex Energy, combining fruit nectar flavors with an energy formulation containing 150 mg of caffeine per serving, alongside vitamins C, B5, B6, and B12, taurine, guarana, and ginseng. These developments demonstrate the industry’s movement toward differentiated functional formulations and broader retail distribution.
Health-Conscious Consumption and Zero-Sugar Innovation Support United Kingdom Growth
The United Kingdom energy drinks market is expanding as consumers increasingly seek convenient beverages that provide energy and mental alertness while fitting busy lifestyles. Younger adults, students, working professionals, and fitness-oriented consumers remain important demand groups. Health awareness is encouraging a significant shift toward zero-sugar, reduced-calorie, and natural-ingredient formulations, prompting manufacturers to reformulate existing products and introduce new functional variants. Major brands are also using flavor innovation to maintain consumer engagement, with products such as fruit-based and specialty flavors broadening the category beyond traditional energy beverages. In 2025, Monster Energy strengthened its competitive position through multiple flavor launches, including Juiced Rio Punch, Bad Apple, and Nitro Cosmic Peach, while its zero-sugar portfolio continued to perform strongly. Supermarkets, convenience stores, vending outlets, gyms, and online retailers provide broad market access. Regulatory attention toward sugar, caffeine, labeling, and marketing—particularly to younger consumers—continues to influence product development and promotional strategies.
Urbanization, Youth Consumption, and Functional Benefits Accelerate China Expansion
China represents a major and rapidly evolving energy drinks market, supported by urbanization, rising disposable incomes, expanding functional beverage consumption, and changing lifestyles. Energy drinks are increasingly consumed during work and study, sports and fitness activities, long-distance driving, and other situations requiring sustained energy or alertness. A 2025 consumer survey found that 41.25% of consumers drank energy beverages once or twice per week, while work and study represented the leading consumption motivation at 31.21%. Red Bull remained the leading brand in the survey, with a 46.54% market share, while cans were the preferred packaging format for 38.81% of consumers. The market is also shifting toward reduced-sugar and natural-ingredient formulations as health awareness increases. E-commerce and digital marketing are strengthening product discovery and accessibility, while local brands such as Eastroc Super Drink are expanding through competitive pricing and broad distribution. Growing flavor innovation, influencer marketing, and new consumption occasions are expected to support continued market development.
Premium Consumption, Retail Expansion, and Health Trends Shape Demand in United Arab Emirates
The United Arab Emirates energy drinks market is developing steadily, supported by high purchasing power, urban lifestyles, tourism, sports activities, and strong demand for convenient functional beverages. Energy drinks are popular among young adults, working professionals, fitness enthusiasts, drivers, and consumers seeking quick energy and alertness. The market benefits from extensive availability across supermarkets, convenience stores, forecourt retailers, gyms, vending outlets, and e-commerce platforms. Forecourt retail remains particularly important because of high on-the-go consumption, while online channels are expanding product accessibility. Established international brands lead competition, with Red Bull maintaining a strong leadership position, while local and smaller brands increasingly compete through affordable pricing and vitamin-focused formulations. Health awareness is also encouraging consumers to shift toward reduced-sugar products. However, the UAE’s 100% tax on energy drinks represents an important constraint on market expansion. Manufacturers are consequently focusing on product differentiation, premium positioning, healthier formulations, and innovative marketing to sustain demand.
Recent Developments in Energy Drinks Market
- November 2025: HELL Energy Drink agreed to become the Punjab Kings' official energy drink partner for three years, beginning with the 2026 Indian Premier League. In addition to being visible through matchday hydration stations and fan marketing, the agreement displays HELL Energy Drink's logo on the rear of players' helmets and caps.
- September 2025: 28 BLACK, a high-end energy drink brand with the tagline "The day has 28 hours" and distinctive tastes. Exclusive importer Yinbev Beverages India Private Limited is in charge of the launch, which is scheduled for late 2025. Initial availability will be made through www.28black.in and collaborations with stores across the country.
- In September 2025, HELL Energy Drink introduced its Black Cherry version in India as a high-end energy drink aimed for palates. This version combines the brand's original recipe, which contains several B vitamins and no additional preservatives, with a strong black cherry flavor.
Energy Drinks Market Segments
Type
- Alcoholic
- Non-Alcoholic
Product
- Non-Organic
- Organic
- Natural
Packaging
- Plastic
- Glass
- Metal
- Others
End User
- Kids
- Adults
- Teenagers
Gender
- Women
- Man
Distribution Channel
- Convenience Stores
- Foodservice
- Mass Merchandisers
- Supermarket
- Others
Countries
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Thailand
- Malaysia
- Indonesia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Aje Group
- Red Bull
- Congo Brands
- Monster Beverage Corporation
- PepsiCo, Inc.
- National Beverage Corp
- Suntory Holdings Limited
- The Coca-Cola Company
- Campbell Soup Co.
- Amway Corporation
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Type, Product, Packaging, End User, Gender, Distribution Channel and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.