United States Active Pharmaceutical Ingredients (APIs) Market – Growth, Trends & Forecast 2026–2034
Buy NowUnited States Active Pharmaceutical Ingredients (APIs) Market Outlook and Forecast (2026–2034)
United States Active Pharmaceutical Ingredients (APIs) Market is expected to reach US$ 129.18 Billion by 2034 from US$ 73.54 Billion in 2025, with a CAGR of 6.46% from 2026 to 2034. The United States Active Pharmaceutical Ingredients Market is expected to witness sustained growth throughout the forecast period, supported by pharmaceutical innovation, biologics development, domestic manufacturing expansion, and evolving healthcare requirements.
United States Active Pharmaceutical Ingredients (APIs) Industry Landscape
Occupying a critical position within the pharmaceutical value chain, the United States Active Pharmaceutical Ingredients (APIs) Market supports the development and manufacturing of prescription medicines, over-the-counter drugs, biologics, and specialty therapeutics. Active pharmaceutical ingredients are the biologically active substances responsible for delivering the intended therapeutic effects of pharmaceutical products. The market encompasses both synthetic and biological APIs utilized across numerous therapeutic areas, including cardiovascular disorders, oncology, infectious diseases, neurology, endocrinology, respiratory diseases, and immunology. Increasing healthcare demand, continuous pharmaceutical innovation, and greater emphasis on high-quality drug manufacturing continue reinforcing the strategic importance of API production across the United States. Strong regulatory oversight and advanced manufacturing capabilities further strengthen the country's pharmaceutical ecosystem.
Scientific advancement continues transforming the API industry through innovations in process chemistry, biomanufacturing, continuous manufacturing technologies, and advanced analytical techniques. Pharmaceutical companies are investing in modern production facilities equipped with automation, digital quality monitoring, artificial intelligence, and advanced process control systems that improve manufacturing efficiency while maintaining strict regulatory compliance. Growing interest in biologics, peptide-based therapies, gene therapies, and personalized medicine has encouraged significant investment in biotechnology-based API production. Contract development and manufacturing organizations are also expanding capabilities to support pharmaceutical companies seeking flexible and efficient production solutions. These developments continue improving supply chain resilience while strengthening domestic pharmaceutical manufacturing capacity.
Looking ahead, the United States Active Pharmaceutical Ingredients Market is expected to benefit from increasing pharmaceutical research, healthcare innovation, and government initiatives supporting domestic manufacturing capabilities. Pharmaceutical companies continue diversifying supply chains, expanding manufacturing infrastructure, and strengthening research partnerships to improve production flexibility and reduce external supply dependence. Continuous innovation in biotechnology, synthetic chemistry, and precision medicine is anticipated to generate new opportunities across multiple therapeutic applications. Although regulatory compliance, production costs, and raw material availability remain ongoing considerations, technological advancement and growing pharmaceutical demand are expected to sustain long-term market development. Consequently, the API industry will continue serving as a foundational component of the United States pharmaceutical sector.
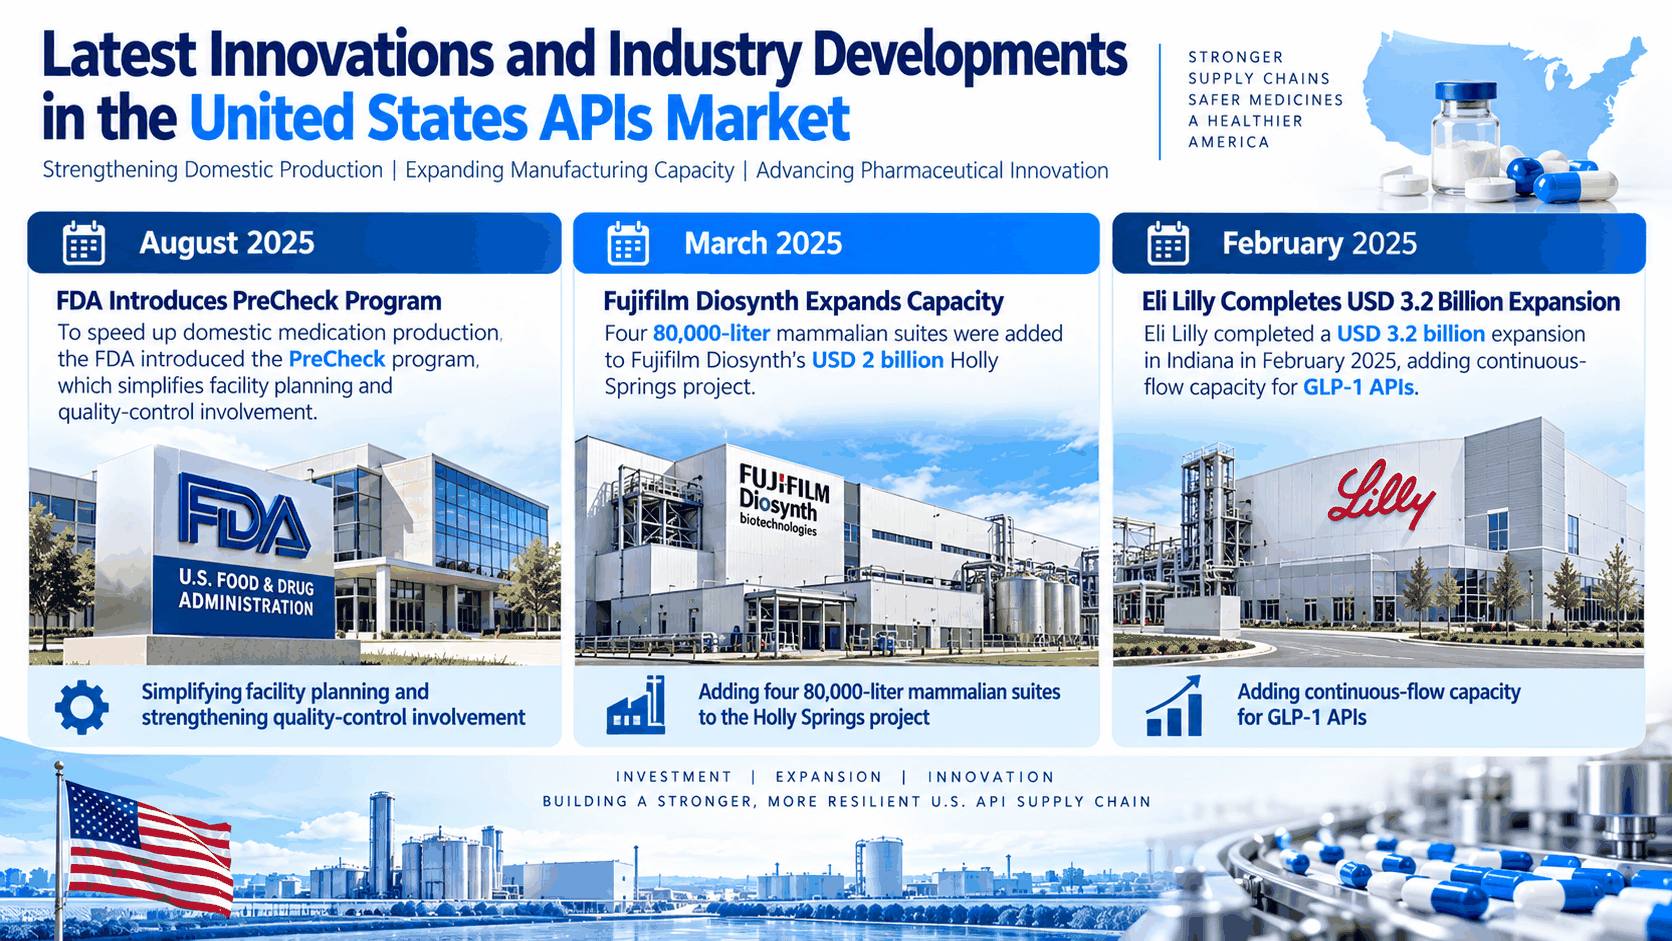
Latest Innovations and Industry Developments in the United States Active Pharmaceutical Ingredients (APIs) Market
- August 2025: To speed up domestic medication production, the FDA introduced the PreCheck program, which simplifies facility planning and quality-control involvement.
- March 2025: Four 80,000-liter mammalian suites were added to Fujifilm Diosynth's USD 2 billion Holly Springs project.
- Eli Lilly completed a USD 3.2 billion expansion in Indiana in February 2025, adding continuous-flow capacity for GLP-1 APIs.
Factors Supporting the Growth of the United States Active Pharmaceutical Ingredients (APIs) Market
Growing Interest in Generic Medications
In the US, generic pharmaceuticals are becoming more and more important because they are more affordable than branded ones. Industry research claims that generic drugs have saved the US healthcare system about USD 338 billion annually, with savings over a ten-year period estimated to be close to USD 2.4 trillion. These drugs provide more affordable treatment options while preserving the quality and efficacy of the name-brand medication, according to the US active pharmaceutical ingredients market projection.
The necessity for manufacturers to prove that their goods are just as safe and effective as their branded versions is what makes generic medications so important. As a result, the APIs used in generics need to be of the highest caliber and adhere to strict regulations. This trend emphasizes how important it is to uphold strict standards in API manufacturing in order to facilitate the growth of the generic medication market.
Increasing the Variety of US Supply-Chain Incentives for Homegrown API Production
Pharmaceutical purchasers are being compelled by the BIOSECURE Act's congressional momentum to assess their exposure to China and transfer contracts to domestic facilities. More than $100 million has been pledged by Curia, Cambrex, and Amgen to onshore capacity that was formerly located in Asia. By extending tax incentives to pharmaceutical process equipment, the CHIPS and Science Act drastically reduce reactor capital expenditures and closes the cost difference with offshore batch assets. States provide additional assistance; Massachusetts expedites GMP permits that satisfy ISO 14001 requirements, while North Carolina co-financed Amgen's USD 1 billion biologics campus. For molecules with an annual demand over 500 kilos, stacked incentives bring the total cost of ownership below offshore equivalents.
Growing Oncology Boom Demand for High-Potency APIs
In 2025, the FDA approved 18 new cancer medications, the most ever in a single year. Glove-box isolators and negative-pressure chambers, which might cost USD 50–100 million per 500-kilogram line, are necessary for high-potency APIs. In order to supply monomethyl auristatin E and duocarmycin analogs, which retail for more than $100,000 per kilogram, Curia added three OEB 5 reactors in 2025. Eli Lilly's USD 3.2 billion Indiana complex will meet the needs of its Loxo Oncology portfolio and mitigate supply risk for assets whose peak yearly revenue is expected to surpass USD 1 billion. To ensure dose consistency in oral formulations, Catalent and Patheon have implemented controlled micro-dose platforms that micronize powerful APIs to less than 10 microns.
Major Challenges Affecting the United States APIs Industry
Stringent Regulatory and Quality Compliance Requirements
API manufacturers operate under highly regulated pharmaceutical manufacturing environments requiring strict compliance with quality standards, good manufacturing practices, documentation procedures, process validation, and product traceability. Regulatory authorities require comprehensive inspections, continuous quality monitoring, and extensive testing to ensure patient safety and product consistency. Maintaining regulatory compliance requires significant investment in manufacturing technologies, quality systems, employee training, and facility modernization. Successfully meeting evolving regulatory expectations remains one of the most significant operational challenges within the United States API industry.
Raw Material Availability and Supply Chain Complexity
The production of active pharmaceutical ingredients depends upon the consistent availability of specialized chemical intermediates, biological materials, laboratory reagents, and manufacturing components. Supply chain disruptions, transportation challenges, geopolitical developments, and fluctuations in raw material availability may affect production continuity and manufacturing efficiency. Pharmaceutical companies increasingly diversify sourcing strategies, strengthen supplier partnerships, and expand domestic manufacturing capabilities to improve supply chain resilience. Managing complex global supply networks while ensuring uninterrupted pharmaceutical production remains a critical industry challenge.
California: Leading Innovation Hub for API Manufacturing
California remains one of the most significant contributors to the United States Active Pharmaceutical Ingredients Market due to its concentration of biotechnology companies, pharmaceutical manufacturers, research universities, and life sciences innovation centers. The state supports advanced API research, biologics manufacturing, precision medicine, and pharmaceutical development through strong collaboration between academic institutions and private industry. Continuous investment in biotechnology infrastructure and research capabilities further strengthens California's leadership within the national pharmaceutical manufacturing ecosystem.
Texas Active Pharmaceutical Ingredients Market Assessment
Texas continues strengthening its position within the United States API Market through expanding pharmaceutical manufacturing, biotechnology investment, and healthcare research activities. Modern manufacturing facilities, research institutions, and contract manufacturing organizations support growing demand for high-quality pharmaceutical ingredients across multiple therapeutic areas. Increasing industrial investment and favorable business conditions continue encouraging pharmaceutical production and innovation throughout the state.
New York APIs Industry Overview
New York's Active Pharmaceutical Ingredients Market benefits from world-class research institutions, pharmaceutical companies, biotechnology organizations, and advanced healthcare infrastructure. The state continues supporting innovation in drug development, biotechnology research, clinical studies, and pharmaceutical manufacturing through collaborative partnerships. Strong investment in scientific research and healthcare innovation contributes significantly to API industry development across New York.
Florida APIs Market Perspective
Florida's API Market continues expanding alongside increasing pharmaceutical demand, healthcare services, biotechnology investment, and life sciences research activities. Pharmaceutical manufacturers continue strengthening production capabilities while healthcare organizations support greater utilization of advanced medicines across diverse therapeutic applications. Continued healthcare infrastructure development contributes to sustained demand for pharmaceutical ingredients throughout the state.
Merchant APIs Market Analysis
Merchant APIs represent an important segment of the pharmaceutical industry by supplying active pharmaceutical ingredients to multiple pharmaceutical manufacturers rather than producing exclusively for internal consumption. Independent API manufacturers provide flexible production capacity, specialized expertise, and cost-efficient manufacturing solutions supporting branded pharmaceuticals, generic medicines, and contract manufacturing operations. Growing outsourcing activities continue strengthening demand for merchant API suppliers across the pharmaceutical value chain.
Biotech APIs Market Evaluation
Biotech APIs continue gaining strategic importance due to increasing demand for biologics, biosimilars, recombinant proteins, monoclonal antibodies, vaccines, and advanced therapeutic products. Biotechnology manufacturers continue investing in sophisticated bioprocessing technologies, cell culture systems, and advanced purification techniques to improve manufacturing efficiency and product quality. Scientific innovation continues driving expansion across the biotech API segment.
Generic APIs Market Outlook
Generic APIs remain essential for the production of affordable pharmaceutical products following patent expiration of branded medicines. Pharmaceutical manufacturers continue emphasizing cost-efficient production, quality assurance, regulatory compliance, and manufacturing optimization to support increasing demand for generic medicines. Growing healthcare accessibility and pharmaceutical affordability continue supporting long-term expansion of the generic API segment.
Cardiovascular Diseases APIs Market Review
Cardiovascular disease APIs represent a significant therapeutic segment due to the ongoing need for medicines treating hypertension, heart failure, arrhythmias, coronary artery disease, and related cardiovascular conditions. Pharmaceutical manufacturers continue investing in research, manufacturing quality, and process optimization to ensure consistent supply of high-quality active pharmaceutical ingredients supporting cardiovascular therapies. Continued advancement in cardiovascular medicine contributes to sustained demand for specialized APIs.
FAQs About the United States Active Pharmaceutical Ingredients Market Report
Q1: What is the projected market size and growth rate for the United States API market?
The United States active pharmaceutical ingredients (APIs) market is projected to reach US$ 129.18 billion by 2034, increasing from US$ 73.54 billion in 2025. This expansion represents a steady Compound Annual Growth Rate (CAGR) of 6.46% from 2026 to 2034, driven by domestic manufacturing expansion and pharmaceutical innovation.
Q2: What significant manufacturing facility expansions were implemented by major players in early 2025?
In February 2025, Eli Lilly finalized a USD 3.2 billion Indiana expansion adding continuous-flow capacity for GLP-1 APIs. Shortly after, in March 2025, Fujifilm Diosynth advanced its USD 2 billion Holly Springs project by integrating four massive 80,000-liter mammalian suites to boost regional biomanufacturing.
Q3: How are legislative measures like the BIOSECURE and CHIPS Acts driving domestic API onshoring?
Congressional momentum from the BIOSECURE Act pressures purchasers to exit Chinese contracts, leading firms like Curia, Cambrex, and Amgen to pledge over $100 million for domestic onshoring. Simultaneously, the CHIPS and Science Act offer critical tax incentives for pharmaceutical process equipment, significantly lowering reactor capital expenditures.
Q4: Why has the oncological boom triggered a surging demand for high-potency APIs (HPAPIs)?
Following a record-breaking 18 FDA cancer drug approvals in 2025, demand spiked for highly complex HPAPIs like monomethyl auristatin E. Manufacturing these compounds requires specialized containment infrastructure costing USD 50–100 million per line, which ensures strict dose consistency and shields operators from hazardous exposure.
Q5: What economic impact do generic medications have on the United States healthcare ecosystem?
Generic medications provide highly affordable treatment alternatives that preserve the exact quality and efficacy of brand-name products. According to industry research, generics save the United States healthcare system roughly USD 338 billion annually, with ten-year cumulative savings projected to approach a massive USD 2.4 trillion.
Research Methodology for the United States Active Pharmaceutical Ingredients (APIs) Market
1. Market Definition and Scope
The United States Active Pharmaceutical Ingredients (APIs) Market should be defined as the value of active pharmaceutical ingredients consumed, supplied, or sold for pharmaceutical manufacturing in the United States, according to the selected market boundary.
The scope should include small-molecule APIs, synthetic APIs, biological APIs, highly potent APIs, generic APIs, branded APIs, and specialty APIs, where applicable.
The market should be segmented by type, therapeutic area, drug type, manufacturing source, synthesis type, application, customer, and geography. Intermediates, excipients, finished dosage forms, and formulation services should be excluded unless specifically included in the market definition.
The analysis should clearly distinguish between API consumption in the U.S. and API manufacturing within the U.S., because imported APIs represent an important component of the domestic pharmaceutical supply chain. FDA reported that only 11% of API manufacturers for FDA-approved products were located in the U.S. in 2025.
2. Estimate the U.S. Pharmaceutical Production Base
The first step should be to establish the U.S. pharmaceutical manufacturing base.
The analysis should cover:
- Brand-name pharmaceutical manufacturers
- Generic drug manufacturers
- Specialty pharmaceutical companies
- Biopharmaceutical companies
- Contract manufacturing organizations
- API manufacturers
- Contract API manufacturers
FDA's FY2025 inspection report identified 1,951 establishments registered as API establishments, although this figure should not be treated directly as the market size because establishment registration and commercial API sales are different measures.
3. Estimate the Number of APIs Used in the United States
The number of APIs used in U.S. pharmaceutical products should be established from:
- FDA-approved drug products
- Orange Book
- Drugs@FDA
- ANDA products
- NDA products
- Biologics and biosimilars
- Active Drug Master Files
- Pharmaceutical company product portfolios
The FDA Orange Book can be searched by active ingredient and provides downloadable product data, making it useful for building an API-level database.
The API universe should then be classified into commercially significant APIs rather than simply counting every listed ingredient.
4. Estimate API Consumption Volume
The primary bottom-up calculation should estimate the quantity of each API required for pharmaceutical production.
The calculation should consider:
API Consumption = Number of Drug Units × API Quantity per Drug Unit × Manufacturing Adjustment
The manufacturing adjustment should account for:
- Production losses
- Process yield
- Formulation losses
- Batch rejection
- Inventory requirements
- Safety stock
The analysis should be performed separately for each major API and therapeutic category.
5. Estimate Pharmaceutical Product Volumes
API demand should be derived from the volume of finished pharmaceutical products manufactured or consumed in the United States.
The analysis should include:
- Prescription drugs
- Generic drugs
- Branded drugs
- Hospital pharmaceuticals
- Specialty medicines
- Injectable medicines
- Oral solid dosage forms
- Other dosage forms
For each product:
Annual API Requirement = Annual Drug Units × API Dosage per Unit
The resulting API quantities should then be aggregated across pharmaceutical products.
6. Estimate Average API Selling Price
Average selling prices should be calculated separately for individual API categories.
API ASP = API Revenue ÷ API Volume Sold
ASP should vary according to:
- API molecule
- Purity
- Manufacturing process
- Therapeutic application
- Generic versus branded use
- Production scale
- Grade
- Regulatory status
- Geographic source
- Synthetic versus biological production
- Potency and complexity
Commodity APIs should not be assigned the same price as high-value specialty or highly potent APIs.
7. Calculate the Bottom-Up Market Size
The primary market size should be calculated at the API level.
U.S. API Market = Σ (API Volume Consumed × Average Selling Price per API)
This should be calculated for major API categories and then aggregated.
Where molecule-level volume is unavailable, the market should be estimated using therapeutic-class consumption, drug-unit volume, dosage strength, and representative API pricing.
8. Estimate the Market by API Type
The market should be segmented into:
- Synthetic APIs
- Biological APIs
- Highly Potent APIs
- Generic APIs
- Specialty APIs
- Other APIs
Synthetic small-molecule APIs should be modelled separately from biologically derived active substances because production processes, capacity, pricing, and supply chains differ substantially.
9. Estimate the Market by Therapeutic Area
API demand should be allocated across major therapeutic categories, including:
- Oncology
- Cardiovascular
- Diabetes
- Central Nervous System
- Respiratory
- Anti-infective
- Gastrointestinal
- Neurology
- Immunology
- Endocrinology
- Other therapeutic areas
The allocation should be based on the number of pharmaceutical products, prescription volumes, dosage requirements, and API prices within each therapeutic area.
10. Estimate Generic and Branded API Demand
The API market should separately estimate demand generated by:
Generic Pharmaceuticals
Generic API demand should be calculated using generic drug volumes, dosage strengths, and the number of manufacturers producing each formulation.
Branded Pharmaceuticals
Branded API demand should be estimated from branded pharmaceutical production and dosage requirements.
The distinction is important because generic products generally involve different API sourcing structures, supplier competition, pricing, and manufacturing economics than innovative medicines.
11. Estimate Domestic API Production
The domestic production market should be estimated separately from overall U.S. API consumption.
Domestic API Production Value = Domestic API Production Volume × Average Domestic API Price
Manufacturing capacity should be assessed using:
- FDA-registered API establishments
- Company manufacturing facilities
- Production capacity disclosures
- Facility announcements
- Plant expansions
- FDA inspections
- Company annual reports
FDA's establishment data should be used as a supply-side validation rather than directly converted into revenue.
12. Estimate Imported API Consumption
Imported APIs should be incorporated because U.S. pharmaceutical manufacturers source APIs from international suppliers.
The supply-side framework should be:
U.S. API Consumption = Domestic Production + API Imports − API Exports ± Inventory Adjustment
Census provides detailed monthly U.S. import and export data by Harmonized System classification, including value and quantity information where available.
Relevant HS codes should be mapped carefully because some pharmaceutical chemical classifications contain APIs together with intermediates or other chemical products.
13. Validate Through API Drug Master Files
FDA Drug Master File information should be used to assess the active API supplier landscape.
The analysis should examine:
- Type II API DMFs
- DMF holders
- API manufacturers
- API suppliers
- New DMF submissions
- Active versus inactive DMFs
- Domestic versus foreign suppliers
FDA's DMF database is updated quarterly, while GDUFA reporting provides counts of Type II API DMF payments and related activity.
DMF counts should be used as an indicator of supplier activity and market breadth, not as a direct proxy for API revenue.
14. Estimate API Market by Manufacturing Source
The market should be divided into:
- Domestic Manufacturing
- Imported APIs
- Contract Manufacturing
- Captive/In-house Manufacturing
The domestic-versus-imported split should be calculated separately for major API categories because sourcing dependence can differ considerably between generic, specialty, oncology, and biological APIs.
FDA's recent analysis confirms that pharmaceutical manufacturing networks for U.S.-based applications have increasingly involved manufacturing locations outside the United States.
15. Validate Through Pharmaceutical Company Revenue
Major pharmaceutical companies should be analyzed individually.
The analysis should examine:
- API manufacturing revenue
- Captive API production
- External API purchases
- Drug production volume
- Manufacturing facilities
- Supplier agreements
- API sourcing strategy
For vertically integrated companies, only the estimated API component of pharmaceutical manufacturing should be attributed to the API market.
Finished-drug revenue should not be counted as API revenue.
16. Validate Through API Manufacturer Revenue
Major API suppliers and CDMOs should be analyzed from the supply side.
The assessment should include:
- API revenue
- U.S. revenue
- Manufacturing capacity
- Production volume
- Product portfolio
- New API facilities
- Contract manufacturing agreements
- Specialty API and HPAPI capabilities
Global supplier revenue should be allocated to the United States based on customer location, shipment destination, or estimated U.S. sales share.
17. Estimate the Market by Customer Type
The U.S. API market should be segmented by:
- Pharmaceutical Companies
- Generic Drug Manufacturers
- Biotechnology Companies
- Specialty Pharmaceutical Companies
- CDMOs/CMOs
- Research and Development Organizations
- Other Pharmaceutical Manufacturers
Captive API production should be distinguished from APIs purchased commercially from external suppliers.
18. Estimate the Market by Dosage Form
API consumption should also be allocated according to final dosage form:
- Oral Solid Dosage
- Injectables
- Oral Liquids
- Topical Products
- Inhalation Products
- Ophthalmic Products
- Other Dosage Forms
This allows the analysis to capture differences in API dosage, purity requirements, formulation losses, and manufacturing complexity.
19. Estimate the Market by API Manufacturing Process
The market should be segmented by:
- Synthetic Manufacturing
- Fermentation
- Biotechnological Production
- Extraction
- Chemical Synthesis
- Other Manufacturing Processes
The manufacturing process should be linked with production costs, yield, capacity, raw-material requirements, and API pricing.
20. Validate Through Raw Material and Manufacturing Costs
API production costs should be cross-checked using:
- Starting materials
- Key starting materials
- Solvents
- Catalysts
- Utilities
- Labor
- Manufacturing overhead
- Quality control
- Regulatory compliance
- Waste treatment
- Packaging
The cost structure can be used to test whether estimated API selling prices are commercially reasonable.
21. Estimate Regional and State-Level Markets
The U.S. API market should be allocated across major pharmaceutical manufacturing regions and states.
The analysis could separately examine states with significant pharmaceutical and biopharmaceutical manufacturing activity, such as:
- New Jersey
- California
- North Carolina
- New York
- Pennsylvania
- Massachusetts
- Indiana
- Connecticut
- Other states
Allocation should consider API manufacturing facilities, pharmaceutical production, CDMO capacity, employment, investment, and company locations.
22. Validate Through Trade and Supply-Chain Data
Trade validation should use the following framework:
Apparent API Consumption = Domestic API Production + Imports − Exports ± Inventory Adjustment
Census international trade datasets provide monthly import and export statistics by HS code and can be used to track pharmaceutical chemical trade flows.
Trade codes should be mapped molecule-by-molecule where possible to avoid including pharmaceutical intermediates and unrelated chemicals.
23. Estimate Historical Market Size
Historical API market values should be reconstructed using:
Historical API Volume × Historical API ASP
Historical calculations should account for:
- Prescription volumes
- Generic drug penetration
- Branded drug production
- API imports
- Domestic API manufacturing
- Drug shortages
- Product launches
- Patent expirations
- API pricing changes
- Changes in manufacturing location
The historical model should maintain a consistent API definition across all years.
24. Forecast the United States APIs Market
The forecast should incorporate:
- Pharmaceutical production growth
- Generic drug demand
- Specialty pharmaceutical growth
- Biologics and biosimilars
- New drug approvals
- Patent expirations
- API outsourcing
- Domestic manufacturing investment
- Supply-chain diversification
- Drug shortages
- API pricing
- Manufacturing capacity expansion
The basic forecast formula should be:
Future API Market Size = Base-Year Market Size × (1 + CAGR) ^n
A driver-based forecast should then be used to test whether the resulting CAGR is consistent with expected pharmaceutical production and API demand.
25. Third Validation and Market Triangulation
The final United States API market estimate should be validated through three independent approaches.
Demand-Side Validation
Pharmaceutical Units × API Dosage × API ASP
Supply-Side Validation
Domestic API Production + API Imports − API Exports ± Inventory Adjustment
Company-Level Validation
API Revenue of U.S.-Relevant API Manufacturers + Estimated Captive API Value
The three approaches should not simply be averaged. Differences should be investigated based on API classification, captive production, imported APIs, intermediates, inventory, transfer pricing, and whether the estimate represents API consumption, commercial API sales, or domestic API manufacturing.
Core Formula
United States API Market = Σ (API Volume Consumed × Average API Selling Price)
Supply-Side Cross-Check
U.S. API Consumption = Domestic API Production + API Imports − API Exports ± Inventory Adjustment
Domestic Manufacturing Market
U.S. API Manufacturing Market = Σ (Domestic API Production Volume × Domestic API ASP)
The API volume × ASP model should be the primary methodology, while FDA establishment and DMF data, pharmaceutical production, company revenues, and international trade data should be used to validate the estimate. FDA's current data infrastructure provides particularly useful checkpoints through API establishment registrations, Type II DMFs, and approved-product/active-ingredient databases.
Market Segmentation
Business Mode
- Captive APIs
- Merchant APIs
Synthesis Type
- Biotech
- Synthetic
Drug Type
- Generic
- Innovative
Application
- Cardiovascular Diseases
- Endocrinology
- CNS & Neurology
- Oncology
- Gastroenterology
- Orthopedic
- Pulmonology
- Nephrology
- Ophthalmology
- Others
States
- California
- Texas
- New York
- Florida
- Illinois
- Pennsylvania
- Ohio
- Georgia
- New Jersey
- Washington
- North Carolina
- Massachusetts
- Virginia
- Michigan
- Maryland
- Colorado
- Tennessee
- Indiana
- Arizona
- Minnesota
- Wisconsin
- Missouri
- Connecticut
- South Carolina
- Oregon
- Louisiana
- Alabama
- Kentucky
- Rest of United States
All the Key players have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Pfizer Inc.
- Novartis AG
- BASF SE
- Teva Pharmaceutical Industries Ltd
- Viatris Inc.
- Sanofi Inc.
- Merck KGaA
- Reddy's Laboratories Ltd
- Lupin Ltd
- Bristol-Myers Squibb
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Business Mode, Synthesis Type, Drug Type, Application and States |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.