Global O-Ring Seals Market Report by Type (Synthetic Rubber, Thermoplastic Elastomer), Application (Electrical & Electronic Products, Aerospace Equipment, Energy, Food & Beverages, Healthcare & Medical, Automotive & Transportation, Machinery Manufacturing, Others), Countries and Company Analysis 2026-2034
Buy NowO-ring Seals Market Size and Forecast
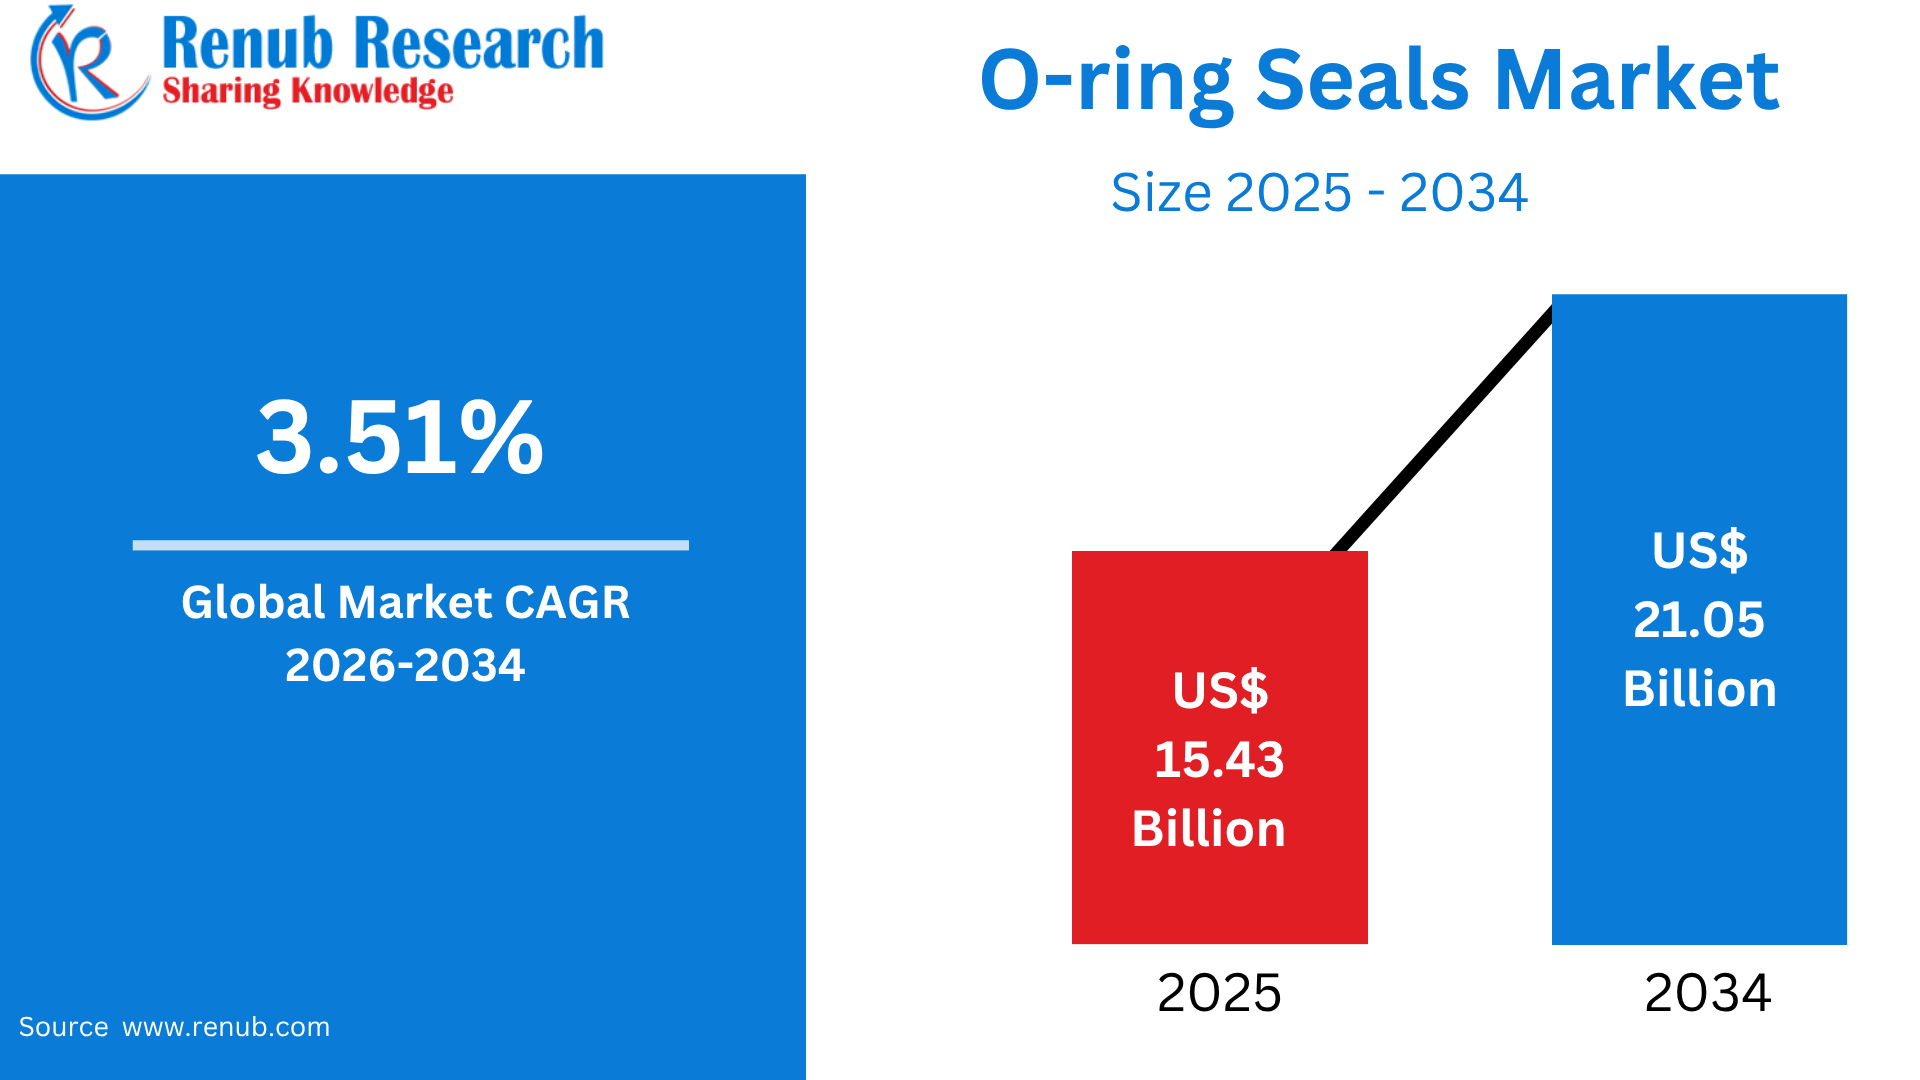
O-ring seals market is projected to grow steadily from US$ 15.43 billion in 2025 to US$ 21.05 billion by 2034, registering a compound annual growth rate (CAGR) of 3.51% during the forecast period from 2026 to 2034. Market growth is primarily driven by rising demand across the automotive, aerospace, oil & gas, manufacturing, and industrial machinery sectors. O-ring seals play a critical role in preventing fluid and gas leakage while ensuring the durability, efficiency, and reliability of mechanical systems and equipment.
What is O-Ring Seals and Their Uses & Popularity Worldwide
O-ring seals are circular, elastomeric sealing components with a round cross-section that are designed to prevent the leakage of liquids and gases between two connected surfaces. They are among the most widely used mechanical seals because of their simple design, cost-effectiveness, and excellent sealing performance under both static and dynamic conditions. O-rings are manufactured from materials such as nitrile rubber (NBR), silicone, fluorocarbon (FKM/Viton), EPDM, neoprene, and polyurethane, allowing them to withstand high temperatures, pressure variations, chemicals, oils, and harsh operating environments. These seals are extensively used in automotive engines, hydraulic and pneumatic systems, aerospace equipment, industrial machinery, oil & gas pipelines, medical devices, food processing equipment, and water treatment systems.
Globally, millions of O-rings are installed every year across manufacturing and engineering industries due to their durability, ease of installation, and low maintenance requirements. Their popularity continues to grow with increasing industrial automation, expansion of electric vehicle production, renewable energy projects, and advanced manufacturing technologies. Continuous innovations in high-performance elastomers and customized sealing solutions are further enhancing O-ring reliability, making them an indispensable component in modern industrial, commercial, and transportation applications worldwide.
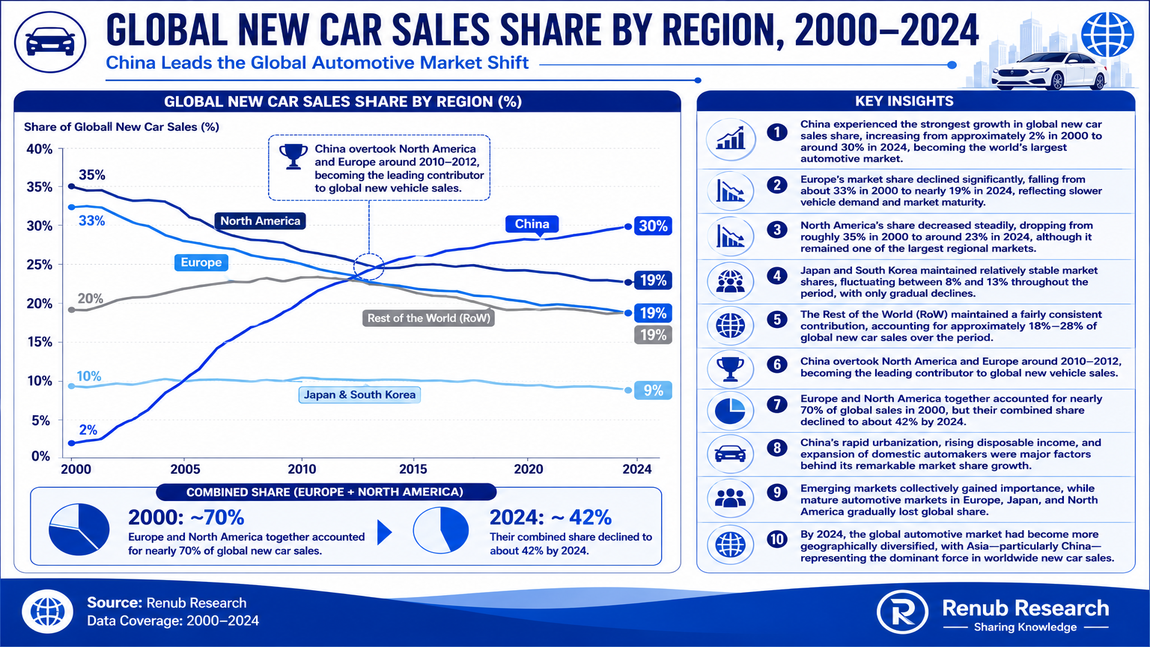
Global new car sales share by region, 2000-2024
- China experienced the strongest growth in global new car sales share, increasing from approximately 2% in 2000 to around 30% in 2024, becoming the world’s largest automotive market.
- Europe’s market share declined significantly, falling from about 33% in 2000 to nearly 19% in 2024, reflecting slower vehicle demand and market maturity.
- North America’s share decreased steadily, dropping from roughly 35% in 2000 to around 23% in 2024, although it remained one of the largest regional markets.
- Japan and South Korea maintained relatively stable market shares, fluctuating between 8% and 13% throughout the period, with only gradual declines.
- The Rest of the World (RoW) maintained a fairly consistent contribution, accounting for approximately 18%–28% of global new car sales over the period.
- China overtook North America and Europe around 2010–2012, becoming the leading contributor to global new vehicle sales.
- Europe and North America together accounted for nearly 70% of global sales in 2000, but their combined share declined to about 42% by 2024.
- China’s rapid urbanization, rising disposable income, and expansion of domestic automakers were major factors behind its remarkable market share growth.
- Emerging markets collectively gained importance, while mature automotive markets in Europe, Japan, and North America gradually lost global share.
- By 2024, the global automotive market had become more geographically diversified, with Asia—particularly China—representing the dominant force in worldwide new car sales.
Growth Driver
Expanding Automotive Production and Electrification of Vehicles
The automotive industry remains one of the largest consumers of O-ring seals, driving substantial market growth worldwide. O-rings are essential for sealing engines, fuel injection systems, braking systems, transmissions, air conditioning units, battery packs, and thermal management systems in both conventional and electric vehicles. According to international automotive industry estimates, more than 90 million passenger and commercial vehicles are produced each year globally, creating significant demand for high-performance sealing solutions. The rapid expansion of electric vehicle (EV) production has further increased the need for advanced O-rings capable of withstanding high temperatures, battery chemicals, and coolant systems. Modern EVs require hundreds of sealing components to ensure leak-free operation and enhance battery safety. Manufacturers are increasingly adopting fluorocarbon (FKM), EPDM, and silicone O-rings due to their superior resistance to heat and aggressive fluids. Rising vehicle ownership in emerging economies, stricter emission regulations, and growing investments in automotive manufacturing continue to strengthen demand for durable O-ring seals, supporting long-term market expansion across the global transportation sector.
Growing Industrial Automation and Manufacturing Activities
Rapid industrialization and the increasing adoption of automated manufacturing systems are significantly driving the global O-ring seals market. O-rings play a vital role in hydraulic systems, pneumatic equipment, compressors, pumps, valves, robotic machinery, and industrial processing equipment by preventing fluid and gas leakage under high-pressure operating conditions. According to the International Federation of Robotics (IFR), more than 4 million industrial robots are currently operating worldwide, highlighting the increasing automation of manufacturing facilities. Every automated production line depends on reliable sealing components to maintain efficiency, minimize equipment downtime, and reduce maintenance costs. Expanding industries including chemicals, food processing, pharmaceuticals, mining, heavy machinery, and packaging continue to increase demand for durable sealing technologies. Manufacturers are also developing advanced elastomer compounds with improved chemical resistance, wear resistance, and temperature tolerance to meet evolving industrial requirements. As factories continue investing in Industry 4.0 technologies, predictive maintenance, and smart manufacturing, demand for high-performance O-ring seals is expected to increase steadily across global industrial markets.
Rising Investments in Oil & Gas, Aerospace, and Infrastructure Projects
The expansion of oil & gas exploration, aerospace manufacturing, and large-scale infrastructure development is creating strong demand for high-quality O-ring seals worldwide. O-rings are critical components in drilling equipment, pipelines, hydraulic cylinders, valves, aircraft engines, landing gear systems, construction machinery, and heavy equipment operating under extreme temperatures and pressures. Global energy demand continues to rise, encouraging investments in offshore drilling, natural gas processing, and pipeline infrastructure that require highly reliable sealing solutions. Similarly, commercial aviation continues expanding, with thousands of new aircraft scheduled for delivery over the coming decades to accommodate increasing passenger traffic. Infrastructure development projects involving water treatment plants, railways, renewable energy facilities, and construction equipment also rely heavily on hydraulic and pneumatic sealing systems. High-performance materials such as fluorosilicone, PTFE, and hydrogenated nitrile rubber (HNBR) enable O-rings to perform reliably in harsh environments. Continuous investments across these industries are expected to sustain long-term demand for advanced sealing technologies and contribute significantly to market growth.
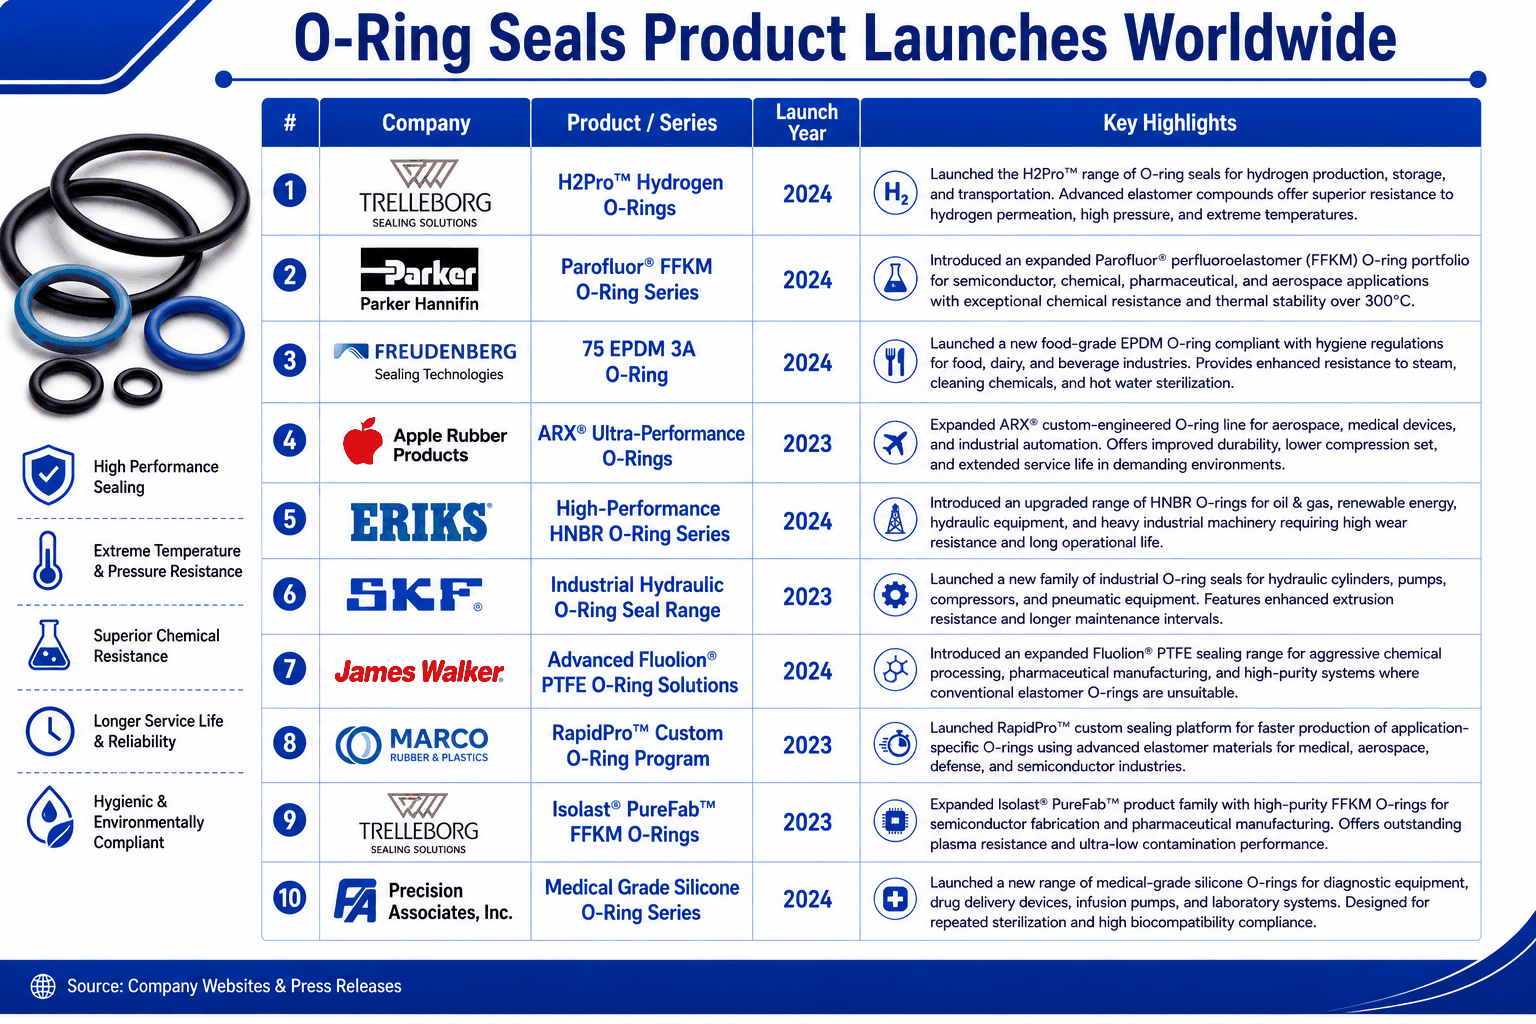
O-Ring Seals Product Launches Worldwide
- Trelleborg Sealing Solutions – H2Pro™ Hydrogen O-Rings (2024): Trelleborg launched the H2Pro™ range of O-ring seals specifically engineered for hydrogen production, storage, and transportation systems. The products feature advanced elastomer compounds with superior resistance to hydrogen permeation, high pressure, and extreme temperatures, supporting the expanding hydrogen energy sector.
- Parker Hannifin – Parofluor® FFKM O-Ring Series (2024): Parker introduced an expanded Parofluor® perfluoroelastomer (FFKM) O-ring portfolio designed for semiconductor manufacturing, chemical processing, pharmaceutical production, and aerospace applications requiring exceptional chemical resistance and thermal stability exceeding 300°C.
- Freudenberg Sealing Technologies – 75 EPDM 3A O-Ring (2024): Freudenberg launched a new food-grade EPDM O-ring that complies with stringent hygiene regulations for food processing, dairy, and beverage industries while providing enhanced resistance to steam, cleaning chemicals, and hot water sterilization.
- Apple Rubber Products – ARX® Ultra-Performance O-Rings (2023): Apple Rubber expanded its ARX® custom-engineered O-ring product line for aerospace, medical devices, and industrial automation. The new seals offer improved durability, lower compression set, and extended service life in demanding operating environments.
- ERIKS – High-Performance HNBR O-Ring Series (2024): ERIKS introduced an upgraded range of Hydrogenated Nitrile Butadiene Rubber (HNBR) O-rings designed for oil & gas, renewable energy, hydraulic equipment, and heavy industrial machinery requiring high wear resistance and long operational life.
- SKF – Industrial Hydraulic O-Ring Seal Range (2023): SKF launched a new family of industrial O-ring seals optimized for hydraulic cylinders, pumps, compressors, and pneumatic equipment. The products feature enhanced extrusion resistance and longer maintenance intervals for heavy-duty industrial applications.
- James Walker – Advanced Fluolion® PTFE O-Ring Solutions (2024): James Walker introduced an expanded Fluolion® PTFE sealing range for aggressive chemical processing, pharmaceutical manufacturing, and high-purity industrial systems where conventional elastomer O-rings are unsuitable.
- Marco Rubber & Plastics – RapidPro™ Custom O-Ring Program (2023): Marco Rubber launched its RapidPro™ custom sealing platform, enabling faster production of application-specific O-rings using advanced elastomer materials for medical, aerospace, defense, and semiconductor industries.
- Trelleborg Sealing Solutions – Isolast® PureFab™ FFKM O-Rings (2023): Trelleborg expanded its Isolast® PureFab™ product family with high-purity FFKM O-rings developed for semiconductor fabrication and pharmaceutical manufacturing, offering outstanding plasma resistance and ultra-low contamination performance.
- Precision Associates Inc. – Medical Grade Silicone O-Ring Series (2024): Precision Associates launched a new range of medical-grade silicone O-rings for diagnostic equipment, drug delivery devices, infusion pumps, and laboratory systems. The products are designed for repeated sterilization and comply with stringent biocompatibility requirements for healthcare applications.
Challenge
Volatility in Raw Material Prices and Supply Chain Disruptions
One of the major challenges facing the O-ring seals market is the fluctuation in raw material prices and periodic disruptions in global supply chains. O-rings are manufactured using elastomers such as nitrile rubber, silicone, fluorocarbon (FKM), EPDM, neoprene, and polyurethane, many of which are derived from petrochemical feedstocks. Changes in crude oil prices directly influence production costs for these materials, creating uncertainty for manufacturers. In addition, geopolitical tensions, transportation delays, labor shortages, and disruptions in global shipping networks can interrupt the supply of raw materials and finished sealing products. Such disruptions increase procurement costs, extend production lead times, and reduce inventory availability for industrial customers. Smaller manufacturers often face greater financial pressure because they have limited bargaining power with suppliers. To remain competitive, companies must invest in diversified sourcing strategies, regional manufacturing facilities, and alternative material development. These ongoing supply chain challenges continue to impact profitability and operational efficiency throughout the global O-ring seals industry.
Increasing Competition from Alternative Sealing Technologies
The O-ring seals market also faces growing competition from alternative sealing solutions that offer advantages in specialized industrial applications. Components such as lip seals, mechanical seals, gasket systems, spring-energized seals, PTFE seals, and customized engineered sealing products are increasingly selected for applications involving extreme temperatures, aggressive chemicals, or ultra-high-pressure environments. These alternatives often provide longer service life, lower friction, or improved resistance under demanding operating conditions where conventional elastomer O-rings may experience wear or degradation. Industries such as aerospace, semiconductor manufacturing, pharmaceuticals, and chemical processing frequently require highly specialized sealing systems that exceed the performance capabilities of standard O-rings. In addition, customers increasingly demand maintenance-free equipment with extended operating lifecycles, encouraging investment in premium sealing technologies. Manufacturers of O-ring seals must continuously improve material performance, precision manufacturing, and product customization to remain competitive. Failure to meet evolving industry requirements may reduce market share in high-value industrial applications, despite continued demand in traditional sectors.
Rising Demand for High-Performance Elastomer Sealing Solutions in Synthetic Rubber O-Ring Seals
Synthetic Rubber O-Ring Seals Market is experiencing steady growth due to the increasing demand for durable, chemical-resistant, and temperature-tolerant sealing components across industrial sectors. Synthetic rubber materials such as nitrile rubber (NBR), fluorocarbon (FKM), EPDM, silicone, hydrogenated nitrile butadiene rubber (HNBR), and neoprene dominate the market because they offer superior performance compared to natural rubber under demanding operating conditions. These O-rings are widely used in automotive engines, hydraulic systems, industrial machinery, aerospace equipment, food processing plants, and medical devices. Globally, the automotive industry manufactures more than 90 million vehicles annually, creating significant demand for high-performance synthetic rubber seals. Industrial automation and expanding manufacturing activities further increase the need for reliable sealing systems capable of preventing fluid and gas leakage under high pressure. Continuous material innovations have improved resistance to aggressive chemicals, UV radiation, ozone exposure, and extreme temperatures ranging from approximately -50°C to over 250°C, making synthetic rubber O-rings the preferred sealing solution across numerous industrial applications worldwide.
Increasing Aircraft Production and Demand for High-Reliability Components
Aerospace O-Ring Seals Market is expanding steadily as commercial aviation, military modernization, and space exploration programs continue to increase worldwide. O-ring seals are essential components in aircraft hydraulic systems, fuel systems, landing gear assemblies, engines, environmental control systems, and spacecraft equipment, where even minor leakage can compromise operational safety. Modern commercial aircraft contain thousands of sealing components, many of which are high-performance O-rings designed to withstand extreme temperatures, vibration, pressure fluctuations, and aggressive aviation fuels. The aerospace industry continues to experience strong demand as airlines expand their fleets to accommodate rising passenger traffic and replace aging aircraft. Advanced materials including fluorosilicone, fluorocarbon (FKM), perfluoroelastomer (FFKM), and silicone are increasingly used because they maintain sealing integrity under harsh operating environments. Growing investments in reusable launch vehicles, satellite deployment, defense aviation, and next-generation aircraft technologies are creating additional opportunities for aerospace-grade O-ring manufacturers. Continuous improvements in material science and precision manufacturing further enhance product reliability, supporting long-term market expansion.
Expanding Medical Device Manufacturing and Infection Control Requirements
Healthcare and Medical O-Ring Seals Market is growing rapidly due to increasing production of medical devices, diagnostic equipment, pharmaceutical processing systems, and laboratory instruments requiring reliable contamination-free sealing solutions. Medical-grade O-rings are widely used in ventilators, infusion pumps, dialysis equipment, surgical instruments, diagnostic analyzers, imaging systems, and drug delivery devices. The global healthcare sector performs hundreds of millions of medical procedures annually, creating sustained demand for precision sealing components capable of maintaining sterile operating conditions. Medical O-rings are commonly manufactured from silicone, EPDM, fluorocarbon, and other biocompatible elastomers that meet strict regulatory and hygiene standards. These materials offer excellent resistance to sterilization methods including steam autoclaving, gamma radiation, ethylene oxide, and chemical disinfectants. Rising healthcare expenditures, aging populations, increasing chronic disease prevalence, and expanding pharmaceutical manufacturing are further accelerating market growth. Continuous advancements in minimally invasive surgical equipment, wearable medical devices, and home healthcare technologies continue to strengthen demand for high-quality medical O-ring seals worldwide.
Industrial Automation Driving Demand for Reliable Sealing Components
Machinery Manufacturing O-Ring Seals Market continues to expand as manufacturers increasingly adopt automated production systems, robotics, and high-performance industrial equipment. O-ring seals play a critical role in hydraulic cylinders, pneumatic systems, compressors, pumps, gearboxes, valves, injection molding machines, and precision manufacturing equipment by preventing leakage and maintaining pressure integrity. According to industrial estimates, more than 4 million industrial robots are currently operating in manufacturing facilities worldwide, demonstrating the rapid pace of industrial automation. Every automated production system depends on reliable sealing components to minimize equipment downtime and improve operational efficiency. High-performance elastomers provide excellent resistance to abrasion, lubricants, hydraulic fluids, and elevated temperatures, ensuring long service life under demanding operating conditions. Growing investments in smart factories, Industry 4.0 technologies, heavy machinery production, and advanced manufacturing continue supporting market expansion. Manufacturers are also developing customized O-rings with enhanced wear resistance and longer maintenance intervals to improve equipment reliability across diverse industrial sectors.
Growing Investments in Oil, Gas, Renewable Energy, and Power Generation
Energy O-Ring Seals Market is witnessing sustained growth due to increasing investments across oil & gas exploration, renewable energy projects, power generation facilities, and hydrogen infrastructure. O-ring seals are critical components in drilling equipment, pipelines, valves, compressors, turbines, hydraulic systems, heat exchangers, and energy storage equipment, where reliable sealing is essential for operational safety and efficiency. Global energy consumption continues to rise, encouraging expansion of upstream oil exploration, liquefied natural gas facilities, offshore platforms, wind farms, solar power plants, and geothermal energy projects. High-performance O-rings manufactured from fluorocarbon, HNBR, PTFE, and perfluoroelastomer materials provide excellent resistance to aggressive chemicals, extreme temperatures, and high-pressure environments commonly encountered in energy applications. Growing hydrogen production and carbon capture projects are also creating new opportunities for specialized sealing technologies capable of handling highly demanding operating conditions. Continuous infrastructure investment, energy transition initiatives, and modernization of power generation facilities are expected to sustain long-term demand for advanced O-ring sealing solutions across the global energy industry.
United States Strong Manufacturing Base and High Demand from Automotive and Aerospace Industries
United States O-Ring Seals Market is one of the largest globally, supported by its well-established automotive, aerospace, industrial manufacturing, and oil & gas sectors. The U.S. manufactures more than 10 million passenger and commercial vehicles annually, creating substantial demand for high-performance sealing components used in engines, transmissions, braking systems, fuel systems, and electric vehicle battery assemblies. The country also operates one of the world’s largest aerospace industries, with thousands of commercial and military aircraft requiring precision O-ring seals for hydraulic systems, landing gear, and aircraft engines. In addition, the United States has over 900,000 manufacturing establishments, generating continuous demand for sealing products used in robotics, industrial machinery, pumps, compressors, and automation equipment. Growing investments in electric vehicles, renewable energy projects, semiconductor manufacturing, and industrial automation are encouraging the adoption of advanced elastomer materials such as fluorocarbon, silicone, and HNBR. Continuous product innovation and domestic manufacturing capabilities position the United States as a leading market for premium O-ring sealing solutions.
Expanding Industrial Engineering and Aerospace Manufacturing Supporting United Kingdom Growth
United Kingdom O-Ring Seals Market is experiencing steady expansion due to increasing demand from aerospace, industrial engineering, automotive manufacturing, pharmaceuticals, and renewable energy sectors. The UK remains one of Europe’s leading aerospace manufacturing hubs, producing advanced aircraft systems and precision engineering components that require highly reliable sealing technologies. The country manufactures hundreds of thousands of vehicles annually, supporting demand for O-rings in engines, fuel injection systems, braking assemblies, electric drivetrains, and thermal management systems. Industrial automation and modernization of manufacturing facilities continue to increase the use of hydraulic and pneumatic sealing solutions across factory equipment and production machinery. The UK’s growing pharmaceutical and medical device industries also rely heavily on medical-grade O-rings for sterile processing equipment and laboratory instruments. Expansion of offshore wind energy projects and hydrogen infrastructure further creates opportunities for specialized high-performance sealing materials capable of operating under extreme temperatures and pressures. Continuous research in advanced elastomers strengthens the country’s long-term market prospects.
Rapid Industrialization and Expanding Automotive Production Fuel India Demand
India O-Ring Seals Market is witnessing robust growth due to rapid industrialization, expanding manufacturing activities, and increasing investments in automotive, energy, and infrastructure development. India produces more than 25 million vehicles annually, making it one of the world’s largest automotive manufacturing centers and a major consumer of O-ring seals used in engines, transmissions, hydraulic systems, air conditioning units, and electric vehicles. The country’s expanding industrial machinery, construction equipment, railway, and agricultural equipment industries are also increasing demand for durable sealing components. Government initiatives such as “Make in India” continue encouraging domestic production of industrial equipment, automotive components, and engineering products, supporting local O-ring manufacturing. Rapid growth in pharmaceutical manufacturing, oil refining, chemical processing, and renewable energy projects further strengthens market opportunities. Increasing automation across factories and the adoption of Industry 4.0 technologies are driving demand for high-performance elastomer seals capable of delivering reliable performance under challenging operating conditions, positioning India as one of the fastest-growing O-ring seal markets globally.
Saudi Arabia Energy Sector Expansion and Vision 2030 Driving Industrial Demand
Saudi Arabia O-Ring Seals Market is growing steadily due to significant investments in oil & gas, petrochemicals, industrial manufacturing, and infrastructure development under Vision 2030. Saudi Arabia remains one of the world’s largest crude oil producers, with production capacity exceeding 10 million barrels per day, creating substantial demand for high-performance O-ring seals used in drilling equipment, pipelines, compressors, pumps, valves, and refinery operations. The country’s expanding petrochemical industry also requires chemically resistant sealing materials capable of operating in aggressive processing environments. Government investments in renewable energy, desalination plants, mining, logistics, and advanced manufacturing are creating new opportunities for industrial sealing products. Large-scale construction projects, including smart cities and transportation infrastructure, further increase demand for hydraulic and pneumatic equipment utilizing O-ring seals. Growing localization of manufacturing and industrial diversification initiatives are encouraging domestic production of engineering components. Combined with increasing investment in energy infrastructure and industrial modernization, these factors position Saudi Arabia as an important growth market for advanced O-ring sealing solutions in the Middle East.
Market Segmentation
Type:
- Synthetic Rubber
- Thermoplastic Elastomer
Application
- Electrical and Electronic Products
- Aerospace Equipment
- Energy
- Food and Beverages
- Healthcare and Medical
- Automotive and Transportation
- Machinery Manufacturing
- Others
Countries
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Thailand
- Malaysia
- Indonesia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players
- AB SKF
- NOK Corporation
- Zhongding Group
- ElringKlinger AG
- Freudenberg & Co. KG
- Hutchinson SA (TotalEnergies SE)
- Parker Hannifin Corporation
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Type, Application and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.