North America Non-Lethal Weapons Market Report by Product Type, Technology, End Use, Countries and Companies Analysis 2026-2034
Buy NowNorth America Non-Lethal Weapons Market Size and Forecast
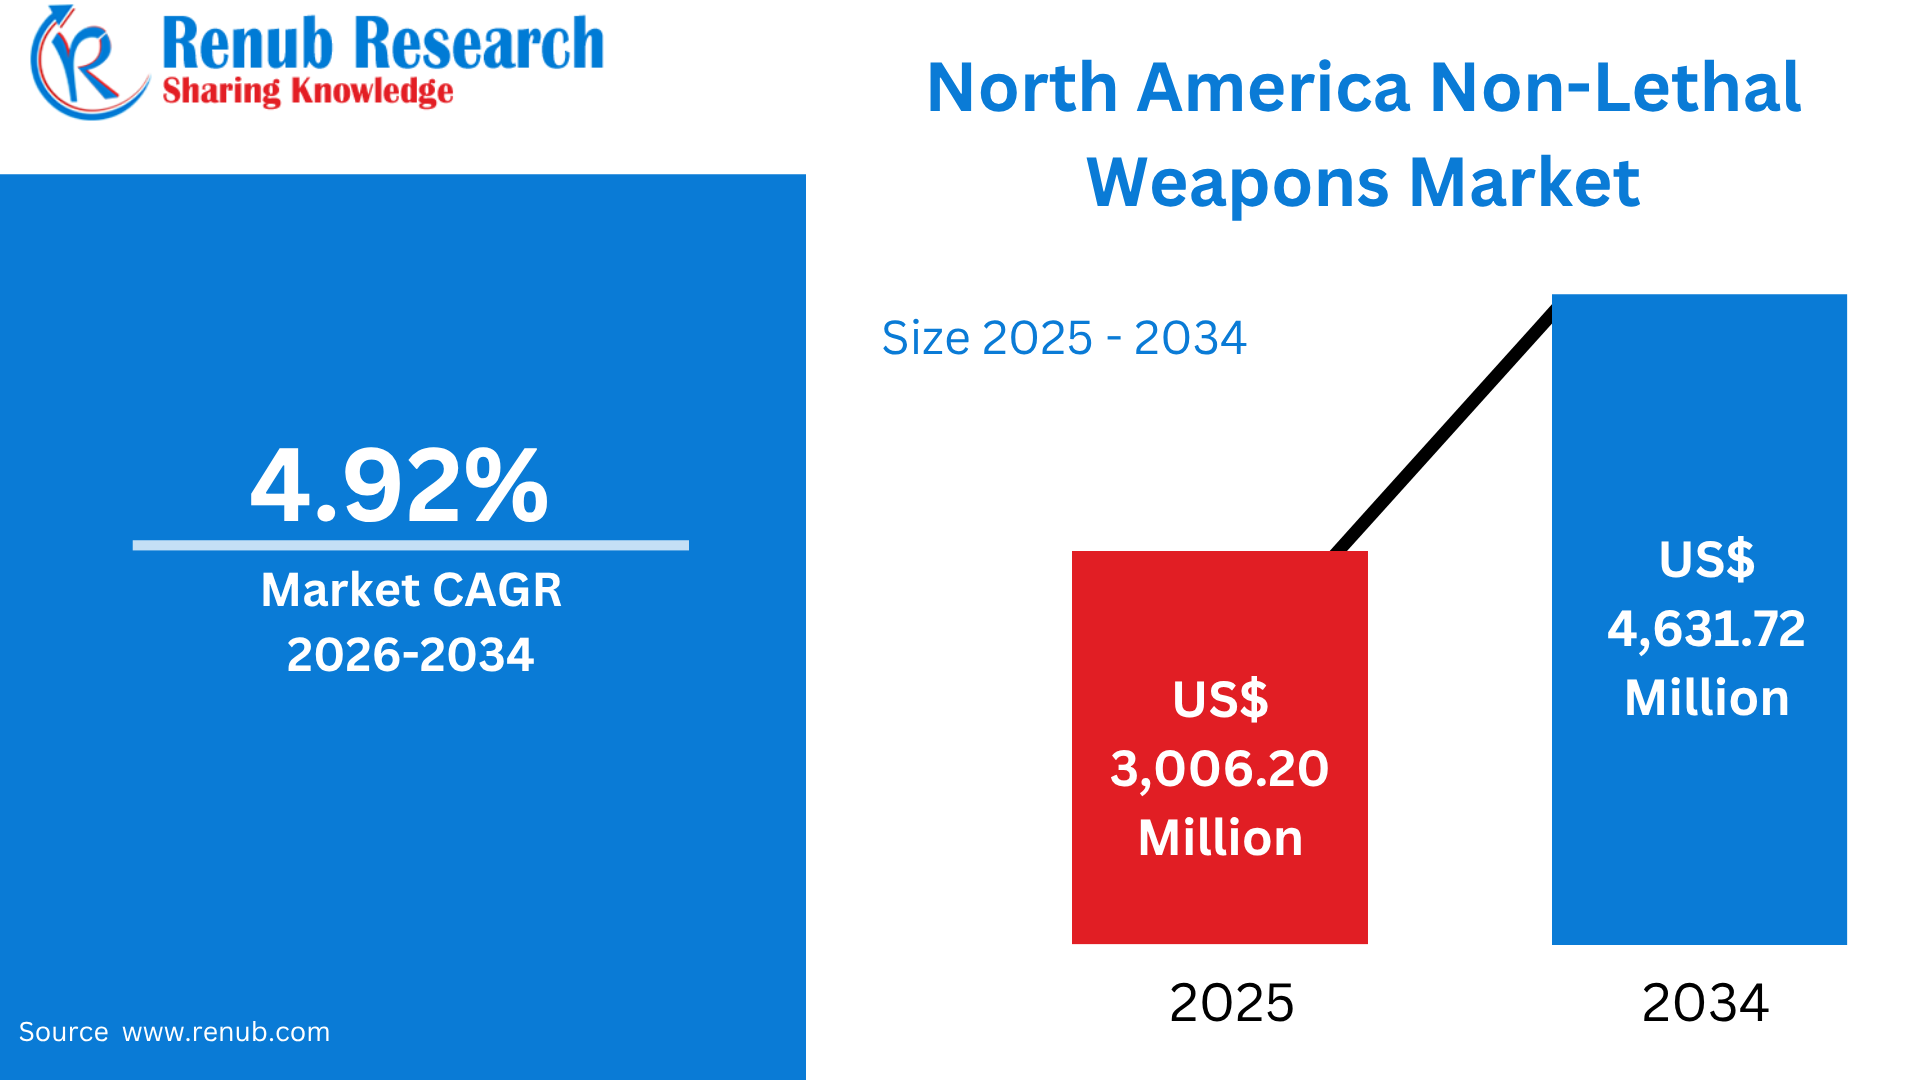
North America Non-Lethal Weapons Market is projected to grow from US$ 3,006.20 million in 2025 to US$ 4,631.72 million by 2034, expanding at a CAGR of 4.92% during 2026–2034. Market growth is supported by increasing demand for non-lethal solutions for crowd management, law enforcement, public safety, and defense applications. Modernization of police and security forces, rising investments in public safety technologies, and the need to reduce reliance on lethal force are contributing to adoption across the region.
What is the North America Non-Lethal Weapons Market? Uses & Popularity
North America Non-Lethal Weapons Market comprises technologies designed to incapacitate, deter, or control individuals while generally seeking to reduce the likelihood of fatal outcomes compared with conventional firearms. Major product categories include conducted-energy weapons, pepper spray and other chemical irritants, kinetic-impact devices, acoustic devices, and other less-lethal systems. These technologies are used by law enforcement, corrections agencies, security organizations, and selected defense and public-safety applications for crowd management, suspect apprehension, perimeter security, and emergency response. Their popularity is supported by the need for response options between verbal commands and lethal force. In the United States, the FBI reported that 82% of the U.S. population was covered by NIBRS-reporting law-enforcement agencies as of May 2024, demonstrating the extensive scale of organized law-enforcement infrastructure. Canada also recorded 14,488 firearm-related violent crimes in 2024, equal to 2.6% of police-reported violent crime, highlighting the broader public-safety environment in which police agencies require graduated response capabilities.
Protest Mobilizations in the United States
- BLM Protests (May–June 2020): Estimated 20.5 million participants, making this one of the largest protest mobilizations in recent U.S. history.
- No Kings 2 (October 2025): Estimated 7.0 million participants across multiple demonstrations.
- No Kings (June 2025): Estimated 5.0 million participants nationwide.
- Women’s March (January 2017): Estimated 4.6 million participants, with demonstrations held across the United States.
- March for Our Lives (March 2018): Estimated 2.2 million participants, centered on demonstrations advocating changes to gun-safety policies.
- Hands Off (April 2025): Estimated 1.5 million participants across participating demonstrations.
Source: Crowd Counting Consortium, ACLED, and various news reports.
Growth Drivers of the North America Non-Lethal Weapons Market
Increasing Demand for Public-Safety and Law-Enforcement Equipment
Growing requirements for public-safety equipment are supporting demand for non-lethal weapons across North America. Police departments, correctional institutions, border-security agencies, and specialized response units require tools that provide additional response options during confrontations, arrests, disturbances, and security incidents. The United States has an extensive law-enforcement network, with NIBRS data covering 82% of the national population as of May 2024. This broad operational base creates a substantial potential user market for less-lethal technologies. In Canada, police services reported 14,488 firearm-related violent crimes in 2024, representing 2.6% of all violent crime, while the national rate was 36.0 incidents per 100,000 population. Such public-safety challenges encourage agencies to maintain graduated-response capabilities. Modern procurement increasingly focuses on technologies that can provide distance, temporary incapacitation, or controlled intervention while complementing officer training and established use-of-force policies.
Modernization and Technological Advancement of Less-Lethal Systems
Technological innovation is another important factor supporting the North American market. Manufacturers are developing more sophisticated conducted-energy weapons, electronic control systems, irritant delivery platforms, acoustic technologies, and kinetic-impact equipment with improvements in ergonomics, targeting, monitoring, connectivity, and reliability. Modern law-enforcement agencies increasingly seek equipment that can integrate into broader officer-safety and evidence-management systems. Product development is also focused on improving accuracy and controllability while reducing unintended exposure and operational risks. The changing nature of public-safety requirements further encourages agencies to update equipment fleets rather than depend exclusively on legacy systems. In Canada, Statistics Canada recorded 14,488 firearm-related violent crimes in 2024, with firearm-related violent crime rates varying considerably between urban, rural, and northern regions. This geographic variation reinforces the need for adaptable equipment across different operational environments. Continued R&D, digital capabilities, compact designs, and improved training systems are therefore expected to contribute to market development.
Rising Focus on Graduated-Response and Crowd-Control Capabilities
The growing emphasis on graduated-response strategies is supporting adoption of non-lethal weapons for situations where authorities need an intervention option between physical control and lethal force. Law-enforcement agencies may deploy less-lethal technologies during crowd-management operations, high-risk arrests, correctional incidents, public-event security, and other situations requiring controlled intervention. The scale of public-safety operations across the region provides a broad application base. In the United States, NIBRS reporting included agencies serving 82% of the population as of May 2024, providing an indication of the extensive law-enforcement infrastructure operating across the country. Canada also recorded 23,014 weapons violations in 2024, according to Statistics Canada, illustrating the continuing need for law-enforcement capabilities addressing weapons-related incidents. Demand is consequently shifting toward equipment that supports proportional response, officer safety, and situational flexibility. Training requirements and agency policies remain important factors in determining how these systems are deployed.
Challenges of the North American Non-Lethal Weapons Market
Safety, Misuse, and Liability Concerns
Safety and liability considerations remain significant challenges for the non-lethal weapons industry. Although these products are designed to reduce the probability of fatal outcomes compared with firearms, they are not risk-free and can cause serious injury or, in some circumstances, death. Their effectiveness can also vary according to distance, environmental conditions, device type, subject characteristics, and deployment circumstances. Consequently, police and security organizations generally require comprehensive training, certification, operating procedures, and documentation. Agencies must also consider legal and financial exposure associated with inappropriate or excessive use. The issue is particularly important because non-lethal equipment is frequently used during rapidly changing confrontations where officers must make decisions under pressure. Regulatory requirements, internal policies, reporting procedures, and public scrutiny can increase procurement and training costs. As agencies modernize their equipment, manufacturers must therefore balance effectiveness with safety, reliability, and accountability. These considerations can lengthen purchasing decisions and create additional compliance requirements for suppliers seeking to expand across North American jurisdictions.
Regulatory Complexity and Public Acceptance
Regulatory differences, procurement requirements, and public concerns can constrain market expansion across North America. Rules governing the possession, carrying, deployment, training, and use of non-lethal weapons can differ between federal, state, provincial, municipal, and agency jurisdictions. Manufacturers therefore face multiple compliance environments when introducing products across the United States and Canada. Public acceptance is another consideration because debates surrounding police use of force can influence agency procurement decisions and operational policies. Statistics Canada reported that 14,488 firearm-related violent crimes occurred in Canada in 2024, but the rate declined 4.2% from 2023, demonstrating that public-safety conditions can change over time. Such changes can affect procurement priorities and budget allocations. Agencies must also demonstrate that equipment is supported by appropriate training and use-of-force policies. As a result, manufacturers may face longer evaluation cycles, jurisdiction-specific certifications, policy reviews, and additional training requirements before products achieve broad adoption.
North America Non-Lethal Weapons Product Launches
- PepperBall – Shatter™, Jammer™, and Lumen™ Projectiles (2025, USA): Introduced new kinetic projectiles designed for applications including marking, glass breaking, and sensor disruption.
- Wrap Technologies – MERLIN-Interdictor Drone Payload (2025, USA): Developed a drone-based non-lethal system intended to support remote suspect interdiction and law-enforcement operations.
- Byrna Technologies – Byrna CL Compact Launcher (2025, USA): Launched an ultra-compact less-lethal launcher designed for personal protection and potential law-enforcement applications.
- PepperBall – Sentry 68™ Launcher (2025, USA): Introduced a lightweight launcher designed for rapid-response and patrol applications.
- ASP Inc. – Defender LE OC Spray Line (2025, USA): Expanded its duty-grade OC spray portfolio with UV marking capabilities intended to assist with suspect identification.
- PepperBall – VK-SBL PRO PLUS™ Launcher (2025, USA): Introduced an enhanced projectile-launching platform featuring increased capacity and updated performance characteristics.
- RoboRounds/PepperBall – Lumen™ UV Marking Rounds (2025, USA): Developed UV-marking projectiles designed to support identification and tracking during law-enforcement and crowd-management operations.
- Wrap Technologies – DFR-X Drone System (2025, USA): Introduced a drone-based first-responder platform designed to provide remote, non-contact intervention capabilities.
- Byrna Technologies – Byrna CL Civilian Expansion Rollout (2025, USA): Expanded commercial availability of its compact less-lethal launcher platform for civilian personal-protection applications.
- PepperBall – Tactical Training & Deployment Upgrades (2025, USA): Expanded training and deployment programs incorporating integrated launch systems and updated field-training capabilities.
Chemical Irritants Support Rapid-Response Applications
North America Non-Lethal Gases and Sprays Weapons Market includes pepper spray, oleoresin capsicum (OC) formulations, tear gas, and other chemical irritant systems used to temporarily impair or deter individuals. These products are widely associated with law-enforcement, correctional, security, and crowd-management applications because they are portable, relatively easy to deploy, and can provide officers with a response option at short range. The U.S. Government Accountability Office identifies chemical spray, including pepper spray and tear gas, as a major category of less-lethal force used by law-enforcement agencies. Demand is supported by the need for equipment that can be incorporated into graduated-response policies, particularly during public-order incidents and high-risk arrests. Their comparatively compact form also makes them suitable for routine patrol operations. In Canada, the RCMP’s use-of-force framework emphasizes training, de-escalation, and documented decision-making, illustrating the importance of integrating less-lethal equipment with established operational procedures.
Kinetic Impact Munitions Enable Distance-Based Intervention
North America Non-Lethal Bullets Market comprises kinetic-impact ammunition and projectiles intended to provide law-enforcement personnel with a means of intervening from a greater distance than direct physical contact. Products can include rubber or polymer projectiles, bean-bag rounds, sponge rounds, and other specialized impact munitions. The U.S. Government Accountability Office specifically identifies rubber bullets and other kinetic-impact munitions among less-lethal force options used by federal agencies. These systems can be considered for public-order management, correctional environments, tactical incidents, and situations where maintaining distance is operationally important. In Canada, the RCMP classifies its extended-range impact weapon as an intermediate less-lethal option and notes that the increased distance can provide officers with additional time for de-escalation where possible. Market demand is therefore linked to modernization of law-enforcement equipment and the development of graduated-response capabilities. However, procurement and deployment depend heavily on agency training, policies, safety requirements, and jurisdiction-specific rules governing use of force.
Diverse Physical-Control Systems Expand Operational Options
North America Non-Lethal Weapons Mechanical and Kinetic Market encompasses physical-control and impact-based systems such as batons, riot-control equipment, shields, kinetic launch platforms, and other devices designed to provide intermediate response capabilities. Demand is supported by the need for scalable equipment across policing, corrections, public-event security, and specialized tactical operations. The U.S. Government Accountability Office categorizes physical tactics, batons, chemical sprays, munitions, and kinetic-impact munitions within the broader less-lethal force landscape. In Canada, the RCMP’s Incident Management/Intervention Model includes both conducted-energy weapons and extended-range impact weapons as intermediate options, demonstrating the role of multiple equipment categories within graduated intervention frameworks. Product development increasingly emphasizes ergonomics, durability, controllability, and compatibility with officer training. Market opportunities are also influenced by replacement cycles as agencies modernize older equipment. Nevertheless, adoption depends on procurement budgets, training requirements, safety assessments, and policies governing proportional and necessary use of force.
Police Modernization and Use-of-Force Policies Drive Demand
North America Law Enforcement Non-Lethal Weapons Market focuses on equipment that police and public-safety agencies use when circumstances require an intervention option short of deadly force. Major categories include conducted-energy weapons, chemical sprays, batons, kinetic-impact munitions, and other less-lethal technologies. The U.S. Department of Justice’s use-of-force policy requires its law-enforcement components to provide annual training on use-of-force policies and legal updates, while training must reinforce de-escalation and appropriate use of less-than-lethal and deadly force. This institutional emphasis supports continuing demand for equipment, training, certification, and replacement systems. In Canada, RCMP personnel carrying conducted-energy weapons must complete training and re-certify annually, while deployments require reporting and supervisory review. The market therefore extends beyond physical equipment to training and accountability infrastructure. Continued modernization of police fleets, changing public-safety requirements, and the development of technology-enabled systems are expected to support demand, although procurement remains closely tied to agency policies and available budgets.
Defense and Law-Enforcement Modernization Support United States Market Development
United States Non-Lethal Weapons Market is supported by demand from federal, state, and local law-enforcement agencies as well as military organizations seeking graduated-response capabilities. Product categories include conducted-energy weapons, OC sprays, kinetic-impact munitions, acoustic systems, and other technologies intended for situations where lethal force is not appropriate. The U.S. Department of Justice requires annual use-of-force training for its law-enforcement components and emphasizes de-escalation and appropriate application of less-than-lethal force. Federal oversight also highlights the importance of accurate reporting: a GAO review of 10 federal agencies found that 8 used less-lethal force during protest deployments examined after George Floyd’s death, while reporting gaps were identified in some agencies. These findings illustrate both the operational use and accountability requirements surrounding such technologies. Market development is further supported by product innovation, agency equipment replacement, specialized training, and demand for systems that can be incorporated into documented use-of-force frameworks. Regulatory scrutiny, procurement constraints, safety considerations, and public accountability remain important market factors.
Structured Training and Accountability Shape Canadian Adoption
Canada Non-Lethal Weapons Market is developing around law-enforcement requirements for controlled intervention, officer safety, and public protection. Key technologies include conducted-energy weapons, OC sprays, and extended-range impact systems. The Royal Canadian Mounted Police adopted conducted-energy weapons in December 2001, and current RCMP policy requires officers to complete training before carrying them and to re-certify annually. The RCMP also requires consideration of factors such as the environment and known health risks before deployment. The broader public-safety environment provides an ongoing operational requirement: Statistics Canada reported 591,856 police-reported violent crimes in 2024, equivalent to a rate of 1,433 per 100,000 population. Separately, police services recorded 14,488 firearm-related violent crimes in 2024, representing 2.6% of violent crime. These statistics do not directly measure non-lethal weapon demand, but they indicate the scale of public-safety activity requiring police response capabilities. Procurement remains influenced by training, policy, accountability, provincial requirements, and agency budgets.
North America Non-Lethal Weapons Market Segments
Product Type
- Gases and sprays
- Grenades
- Bullets
- Taser Guns
- Others
Technology
- Chemical
- Electroshock
- Mechanical and Kinetic
- Acoustic/Light
- Others
End Use
- Law Enforcement
- Military
- Others
Countries
- United States
- Canada
- Mexico
- Rest of North America
All the Key players have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Byrna Technologies Inc.
- General Dynamics Corporation
- Moog Inc.
- Raytheon Technologies Corporation
- Rheinmetall AG
- Textron Inc.
- Combined Systems Inc.
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Million |
| Segment Covered |
Product Type, Technology, End Use and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.