Global Desalination Market Report by Technology, Application, Water Source, Countries and Company Analysis 2026-2034
Buy NowGlobal Desalination Market Size & Forecast
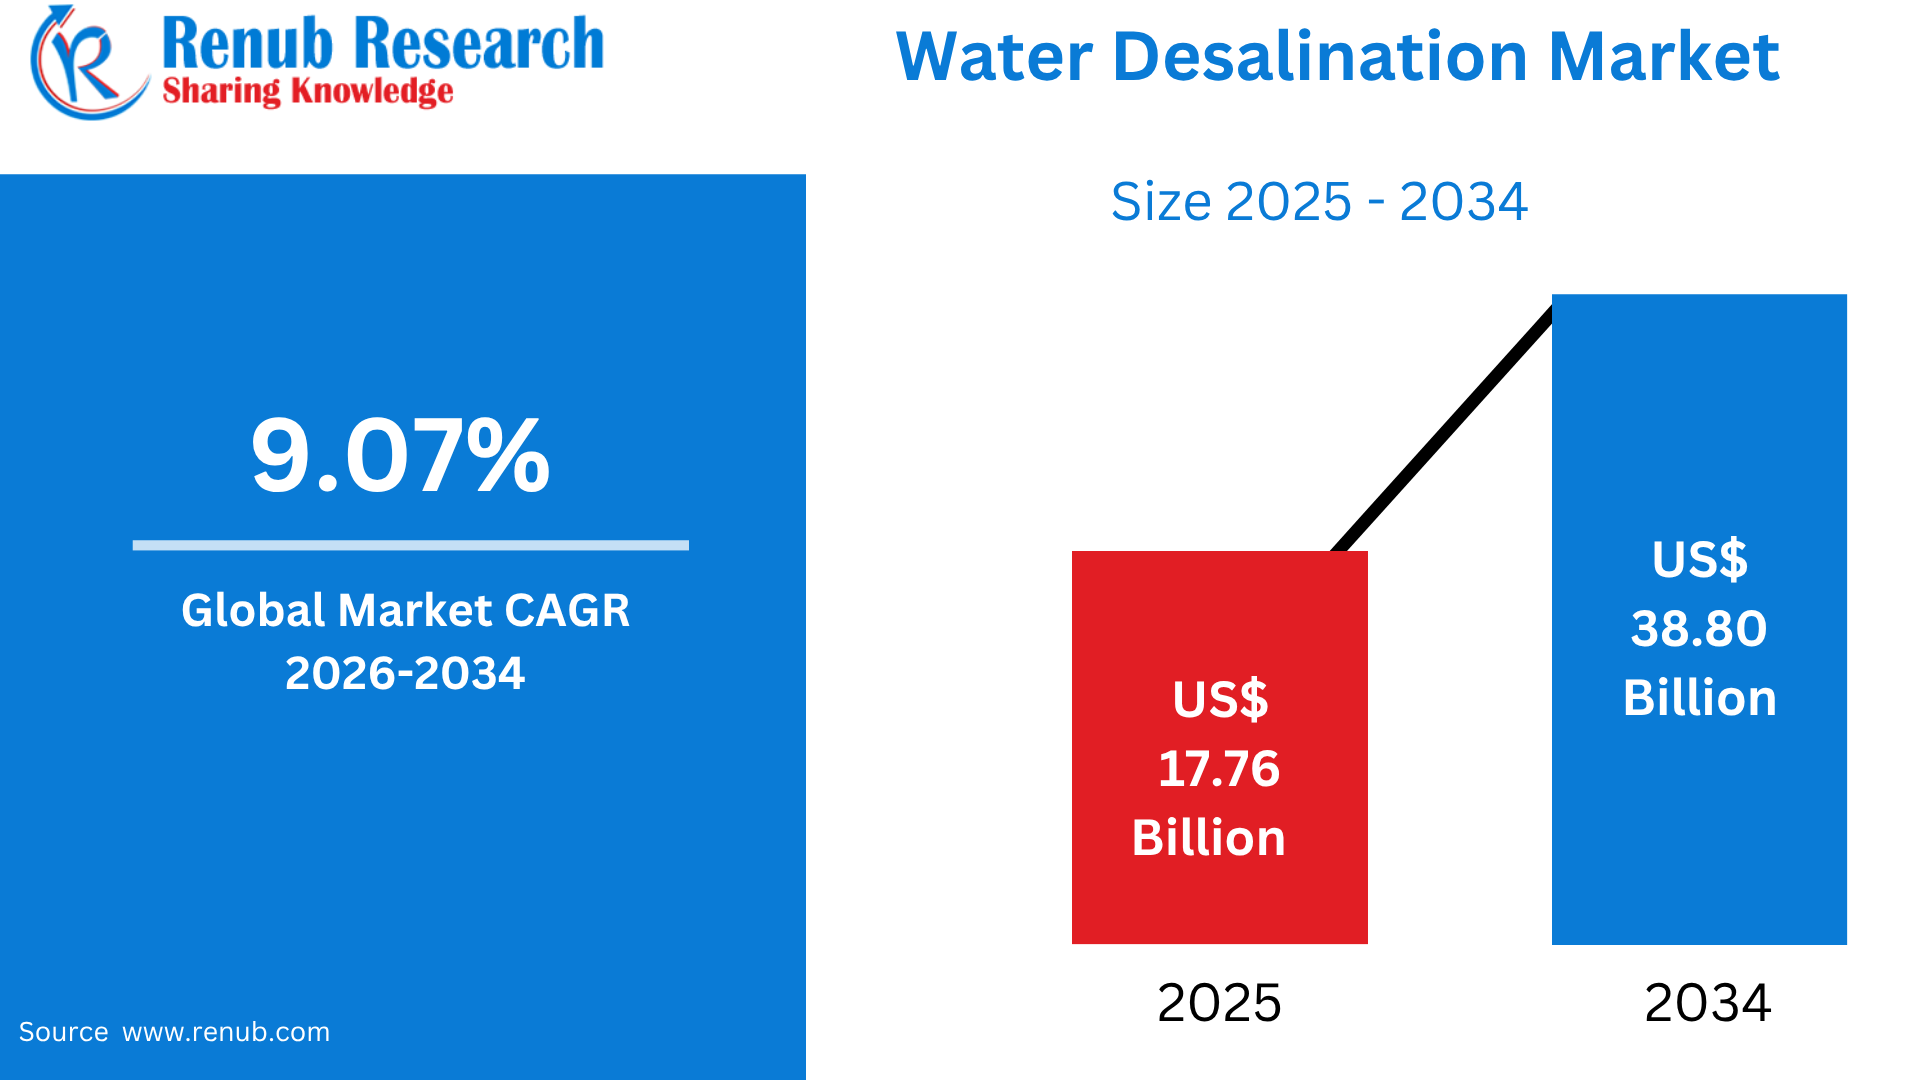
The global desalination market is projected to expand from US$ 17.76 billion in 2025 to US$ 38.80 billion by 2034, registering a compound annual growth rate (CAGR) of 9.07% during the forecast period from 2026 to 2034. Market growth is primarily driven by increasing water scarcity, rapid population growth, and rising industrial demand for freshwater. In addition, continuous advancements in desalination technologies, growing government investments in water infrastructure, and the adoption of sustainable water management practices are accelerating the expansion of the global desalination market.
What is Desalination and Its Uses & Popularity Worldwide
Desalination is the process of removing dissolved salts, minerals, and other impurities from seawater or brackish water to produce fresh water suitable for drinking, industrial applications, and agricultural use. The two most widely used desalination technologies are reverse osmosis (RO) and thermal desalination, both of which are designed to address freshwater shortages in water-scarce regions. As global water demand continues to rise due to population growth, urbanization, climate change, and industrial expansion, desalination has become an essential solution for ensuring a reliable and sustainable water supply.
Worldwide, desalination is gaining significant popularity, particularly in regions facing chronic water stress, such as the Middle East, North Africa, Australia, and parts of Asia and the Americas. Governments and private organizations are investing heavily in advanced desalination plants to strengthen water security and reduce dependence on limited freshwater resources. Technological innovations, including energy-efficient membranes and renewable energy-powered desalination systems, are improving operational efficiency while lowering environmental impacts. As a result, desalination is increasingly recognized as a critical component of global water management and long-term sustainability strategies.
U.S. Department of Energy (DOE) announced Renewed Funding
The U.S. Department of Energy (DOE) has announced $75 million in renewed funding over five years for the National Alliance for Water Innovation (NAWI), its Energy Innovation Hub dedicated to advancing desalination and water treatment technologies. During this second phase, NAWI will continue collaborating with leading industry stakeholders, national laboratories, and academic institutions to address key technical challenges and accelerate research aimed at significantly reducing the energy consumption and cost of water purification and desalination systems. The initiative is expected to drive innovation in next-generation desalination technologies, support the modernization of the nation’s water infrastructure, expand access to safe and reliable drinking water, and contribute to the United States’ goal of achieving a net-zero emissions economy by 2050.
CITIC Construction Signs Egypt Desalination Membrane Plant Deal in April 2026
Egypt’s Ministry of Housing has signed a Memorandum of Understanding (MoU) with China’s CITIC Construction and the International Company for Petroleum and Industrial Services (ANCOM) to establish a manufacturing facility for reverse osmosis (RO) membranes used in seawater desalination plants. The agreement aims to strengthen Egypt’s domestic desalination manufacturing capabilities and support the country’s expanding water infrastructure projects. CITIC Construction, a leading subsidiary of CITIC Limited (HKEX: 0267), brings extensive global expertise in designing and delivering reverse osmosis desalination systems, having successfully implemented similar projects across numerous countries. The initiative is expected to enhance local production capacity, reduce reliance on imported membrane technologies, and support Egypt’s long-term water security objectives.
Growth Driver
Rising Global Water Scarcity and Freshwater Demand
Water scarcity has become one of the strongest drivers of the global desalination market as increasing populations, climate change, and declining freshwater resources place immense pressure on existing water supplies. According to the United Nations, around 2.2 billion people lack access to safely managed drinking water, while nearly 4 billion people experience severe water scarcity for at least one month each year. Rapid urbanization and industrialization are further widening the gap between freshwater demand and available resources. Desalination provides a dependable and climate-resilient source of potable water by converting seawater and brackish water into freshwater, making it particularly valuable in arid and coastal regions. Countries such as Saudi Arabia, the UAE, Israel, Australia, and Spain have significantly expanded desalination capacity to ensure long-term water security. Moreover, prolonged droughts in regions including California, South Africa, and Southern Europe are accelerating investments in desalination infrastructure. As freshwater resources continue to diminish due to overextraction and changing weather patterns, governments and utilities worldwide are increasingly adopting desalination as a strategic solution, driving sustained growth in the global market.
Government Investments and Water Infrastructure Development
Government initiatives and large-scale investments in water infrastructure are significantly accelerating the growth of the desalination market worldwide. Many countries have incorporated desalination into their national water security strategies to reduce dependence on rainfall and groundwater resources. The Middle East accounts for more than 45% of the world’s installed desalination capacity, supported by continuous investments in large-scale seawater desalination plants. Saudi Arabia has announced multiple multi-billion-dollar water infrastructure projects under its Vision 2030 program, while the UAE continues to expand high-capacity reverse osmosis plants to meet growing municipal and industrial demand. In addition, countries including India, China, Australia, and the United States are increasing funding for desalination facilities to address regional water shortages. Public-private partnerships, favorable regulatory frameworks, and financial incentives are encouraging private investment in advanced desalination technologies. International organizations and development banks are also supporting desalination projects in water-stressed developing nations. These sustained infrastructure investments are strengthening water resilience and creating substantial opportunities for desalination equipment manufacturers, engineering firms, and technology providers across the global market.
Technological Advancements Improving Efficiency and Sustainability
Continuous technological innovation is making desalination more energy-efficient, environmentally sustainable, and economically viable, thereby driving market expansion. Reverse osmosis (RO) technology now accounts for more than 65% of global desalination capacity, owing to its lower energy consumption compared to traditional thermal desalination methods. Advances in high-performance membranes, energy recovery devices, digital monitoring systems, and artificial intelligence-based plant optimization have significantly reduced operating costs while improving water recovery rates. Renewable energy integration, particularly solar- and wind-powered desalination plants, is gaining momentum in regions with abundant renewable resources, helping lower carbon emissions and operational expenses. Research into next-generation membrane materials, graphene-based filtration, and zero-liquid-discharge technologies is further enhancing desalination efficiency while minimizing environmental impacts associated with brine disposal. These technological improvements are making desalination increasingly attractive for municipalities, industrial facilities, mining operations, and power plants seeking reliable freshwater supplies. As production costs continue to decline and operational performance improves, advanced desalination technologies are expected to witness widespread adoption across both developed and emerging economies.
Challenges
High Capital Investment and Energy Consumption
Despite strong market growth, the desalination industry continues to face challenges related to high capital expenditure and energy-intensive operations. Constructing large-scale seawater desalination plants requires significant investments in intake systems, treatment facilities, pipelines, and distribution networks, often costing hundreds of millions of dollars. In addition, energy represents 30–50% of the total operating cost of many desalination plants, particularly in thermal desalination systems. Although reverse osmosis technology has reduced electricity consumption considerably over the past two decades, desalination remains more expensive than conventional freshwater treatment in many regions. Rising electricity prices and dependence on fossil-fuel-generated power further increase operating expenses and carbon emissions. Developing countries with limited financial resources often struggle to fund large desalination projects without external financing or government subsidies. These financial barriers can delay project implementation and restrict market penetration in lower-income regions. Continued investment in renewable energy integration, energy-efficient membranes, and innovative financing models will be essential to reducing costs and improving the long-term affordability of desalination.
Environmental Concerns Related to Brine Disposal
Environmental impacts associated with desalination, particularly concentrated brine discharge, remain a significant challenge for market expansion. For every liter of freshwater produced, desalination plants generate a highly saline waste stream containing dissolved salts, treatment chemicals, and trace metals. Studies estimate that global desalination facilities collectively produce over 140 million cubic meters of brine every day, much of which is discharged into oceans or coastal ecosystems. Improper brine disposal can increase seawater salinity, reduce dissolved oxygen levels, and negatively affect marine biodiversity, coral reefs, and coastal habitats. Environmental regulations governing marine discharge are becoming increasingly stringent, requiring operators to invest in advanced brine management systems and monitoring technologies. Researchers are exploring sustainable solutions such as mineral recovery, brine concentration, zero-liquid-discharge systems, and beneficial industrial reuse to minimize ecological impacts. However, these technologies often increase project complexity and costs. Addressing environmental concerns while maintaining economic viability will remain a critical challenge for the global desalination market over the coming decade.
Desalination Launches Worldwide
- October 2024 – Beam Global (United States): Launched the BeamWell™ Water Desalination and EV ARC™ delivery system, a portable solution designed to provide clean drinking water, renewable power, and electric vehicle charging for disaster relief and humanitarian operations.
- December 2025 – IDE Technologies (India): Signed a contract with SIPCOT to design, build, and operate a 60 MLD Seawater Reverse Osmosis (SWRO) desalination plant in Tuticorin, Tamil Nadu, in partnership with Jindal Water Infrastructure Limited (JWIL) and Vishnusurya Projects & Infra Ltd. (VPIL).
- January 2026 – Anglian Water (United Kingdom): Awarded TYPSA–Stantec the technical design contract for two major desalination plants in Lincolnshire and Norfolk to strengthen long-term water security in eastern England.
- November 2025 – Saudi Water Authority (Saudi Arabia): Partnered with Ebb Carbon to deploy advanced electrochemical technology aimed at reducing carbon emissions from Saudi Arabia’s large-scale desalination facilities.
- 2025 – ACWA Power (Saudi Arabia): Commissioned the Rabigh 4 Independent Water Plant, a large-scale reverse osmosis desalination facility supplying potable water to the Makkah and Madinah regions.
- 2025 – Veolia Water Technologies (France): Expanded its Barakah desalination project in the United Arab Emirates by deploying advanced reverse osmosis systems with improved energy recovery technology.
- 2024 – SUEZ (France): Introduced a next-generation SeaDAF™ pretreatment solution for seawater desalination plants, improving membrane protection and reducing operating costs for reverse osmosis facilities.
- 2024 – DuPont Water Solutions (United States): Launched new FilmTec™ reverse osmosis membrane elements designed to increase freshwater production while lowering energy consumption in municipal and industrial desalination plants.
- 2024 – Toray Industries (Japan): Released an upgraded high-rejection reverse osmosis membrane series offering improved durability, higher water recovery, and lower operational costs for seawater desalination applications.
- 2025 – Xylem Inc. (United States): Introduced advanced digital monitoring and intelligent automation solutions for desalination plants, enabling real-time performance optimization, predictive maintenance, and improved energy efficiency.
Leading Technology Owing to High Efficiency and Low Energy Consumption in Reverse Osmosis (RO) Desalination
Reverse osmosis (RO) dominates the global desalination market, accounting for more than 65% of installed desalination capacity worldwide, making it the most widely adopted desalination technology. The segment leads due to its superior energy efficiency, lower operating costs, and ability to produce high-quality freshwater compared to conventional thermal desalination technologies. RO systems utilize semi-permeable membranes to remove dissolved salts, minerals, and contaminants from seawater and brackish water, achieving salt rejection rates exceeding 99%. Continuous innovations in membrane materials, energy recovery devices, and AI-enabled plant monitoring have significantly reduced electricity consumption and maintenance costs over the past decade. RO technology is extensively deployed in municipal water supply, industrial water treatment, and large-scale seawater desalination projects across the Middle East, Asia-Pacific, North America, and Europe. Furthermore, increasing integration with renewable energy sources such as solar and wind power is improving the sustainability of RO facilities. As governments continue investing in water security and cost-effective desalination infrastructure, the reverse osmosis segment is expected to maintain its dominant market position throughout the forecast period.
Multi-Stage Flash (MSF) Desalination Preferred for Large-Scale and High-Salinity Applications
Multi-Stage Flash (MSF) desalination remains one of the most established thermal desalination technologies, particularly in energy-rich countries across the Middle East. The technology accounts for approximately 20–25% of global desalination capacity and is widely used for large-scale municipal water production due to its operational reliability and long service life. MSF works by heating seawater and rapidly reducing pressure across multiple stages, allowing water to evaporate and condense into high-purity freshwater. The process performs efficiently with highly saline seawater and can operate continuously for decades with proper maintenance. Countries including Saudi Arabia, the UAE, Kuwait, and Qatar continue to rely on MSF plants because of abundant energy resources and integrated water-power generation facilities. However, MSF requires significantly higher energy consumption than reverse osmosis, resulting in increased operational costs and carbon emissions. Ongoing research focuses on improving thermal efficiency, waste heat recovery, and hybrid desalination systems to reduce energy requirements. Despite competition from RO technology, MSF continues to play a critical role in regions where energy availability supports large-scale thermal desalination.
Expanding Investments to Meet Urban Water Demand in Municipal Desalination
The municipal desalination segment represents the largest application area within the global desalination market, driven by increasing urbanization, population growth, and rising pressure on public water infrastructure. According to the United Nations, over 56% of the global population currently lives in urban areas, a figure expected to approach 68% by 2050, significantly increasing municipal water demand. Governments worldwide are investing heavily in large-scale desalination facilities to provide reliable drinking water and reduce dependence on groundwater and surface water resources. Public-private partnerships (PPPs) are accelerating the construction of advanced desalination plants across the Middle East, Asia-Pacific, Australia, Europe, and North America. Modern municipal plants increasingly incorporate energy-efficient reverse osmosis systems, digital monitoring technologies, and renewable energy integration to improve operational sustainability. Many cities are also expanding desalination capacity to strengthen resilience against droughts and climate-related water shortages. As freshwater availability continues to decline and urban populations expand, municipal desalination is expected to remain the fastest-growing application segment, supported by continuous government funding and long-term water security initiatives.
Largest Feedwater Source Due to Unlimited Ocean Availability
Seawater desalination represents the largest feedwater segment in the global desalination market because oceans contain approximately 97% of the Earth’s total water resources. Countries facing chronic freshwater shortages increasingly rely on seawater desalination to ensure long-term water security. The segment dominates installations across the Middle East, North Africa, Australia, Spain, China, India, and the United States, where coastal populations and industrial activities continue to grow rapidly. Continuous improvements in reverse osmosis membranes, energy recovery systems, and plant automation have substantially reduced the cost of seawater desalination over the last two decades. Governments are investing billions of dollars in mega-scale seawater desalination projects to secure drinking water supplies while reducing dependence on rainfall and groundwater. Despite challenges including high energy requirements, marine ecosystem impacts, and brine disposal management, seawater desalination remains the most practical solution for coastal regions. Increasing adoption of renewable-powered desalination facilities and environmentally friendly brine management technologies is further strengthening the long-term growth potential of the seawater desalination segment.
Cost-Effective Solution for Inland Water Treatment
Brackish water desalination is witnessing strong growth as industries, municipalities, and agricultural sectors seek economical alternatives to seawater desalination. Brackish water typically contains 1,000–10,000 mg/L of dissolved salts, substantially lower than seawater, which averages around 35,000 mg/L, allowing desalination systems to consume significantly less energy. As a result, operational costs for brackish water reverse osmosis plants are considerably lower than those for seawater facilities. The technology is widely used across inland regions where groundwater contains moderate salinity but seawater access is unavailable. Agriculture, mining, food processing, pharmaceuticals, and manufacturing industries increasingly depend on brackish water desalination to secure reliable freshwater supplies. Governments are also investing in decentralized and small-scale brackish water treatment plants to improve rural water access and support regional economic development. Continuous improvements in membrane technology, automation, and energy-efficient pumps are enhancing system performance while reducing maintenance costs. Growing concerns over groundwater depletion and freshwater scarcity are expected to drive sustained expansion of the global brackish water desalination market.
Water Stress Driving Investments in Advanced Desalination in USA
United States desalination market is experiencing steady expansion due to increasing water scarcity, prolonged droughts, and rising municipal and industrial water demand, particularly in California, Texas, Arizona, and other Southwestern states. According to the U.S. Geological Survey (USGS), the United States operates more than 2,000 desalination facilities, treating both seawater and brackish groundwater for municipal, industrial, and agricultural applications. Reverse osmosis (RO) remains the dominant technology because of its high efficiency and lower energy consumption. Growing concerns over declining reservoir levels, groundwater depletion, and climate change have encouraged federal and state governments to invest in desalination infrastructure and water reuse initiatives. Technological advancements in membrane filtration and energy recovery systems continue to improve plant efficiency while lowering operational costs. However, high capital investment, permitting challenges, and environmental concerns related to brine disposal remain key obstacles. In October 2024, Beam Global launched the BeamWell water desalination and electric vehicle delivery system, designed to provide clean drinking water, renewable power, and mobility solutions for humanitarian emergencies and disaster response, highlighting continued innovation within the U.S. desalination sector.
United Kingdom Strengthening Water Resilience Through Strategic Infrastructure Development
United Kingdom desalination market remains relatively small but is gaining importance as climate variability, population growth, and regional water shortages increase pressure on conventional water resources. Although the UK primarily depends on rainfall, reservoirs, and groundwater, the Environment Agency projects that England could face a daily water deficit of approximately 5 billion litres by 2050 without additional water supply measures. Desalination is increasingly being incorporated as a strategic backup water source, particularly in southern and eastern England, where water stress is highest. Modern desalination facilities utilize advanced reverse osmosis systems to improve energy efficiency and minimize environmental impacts while supporting long-term water resilience. Water utilities are integrating desalination into broader resource management strategies alongside water recycling and demand management programs. In January 2026, Anglian Water awarded TYPSA-Stantec the technical contract to develop two new desalination plants in Lincolnshire and Norfolk. These facilities form part of the company’s long-term investment strategy to secure sustainable water supplies for one of the driest regions in the United Kingdom.
India Rapid Urbanization and Industrial Expansion Accelerating Market Growth
India’s desalination market is witnessing rapid growth due to increasing freshwater shortages, rapid urbanization, industrial development, and changing climate conditions. India possesses a coastline exceeding 7,500 kilometers, providing substantial opportunities for seawater desalination, particularly in coastal states such as Tamil Nadu, Gujarat, Andhra Pradesh, and Maharashtra. Declining groundwater availability, irregular monsoon rainfall, and rising municipal water demand have accelerated investments in desalination infrastructure. Reverse osmosis technology dominates the market because of its cost-effectiveness and operational efficiency for both municipal and industrial applications. Government initiatives, public-private partnerships, and infrastructure investments continue to encourage new desalination projects serving residential, industrial, power generation, and refinery sectors. While high energy consumption and operational costs remain challenges, advances in membrane technology and renewable energy integration are improving project economics. In December 2025, IDE Technologies signed a contract with SIPCOT to develop a 60 MLD seawater reverse osmosis desalination plant in Tuticorin, Tamil Nadu, in partnership with Jindal Water Infrastructure Limited (JWIL) and Vishnusurya Projects & Infra (VPIL), strengthening water security in the region.
Saudi Arabia Desalination Supported by Massive Capacity Expansion
Saudi Arabia represents the world’s largest desalination market and remains a global leader in desalinated water production due to its extremely limited natural freshwater resources and growing population. The Kingdom accounts for approximately 22% of global desalinated water production, with desalination supplying a significant share of municipal drinking water across major cities. Under Vision 2030, Saudi Arabia continues investing billions of dollars in advanced reverse osmosis facilities, renewable-powered desalination plants, and modernization of existing infrastructure to improve operational efficiency while reducing carbon emissions. Large-scale projects managed by the Saudi Water Authority (SWA) and other national entities are strengthening long-term water security and supporting industrial development. The country is also emphasizing digital monitoring, energy-efficient membranes, and sustainable brine management technologies to enhance environmental performance. In November 2025, the Saudi Water Authority (SWA) partnered with Ebb Carbon to accelerate the decarbonization of Saudi Arabia’s desalination sector, supporting cleaner desalination technologies while reinforcing the Kingdom’s position as the world’s leading desalination market.
Desalination Market Segments
Technology
- Reverse Osmosis
- Multi-stage flash (MSF) Distillation
- Multi-effect (MED) distillation
- Others
Application
- Municipal
- Industrial
- Others
Water Source
- Seawater
- Brackish Water
- River Water
- Others
Countries
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Thailand
- Malaysia
- Indonesia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Acciona
- Dow
- Evoqua Water Technologies
- Siemens AG
- DuPont
- Doosan Enerbility
- Toray Industries, Inc.
- Xylem
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 203 |
| Market |
US$ Billion |
| Segment Covered |
By Technology, By Application, By Water Source and By Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.