Europe Electric Vehicle Market Report by Product, Range, Vehicle Type, Vehicle Class, Countries and Companies Analysis 2026-2034
Buy NowEurope Electric Vehicle Market Size and Forecast
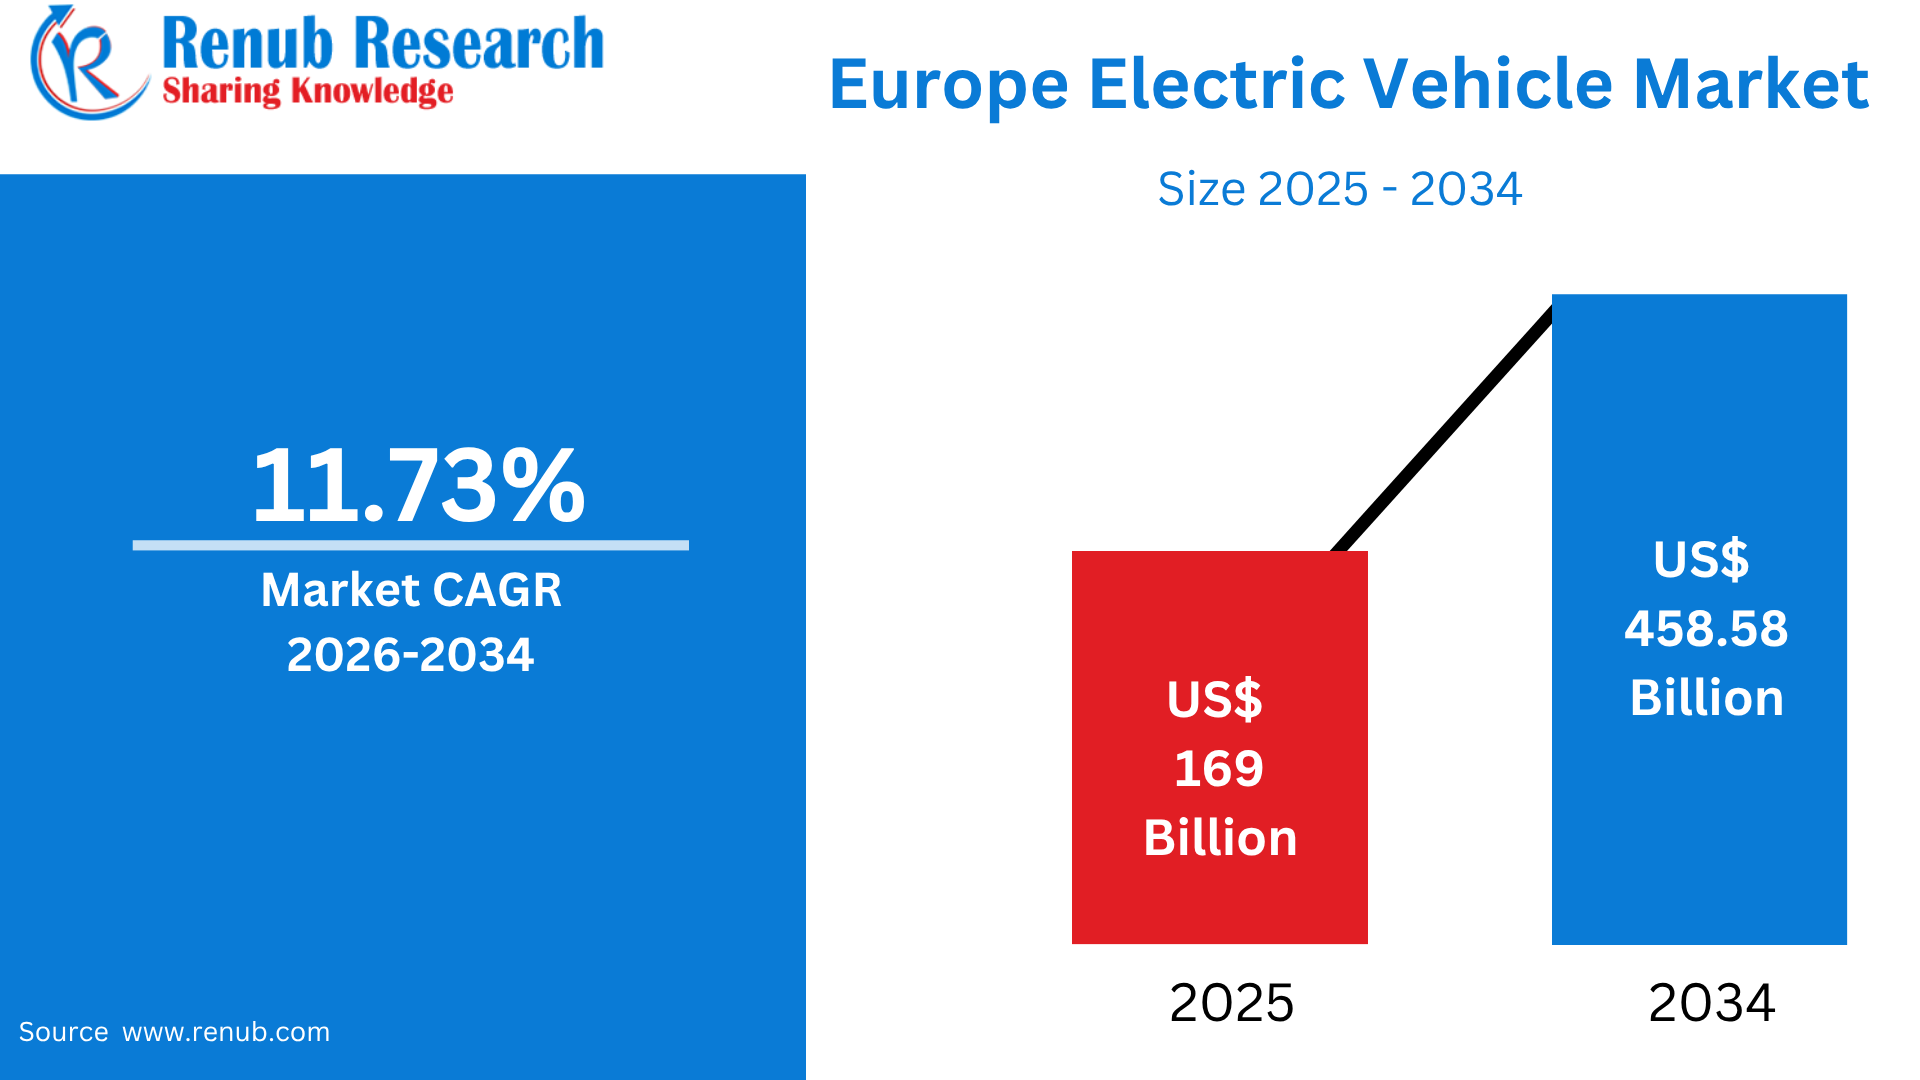
Europe Electric Vehicle Market is projected to expand from US$ 169 billion in 2025 to US$ 458.58 billion by 2034, registering a CAGR of 11.73% during 2026–2034. The market is anticipated to witness strong growth throughout the forecast period, driven by increasing decarbonization efforts, supportive government incentives, and the rapid development of electric vehicle charging infrastructure. Growing consumer awareness of environmental sustainability, combined with rising demand for cleaner and more efficient transportation, is further accelerating EV adoption across Europe.
What is the Europe Electric Vehicle Market and Its Uses & Popularity in Europe
Europe Electric Vehicle (EV) Market comprises vehicles powered fully or partly by electricity, including battery electric vehicles (BEVs), plug-in hybrid electric vehicles (PHEVs), electric buses, vans, and other electrified mobility solutions. EVs are used for private transportation, commuting, commercial deliveries, public transportation, fleet operations, and shared mobility services. They offer an alternative to conventional petrol and diesel vehicles by reducing tailpipe emissions and supporting the transition toward cleaner transportation.
The popularity of EVs has increased significantly across Europe as governments, automakers, businesses, and consumers focus on decarbonization and sustainable mobility. In 2025, battery-electric cars represented 17.4% of new EU car registrations, with 1.88 million new BEVs registered. By the first half of 2026, BEVs had reached 20.7% of new EU car registrations, representing more than 1.22 million vehicles. Growing model availability, improved vehicle technology, charging-network expansion, and financial incentives are supporting wider adoption across European countries.
Top 10 Europe’s Largest BEV Sales in 2025
- Germany: 545,142 BEV sales
- United Kingdom: 473,348 BEV sales
- France: 326,922 BEV sales
- Norway: 172,231 BEV sales
- Netherlands: 156,139 BEV sales
- Belgium: 143,849 BEV sales
- Denmark: 126,542 BEV sales
- Spain: 101,627 BEV sales
- Sweden: 99,732 BEV sales
- Italy: 94,624 BEV sales
BEV Market Share in Europe: 2025 Country Rankings and Milestones
- Norway: 95.9% (Global and European leader)
- Denmark: 68.5%
- Iceland: 41.2%
- Netherlands: 40.2%
- Malta: 37.9%
- Finland: 37.2%
- Sweden: 36.5%
- Belgium: 34.7%
- Luxembourg: 26.9%
- United Kingdom: 23.4%
- Portugal: 23.2%
- Switzerland: 22.8%
- Austria: 21.3%
- France: 20.0%
Growth Drivers of the European Electric Vehicle Market
Government Decarbonization Policies and Emission Targets
Government policies aimed at reducing transportation emissions are a major growth driver for the European electric vehicle market. Road transport represents a significant source of greenhouse-gas emissions in the European Union, encouraging policymakers to accelerate the transition toward low- and zero-emission mobility. The EU has established stringent CO₂ performance standards for new cars and vans, while the regulatory framework has historically targeted a 100% reduction in fleet-wide tailpipe CO₂ emissions from new cars and vans from 2035. These policies encourage automobile manufacturers to expand their EV portfolios and invest in battery technology, software, and electric drivetrains. Incentive programs, tax benefits, and other support measures across individual European markets are also influencing consumer purchasing decisions. ACEA reported that EU battery-electric registrations increased from a 15.6% share in the first half of 2025 to 20.7% in the first half of 2026. Continued regulatory support and fleet-emission requirements are therefore creating a favorable environment for EV adoption and encouraging manufacturers to introduce more affordable and technologically advanced electric models.
Rising Consumer Adoption and Expanding EV Model Availability
Increasing consumer acceptance of electric vehicles is contributing substantially to market expansion across Europe. Buyers are becoming more familiar with battery-electric and plug-in hybrid technologies as manufacturers introduce a broader range of models covering passenger cars, SUVs, compact vehicles, luxury vehicles, and commercial applications. In 2025, battery-electric vehicles accounted for 17.4% of new EU car registrations, compared with 13.6% in 2024, while 1,880,370 new battery-electric cars were registered during the year. The trend strengthened in the first half of 2026, when BEVs reached a 20.7% market share and 1,220,890 new registrations. Germany, France, Italy, Belgium, and the Netherlands have been important contributors to the expanding European EV market. Growing awareness of vehicle operating costs, environmental considerations, improved driving ranges, and technological improvements is supporting consumer interest. At the same time, automakers are increasing the number of electric models available, giving consumers more choices across different price categories and vehicle segments. This combination of greater product availability and improving consumer familiarity is strengthening EV penetration throughout Europe.
Expansion of Charging Infrastructure and Supporting Mobility Ecosystem
The development of charging infrastructure is another important factor supporting electric vehicle adoption across Europe. Convenient access to charging facilities can improve the practicality of EV ownership for households, businesses, commercial fleets, and long-distance travelers. European policies addressing alternative-fuel infrastructure are designed to support the deployment of charging facilities alongside the increasing number of electric vehicles. The European Commission has linked the expansion of recharging infrastructure with the growth of zero-emission mobility and the broader decarbonization of road transport. Growing charging availability at homes, workplaces, shopping locations, public parking areas, highways, and transport hubs is helping integrate EVs into everyday mobility. Improvements in fast-charging technology are also supporting longer-distance travel and reducing charging times. In parallel, digital charging platforms, navigation systems, payment solutions, and connected-vehicle technologies are improving the user experience. As EV registrations continue to rise—with battery-electric cars reaching 20.7% of new EU registrations in H1 2026—the need for an increasingly accessible and reliable charging ecosystem is expected to remain an important market driver.
Challenges of the Europe Electric Vehicle Market
High Initial Vehicle Costs and Affordability Concerns
The relatively high upfront cost of many electric vehicles remains a challenge for broader adoption, particularly among price-sensitive consumers. Although battery costs and EV manufacturing technologies have advanced, electric models can still carry higher purchase prices than comparable conventional vehicles in several segments. The availability and value of financial incentives also vary between European countries, creating differences in affordability and consumer demand. ACEA data illustrates that EV adoption is progressing but remains uneven across powertrain categories: in 2025, battery-electric cars represented 17.4% of EU new-car registrations, while hybrids accounted for 34.5%. This indicates that consumers continue to consider multiple electrified options when purchasing vehicles. EV affordability is also affected by financing costs, insurance, battery size, vehicle range, and charging requirements. Manufacturers are responding by developing smaller and more affordable electric models, while European policy measures increasingly emphasize accessible zero-emission mobility. However, until a wider selection of competitively priced EVs becomes available across passenger and commercial segments, upfront affordability can continue to influence adoption rates.
Charging Accessibility and Infrastructure Gaps
Uneven access to convenient charging infrastructure remains a significant challenge for the European electric vehicle market. Although charging networks are expanding, the availability of chargers can differ considerably between countries, regions, urban centers, rural areas, and residential settings. Consumers without private parking may face additional difficulties because home charging is less convenient when dedicated parking spaces or charging points are unavailable. Long-distance drivers can also be affected by charger availability, charging speed, reliability, and waiting times at high-demand locations. The European Commission has identified the rollout of recharging infrastructure as an important component of the transition toward zero-emission mobility. The continued increase in EV registrations makes infrastructure expansion increasingly important: battery-electric vehicles represented 20.7% of new EU car registrations in the first half of 2026, up from 15.6% during the same period in 2025. Addressing regional infrastructure differences, improving charger reliability, expanding fast-charging networks, and ensuring convenient payment and access systems will remain important for supporting sustained EV adoption across Europe.
Electric Vehicle Launches in Europe
- Renault 5 E-Tech Electric – 2024/2025: Renault launched the Renault 5 E-Tech electric in France in October 2024 and subsequently expanded it across European markets. The compact EV offers an affordable entry point into electric mobility, with a planned starting price of €25,000 before applicable incentives.
- Alpine A290 – 2024: Alpine introduced the A290 as an all-electric performance-oriented compact hatchback for the European market. The model shares the AmpR Small platform with the Renault 5 E-Tech electric and represents Alpine’s move into electric mobility.
- Volkswagen ID.7 Tourer – 2024: Volkswagen launched the ID.7 Tourer as its first all-electric estate car. European pre-sales began in March 2024, with the model offering up to 607 km of WLTP range in its initial configuration.
- BYD Dolphin Surf – 2025: BYD launched the Dolphin Surf in Europe in May 2025, targeting the affordable EV segment. The model was introduced with prices starting at €22,990 and range options of up to 507 km, depending on configuration.
- BMW iX3 – 2025: BMW unveiled the new fully electric iX3 at IAA Mobility in Munich in September 2025. It became the first series-production model based on BMW’s Neue Klasse architecture, featuring sixth-generation eDrive technology and advanced charging capabilities.
- Renault 4 E-Tech Electric – 2025: Renault expanded its European electric portfolio with the Renault 4 E-Tech electric, following the Renault 5. The model targets the compact crossover segment and forms part of Renault’s strategy to accelerate EV adoption in Europe.
- Nissan Leaf – 2026: Nissan introduced the third-generation Leaf in European markets with a crossover-inspired design, 52 kWh and 75 kWh battery options, and a maximum WLTP range of up to 622 km. The new model also adopts CCS charging and supports up to 150 kW DC fast charging.
- Kia PV7 – 2026/2027: Kia unveiled the PV7 electric commercial van at IAA Transportation 2026 in Hannover, Germany. The vehicle is planned for European sales from 2027 and will be available in Cargo and Passenger versions, with battery options of 72 kWh and 96 kWh.
- Volvo XC60 and XC90 Extended-Range Plug-in Hybrids – 2026: Volvo launched updated versions of the XC60 and XC90 with longer electric driving ranges for European and American markets in September 2026. The models combine plug-in hybrid powertrains with increased electric-only capability.
- Volkswagen ID.2all Production Model – 2025/2026: Volkswagen developed the ID.2all as a compact, more affordable electric vehicle aimed at the European market, with the production version planned around the MEB Entry platform. Volkswagen initially targeted a starting price below €25,000 and included the model within its planned expansion of EV offerings.
United Kingdom Government Targets and Accelerating EV Adoption
United Kingdom electric vehicle market is expanding as government decarbonization policies, growing consumer interest, and investments in charging infrastructure accelerate the transition toward cleaner transportation. The UK’s Zero Emission Vehicle (ZEV) Mandate requires an increasing percentage of manufacturers’ new car and van sales to be zero-emission vehicles, reaching 80% for new cars and 70% for new vans by 2030. The mandate is designed to support the government’s wider objective of moving toward zero-emission new vehicles. The UK also recorded strong growth in battery-electric car registrations, with the Society of Motor Manufacturers and Traders (SMMT) reporting that BEVs accounted for 23.4% of new-car registrations in 2025, compared with 19.6% in 2024. Charging infrastructure is expanding alongside demand, with more public chargepoints being installed across residential areas, workplaces, shopping locations, and major road networks. Businesses and fleet operators are also increasing EV adoption as they pursue emissions-reduction targets and operating efficiencies. Continued vehicle launches, improving battery technology, and expanding charging availability are expected to support the UK market over the long term.
Germany Automotive Manufacturing Strength and Growing BEV Penetration
Germany represents one of Europe’s most important electric vehicle markets, supported by its extensive automotive manufacturing ecosystem, engineering capabilities, and investments in electrification. Automakers including Volkswagen, BMW, and Mercedes-Benz are expanding electric model portfolios while investing in batteries, software, charging technologies, and next-generation vehicle platforms. According to the German Federal Motor Transport Authority (KBA), Germany registered approximately 545,100 new battery-electric passenger cars in 2025, giving BEVs a share of around 19% of total new passenger-car registrations. The country is also expanding charging infrastructure to accommodate the increasing number of electric vehicles. Germany’s strong industrial base supports development across the EV value chain, including vehicle manufacturing, battery production, power electronics, and digital mobility services. Consumer demand is supported by a growing selection of electric models across compact, SUV, luxury, and commercial segments. In addition, environmental objectives and European emissions regulations are encouraging manufacturers and fleet operators to accelerate electrification. Continued investment in production capacity, charging networks, batteries, and connected mobility technologies is expected to maintain Germany’s importance within the European EV industry.
France Government Support and Expansion of Sustainable Mobility
France is experiencing continued development of its electric vehicle market as government decarbonization policies, consumer awareness, and investments in charging infrastructure encourage the transition away from conventional combustion-engine vehicles. The country supports EV adoption through environmental policies, company-car taxation measures, purchase incentives for qualifying vehicles, and programs designed to expand low-emission mobility. According to the European Automobile Manufacturers’ Association (ACEA), battery-electric vehicles accounted for approximately 19.9% of new passenger-car registrations in France during 2025, demonstrating the growing role of fully electric vehicles in the national automotive market. France is also strengthening its domestic EV supply chain through investments in battery manufacturing and electric vehicle production. Public charging infrastructure continues to expand across cities, highways, commercial locations, and residential areas, improving accessibility for consumers and fleet operators. French manufacturers are introducing new electric models across compact, passenger, SUV, and commercial categories, while improvements in driving range, charging performance, and connected technologies are increasing product attractiveness. Corporate fleet electrification is another important opportunity as companies pursue emissions-reduction objectives. These developments are expected to support sustained expansion of the French electric vehicle market.
Italy Charging Expansion and Increasing Demand for Low-Emission Mobility
Italy electric vehicle market is developing as environmental awareness, urban emission-reduction measures, and improvements in charging infrastructure encourage consumers and businesses to consider electric mobility. Although Italy has historically recorded a lower BEV penetration rate than several northern European markets, electric vehicle adoption is gradually increasing as the availability of models and charging facilities improves. According to ACEA, battery-electric cars represented approximately 6.2% of new passenger-car registrations in Italy in 2025, indicating continued but comparatively gradual penetration of fully electric vehicles. Government programs and European decarbonization objectives are supporting investments in cleaner transportation, while cities are introducing measures aimed at reducing urban emissions and improving air quality. Charging infrastructure is expanding across metropolitan areas, highways, commercial locations, and other public spaces, helping address one of the key barriers to EV adoption. Automakers and technology companies are also investing in electric powertrains, connected mobility, and charging solutions. Rising consumer interest in fuel efficiency and lower-emission transportation, together with a broader range of electric models, is expected to create additional opportunities for market development. Continued infrastructure deployment and supportive policies will remain important to Italy’s EV transition.
Europe Electric Vehicle Market Segmentation
Product
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicles (HEV)
- plug-in hybrid electric vehicle (PHEV)
Range
- Upto 150 Miles
- 151-300m Miles
- Above 300 Miles
Vehicle Type
- Two-Wheeler
- Passenger Cars
- Commercial Vehicle
Vehicle Class
- Low Priced
- Mid Priced
- Luxury
Countries
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Russia
- Poland
- Greece
- Norway
- Romania
- Portugal
- Rest of Europe
All companies have been covered from 4 viewpoints:
- Overview
- Key Persons
- Recent Development
- Financial Insights
Company Analysis
- Tesla, Inc.
- BMW Group
- BYD Company Ltd.
- Mercedes-Benz Group AG
- Ford Motor Company
- Nissan Motor Co. Ltd
- Toyota Motor Corporation
- Audi AG
Report Details:
| Report Features | Details |
| Base Year |
2024 |
| Historical Period |
2021 - 2024 |
| Forecast Period |
2025 - 2033 |
| Market |
US$ Billion |
| Segment Covered |
Product, Range, Vehicle Type, Vehicle Class and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.