Europe Coffee Market Report by Product Type, Distribution Channel, Countries and Company Analysis 2026-2034
Buy NowEurope Coffee Market Size and Forecast
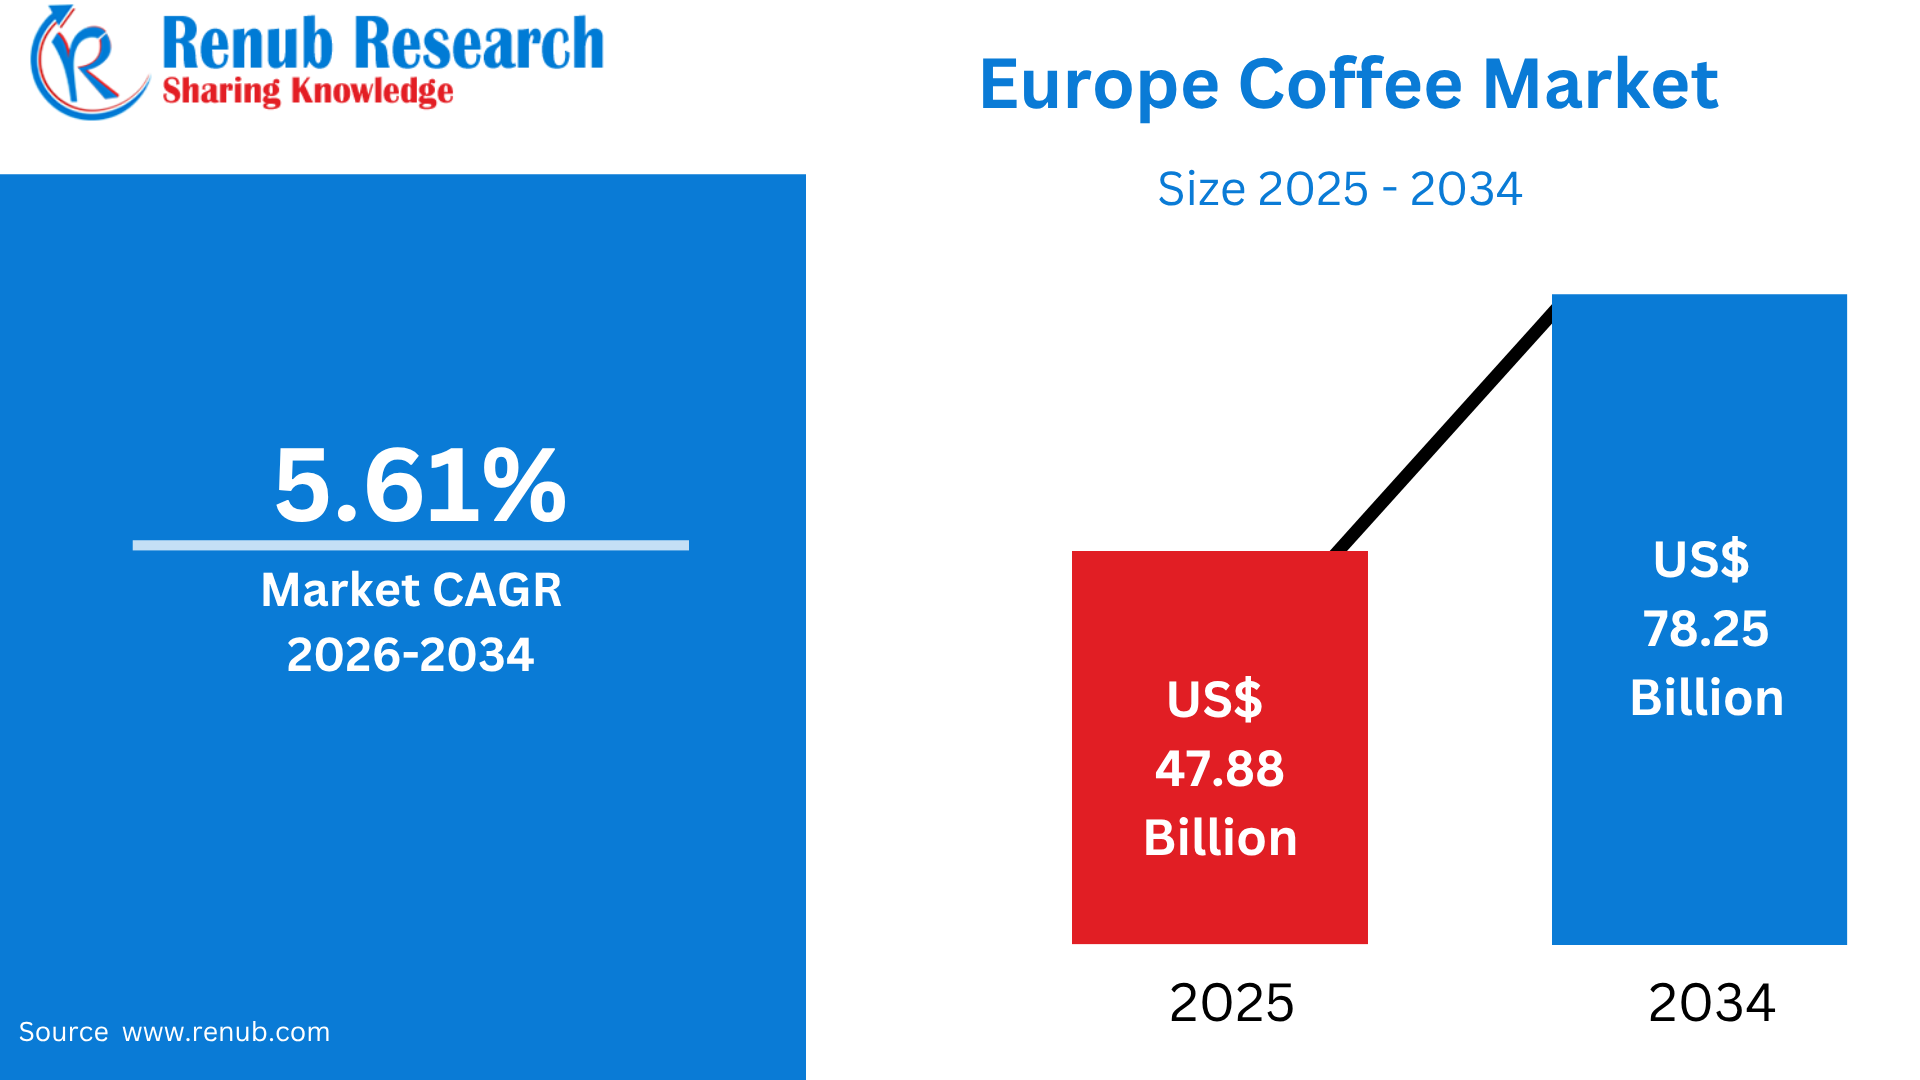
Europe Coffee Market is projected to grow from USD 47.88 Billion in 2025 to USD 78.25 Billion by 2034, registering a CAGR of 5.61% during 2026–2034. The market is expected to expand steadily, supported by strong coffee consumption across European countries, an established café culture, and increasing consumer interest in premium and specialty coffee products. Europe accounts for about 30.7% of global coffee consumption, representing approximately 3.26 million tonnes in 2023/2024, highlighting the region’s substantial and established coffee demand.
What is Coffee and its Uses & Popularity in Europe
Coffee is a widely consumed beverage prepared by roasting and grinding coffee beans, primarily from Arabica and Robusta varieties. It is available in numerous forms, including whole beans, ground coffee, instant coffee, capsules, pods, ready-to-drink beverages, and specialty coffee. In Europe, coffee is consumed at home, offices, cafés, restaurants, hotels, and other foodservice establishments. It is used as a daily energy and refreshment beverage and has also become an important part of social and lifestyle culture.
Europe is the world’s largest coffee-consuming region, accounting for approximately 30.4% of global coffee consumption in 2023/2024, equivalent to around 3.2 million tonnes. European consumers also averaged about 5.7 kg of coffee per person in 2023. Germany, Italy, Spain, and Belgium are among the major European coffee markets. Growing interest in specialty, premium, certified, organic, and sustainably sourced coffee is strengthening the market’s value. The expansion of cafés, premium roasters, coffee chains, home-brewing equipment, and convenient single-serve formats further supports coffee’s popularity across Europe.
Top Coffee Consumption in Europe – 2025
- Luxembourg: Around 20.53 kg per person annually, equivalent to approximately 5.31 cups per day, making it one of Europe’s highest coffee-consuming countries on a per-capita basis.
- Finland: Approximately 14.58 kg per person per year, or about 3.77 cups daily, reflecting the country’s exceptionally strong coffee-drinking culture.
- Sweden: Around 10.00 kg per person annually, equal to roughly 2.59 cups per day.
- Norway: Approximately 9.93 kg per person annually, or around 2.57 cups daily.
- Denmark: About 7.90 kg per person annually, equivalent to approximately 2.04 cups per day.
- Austria: Approximately 7.86 kg per person annually, or about 2.03 cups per day.
- Switzerland: Around 7.23 kg per person annually, equivalent to approximately 1.87 cups daily.
- Netherlands: Approximately 6.91 kg per person annually, or around 1.79 cups per day.
- Greece: About 6.61 kg per person annually, equivalent to roughly 1.71 cups daily.
- Germany: Approximately 6.25 kg per person annually, or about 1.61 cups per day. Germany is also among Europe’s largest coffee markets by total consumption.
- Belgium: Around 6.08 kg per person annually, equivalent to approximately 1.57 cups daily.
- France: Approximately 5.74 kg per person annually, or around 1.48 cups per day.
- Italy: About 5.57 kg per person annually, equivalent to roughly 1.44 cups daily, despite its particularly strong espresso culture.
- Portugal: Approximately 5.45 kg per person annually, or around 1.41 cups daily.
- Spain: Recent industry data indicates average consumption of approximately 4.22 kg per person annually, equivalent to about 562 cups per year.
Growth Drivers of the Europe Coffee Market
Strong Coffee Consumption Culture and Established Café Industry
Europe’s deeply established coffee-drinking culture is a major factor supporting the coffee market. Coffee is integrated into everyday routines, including breakfast, workplace consumption, social gatherings, and café visits. According to the International Coffee Organization (ICO), Europe consumed approximately 53.7 million 60-kg bags of coffee in 2023/24, representing around 30.4% of global coffee consumption. This established consumption base provides manufacturers, roasters, cafés, and retailers with a large and relatively stable customer base. European countries also have distinct coffee traditions, ranging from espresso-based beverages in Italy to filter coffee and specialty preparations in Northern Europe. The growth of independent cafés and specialty coffee shops is encouraging consumers to explore premium beans, alternative brewing methods, single-origin products, and artisanal roasting. Coffee shops are increasingly positioned as social and lifestyle destinations rather than simply beverage outlets. This combination of habitual consumption and expanding café culture supports recurring demand while creating opportunities for premium products and differentiated coffee experiences across European markets.
Premiumization and Rising Demand for Specialty Coffee
Premiumization is increasingly supporting the value growth of the European coffee market, as consumers show greater interest in quality, origin, flavor profiles, ethical sourcing, and specialized preparation methods. The Centre for the Promotion of Imports (CBI) reports that European coffee consumption volumes are expected to remain relatively stable, while market value can increase through premiumization. Europe is also described as an important market for specialty and certified coffee. Consumers are increasingly purchasing single-origin beans, specialty-grade Arabica, organic coffee, fair-trade products, freshly roasted coffee, and premium capsules. In 2024, approximately 70% of Europe’s green coffee imports were Arabica and 30% were Robusta, reflecting the region’s substantial demand for quality-oriented coffee products. Premium cafés and specialty roasters are further stimulating demand by offering distinctive origins, brewing techniques, and customized beverages. This shift enables companies to generate higher revenue from differentiated products even when overall consumption volumes experience limited growth.
Expansion of Convenient and Innovative Coffee Formats
Convenience is another important growth driver as European consumers increasingly seek coffee products that can fit busy lifestyles while maintaining quality and taste. The market has expanded beyond traditional roasted and ground coffee to include instant coffee, coffee pods, capsules, ready-to-drink beverages, cold coffee, and automated home-brewing solutions. Single-serve capsules and pods are particularly suited to consumers seeking quick preparation and consistent flavor at home or in workplaces. Coffee manufacturers are also introducing premium instant products, flavored beverages, functional coffee, and ready-to-drink formats to attract younger and convenience-oriented consumers. Europe’s strong retail infrastructure and developed e-commerce ecosystem provide manufacturers with multiple channels for reaching consumers. In 2024, Europe sourced approximately 3.3 million tonnes of green coffee, demonstrating the scale of its coffee supply and trading network. Germany was identified as Europe’s largest green coffee importer and trade hub, while Belgium also serves as a major distribution center. These established supply and distribution networks facilitate product availability across European markets.
Challenges of the Europe Coffee Market
Volatile Coffee Prices and Supply-Side Risks
Coffee price volatility presents a significant challenge for European coffee companies because Europe relies heavily on imports from producing countries. Changes in weather conditions, crop yields, transportation costs, exchange rates, and global supply-demand conditions can affect raw coffee prices and production costs. The International Coffee Organization maintains coffee price, production, trade, and consumption statistics because these factors are closely interconnected across the global industry. Europe’s dependence on imported green coffee makes the region particularly exposed to international supply disruptions. CBI reported that European green coffee imports declined in 2023 partly because of lower global production, while economic pressures and geopolitical developments also affected trade flows. Higher input costs can raise prices for roasted coffee, capsules, instant coffee, and foodservice beverages, potentially encouraging consumers to shift toward lower-priced alternatives. Companies therefore face pressure to maintain product quality and margins while managing procurement risks. Long-term sourcing relationships, diversified origins, inventory management, and efficient supply chains are increasingly important for mitigating these risks.
Regulatory, Sustainability, and Cost Pressures
Increasing sustainability expectations and regulatory requirements create additional challenges for coffee producers, importers, roasters, and retailers operating in Europe. Consumers increasingly expect coffee to be responsibly sourced, while companies face greater requirements concerning traceability, environmental impacts, certification, and supply-chain transparency. Europe is the world’s largest market for certified coffee, but certification can increase operating expenses because businesses may need additional measures, administration, and audits. At the same time, climate-related risks in coffee-producing regions can affect crop productivity and quality, potentially increasing sourcing costs. European companies must balance sustainability investments with consumer price sensitivity, particularly when inflation and household budgets are under pressure. Smaller coffee businesses may find compliance, certification, documentation, and traceability requirements more difficult to manage than larger companies with established procurement and compliance systems. These factors can increase costs throughout the value chain and complicate market expansion. Nevertheless, sustainability and traceability can also create opportunities for differentiated premium products when consumers are willing to pay more for responsibly sourced coffee.
Coffee Product Launches in Europe
- Nescafé Espresso Concentrated – UK, April 2025
Nestlé introduced Nescafé Espresso Concentrated in the UK as a premium liquid coffee concentrate for preparing café-style iced coffee at home. It was launched in Classic, Vanilla, and Caramel flavors, with each bottle providing 16 servings. - Kenco Iced/Hot Whipped Americano Frappe – UK, June 2025
JDE Peet’s expanded its Kenco portfolio with a Whipped Americano Frappe sachet designed for both hot and cold preparation. The product uses an aerated texture intended to provide a coffee-shop-style experience at home. - Kenco Iced/Hot Creamy Latte – UK, June 2025
Kenco launched its Creamy Latte sachets alongside the Whipped Americano Frappe. The product can be prepared either hot or iced, targeting consumers seeking convenient café-style beverages at home. - Lavazza Tablì – Italy/Europe, April 2025
Lavazza unveiled Tablì, a new single-serve coffee system based on a 100% coffee tab and a specially designed machine. The system was presented during Milan Design Week 2025 and was developed through a five-year R&D program involving more than 15 patents. - Nescafé Espresso Concentrate – France, 2026
Nestlé expanded Nescafé Espresso Concentrate into France as part of its broader European rollout. The liquid concentrate enables consumers to prepare customizable iced coffees without specialized equipment and targets younger consumers. - Nescafé Espresso Concentrate – Germany, 2026
The product was introduced into Germany as part of Nestlé’s expansion of Espresso Concentrate across 10 additional European markets. The range includes Black, Vanilla, and Caramel variants. - Nescafé Espresso Concentrate – Spain, 2026
Spain was included in Nestlé’s 2026 European expansion of Nescafé Espresso Concentrate. The product is positioned around the growing demand for convenient, customizable iced coffee prepared at home. - Nescafé Espresso Concentrate – Switzerland, 2026
Switzerland was among the additional European markets receiving the Nescafé Espresso Concentrate range in 2026. The product is offered in three flavors and is designed for quick preparation of iced coffee with milk or water. - Equator Coffees Cold Brew Blend Brew Bags – UK, September 2024
Equator Coffees launched its Cold Brew Blend in steeped brew bags in collaboration with Steeped Coffee. The format provides a convenient method for preparing cold brew while avoiding the need for specialized brewing equipment. - Nescafé Espresso Concentrate – France, Switzerland, Germany and Other European Markets, 2026
Nestlé expanded the product into a further 10 European markets, including France, Switzerland, Germany, Belgium, the Netherlands, Norway, Denmark, Austria, Spain, and Portugal, following its UK and Ireland launch in 2025. The expansion reflects the company’s focus on year-round iced coffee consumption, particularly among younger consumers.
Rising Preference for Freshly Ground and Premium Coffee
The Europe whole bean coffee market is expanding as consumers increasingly prioritize freshness, aroma, flavor, and higher-quality coffee experiences. Whole beans allow consumers to grind coffee immediately before brewing, supporting greater control over flavor and preparation. The growing specialty coffee movement is reinforcing this trend through demand for single-origin, organic, ethically sourced, and premium Arabica beans. CBI reports that around 70% of European green coffee imports are Arabica, reflecting the importance of quality-oriented coffee in the region. France provides a particularly strong example: whole-bean coffee was the only coffee format to increase in both volume and value in 2023, while demand for single-serve and ground coffee declined. Méo, a French coffee brand, recorded a 45% increase in whole-bean sales volume during the period. Home brewing, espresso machines, grinders, and specialty preparation methods are encouraging consumers to recreate café-style beverages at home. Growing awareness of coffee origin and processing is also encouraging purchases from specialty roasters and premium retailers.
Convenience and Premium Instant Coffee Innovation
The Europe instant coffee market continues to benefit from convenience, quick preparation, affordability, and broad retail availability. Instant coffee requires minimal equipment and can be prepared within seconds, making it suitable for busy households, workplaces, travel, and consumers seeking simple preparation. The category remains particularly relevant in mainstream and value-oriented segments, where supermarkets provide extensive product choices. CBI identifies instant coffee as part of the lower-end European coffee segment, alongside mainstream blends and coffee pads, with supermarkets and service channels representing important routes to consumers. At the same time, manufacturers are moving beyond traditional instant products through premium freeze-dried coffee, improved aroma retention, specialty blends, single-origin offerings, and convenient single-serving formats. Premiumization is important because Europe accounts for 30.7% of global coffee consumption, equivalent to approximately 3.2 million tonnes in 2023/2024. Although specialty and whole-bean coffee are gaining attention, instant coffee maintains demand because it combines accessibility, portability, consistent preparation, and comparatively simple storage.
Dominant Retail Channel and Expanding Private-Label Offerings
Supermarkets and hypermarkets remain major distribution channels for coffee throughout Europe because they provide consumers with broad product selections, competitive pricing, promotional offers, and convenient one-stop shopping. CBI estimates that supermarkets account for more than 50% of coffee sales in most European countries, while Italy records approximately 44% of coffee sales through supermarkets. Spain demonstrates the importance of large-format grocery retail, with supermarkets accounting for 54% of coffee and infusion sales in 2023, while hypermarkets represented another 20%. Retailers are increasingly offering products across mainstream, premium, organic, Fairtrade, Rainforest Alliance, and specialty categories. Private-label coffee is particularly important because it enables retailers to compete across different price points while responding quickly to consumer preferences. In the Netherlands, 72% of coffee consumers purchased at least some of their coffee from service supermarkets in 2024, highlighting the importance of grocery retail for household coffee purchases. Sustainability is also becoming more visible on supermarket shelves, with major European retailers expanding certified and organic coffee selections.
Specialty Roasters and Experiential Coffee Retail
Specialist coffee retailers are gaining importance as European consumers become more interested in coffee quality, origin, brewing techniques, and personalized experiences. These retailers include independent cafés, specialty coffee shops, micro-roasters, dedicated coffee stores, and businesses selling premium beans alongside brewing equipment. CBI reports that interest in specialty coffee is increasing across European markets, particularly among younger consumers, while the growth of small independent roasters, local brands, coffee bars, and trained baristas is supporting the segment. The broader branded coffee-shop market also demonstrates continued expansion: CBI reported 45,008 branded coffee-shop outlets in Europe in 2024, compared with 40,675 in 2021. The United Kingdom had approximately 10,199 outlets, while Germany had 6,533. Specialist retailers differentiate themselves through single-origin beans, tasting sessions, brewing demonstrations, subscriptions, professional equipment, and information about farmers and processing methods. Sustainability is another important selling point, with consumers increasingly interested in traceability and responsible sourcing. This combination of premium products and experiential retail is strengthening specialist coffee channels across European cities.
United Kingdom Specialty Coffee, Home Brewing, and Convenient Formats Drive Demand
The United Kingdom coffee market is supported by a mature café culture, strong instant coffee consumption, and growing interest in specialty products. The expansion of branded coffee chains and independent cafés has encouraged consumers to explore premium beans, specialty beverages, and alternative brewing methods. The UK also has a substantial coffee-shop sector; CBI reported approximately 10,199 branded coffee-shop outlets in the UK in 2024, making it one of Europe’s largest branded coffee-shop markets. Home brewing is another important trend, with consumers purchasing espresso machines, grinders, capsules, and specialty beans to reproduce café-style drinks. Sustainability and ethical sourcing are increasingly relevant, particularly for premium coffee, with certified products gaining visibility. Online retail is also expanding opportunities for subscriptions, direct-to-consumer brands, and specialty roasters. Product innovation remains important: in June 2025, JDE Peet’s introduced Kenco Whipped Americano Frappe and Creamy Latte sachets, designed to be consumed hot or iced. Such innovations provide convenient options for younger consumers while broadening coffee consumption occasions.
Germany Strong Consumption Culture and Growing Specialty Coffee Demand
Germany is one of Europe’s major coffee markets, supported by an established coffee-drinking culture and strong demand for filter coffee, roasted coffee, and whole beans. Coffee is consumed extensively at home, workplaces, cafés, and foodservice establishments, while supermarkets and discounters provide broad access to products across different price points. Germany is also an important coffee trading hub: CBI identifies it as Europe’s largest green coffee importer, with approximately 1.1 million tonnes imported in 2023, representing around 26% of Europe’s total green coffee imports. Specialty coffee is gaining attention as consumers become more interested in quality, origin, freshness, and sustainable sourcing. Organic and certified coffee products are also increasingly visible in retail channels. The development of independent cafés and specialty roasters is creating additional demand for premium beans and alternative preparation techniques. Product innovation is supporting market diversification; in April 2025, Nestlé launched Nescafé Espresso Concentrated in Europe, with Classic, Vanilla, and Caramel variants, with each bottle providing approximately 16 cups. These developments illustrate the continuing diversification of German and European coffee consumption.
Italy Espresso Tradition Meets Premiumization and Home Brewing
Italy has a distinctive coffee culture centered on espresso, cafés, and traditional espresso bars, where consumers value speed, consistency, quality, and familiar preparation methods. Coffee is deeply integrated into everyday routines, with espresso consumed throughout the day in cafés, restaurants, workplaces, and homes. Italy is also a significant coffee-importing and roasting market, with CBI reporting approximately 570,000 tonnes of green coffee imports in 2023, making Italy one of Europe’s major importers. While traditional espresso remains central, consumer interest is gradually expanding toward specialty coffee, single-origin beans, alternative brewing methods, and premium home equipment. The growth of home espresso machines and advanced capsule systems is allowing consumers to reproduce barista-style coffee outside traditional cafés. Sustainability and premium product positioning are also influencing purchasing decisions. Market innovation continues alongside traditional consumption patterns. In April 2025, Lavazza announced Tabli, a capsule system focused on pure coffee. Such developments demonstrate how Italian coffee companies are combining established espresso traditions with new formats and preparation technologies, creating additional opportunities for premium and convenient coffee products.
France Premium Coffee, Specialty Roasters, and Changing Consumption Habits
France has a well-established coffee culture associated with cafés, bistros, espresso, café au lait, and social consumption. At the same time, consumer preferences are evolving toward premium beans, specialty coffee, organic products, and ethically sourced offerings. The specialty segment is benefiting from independent coffee shops and small roasters that emphasize bean origin, roasting methods, freshness, and artisanal preparation. France has also shown notable consumer interest in whole-bean coffee. CBI reported that whole-bean coffee was the only coffee format in France to increase in both volume and value in 2023, while Méo, a French coffee brand, recorded a 45% increase in whole-bean sales volume. Home consumption is another important market feature, with consumers investing in premium coffee machines, grinders, and brewing equipment. E-commerce and specialty online retailers are further improving access to niche coffee products. In May 2024, Fresh Black opened a logistics center in Poland to support European distribution of its specialty coffee products, including whole-bean blends and drip coffee bags. Such developments highlight the increasing availability of specialty and premium coffee products across European markets.
Market Segments
Product Type
- Whole Bean
- Ground Coffee
- Instant Coffee
- Coffee Pods and Capsule
Distribution Channel
On-Trade
Off-Trade
- Supermarkets/Hypermarkets
- Convenience Stores
- Specialist Retailers
- Other Off-trade Channels
Countries
United Kingdom
- Germany
- France
- Russia
- Italy
- Spain
- Rest of Europe
All the Key players have been covered from 5 Viewpoints:
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Company Analysis
- JAB Holding Company
- Nestlé SA
- The Kraft Heinz Company
- J.J. Darboven GmbH & Co. KG
- Strauss Group Ltd
- Melitta Group
- Starbucks Corporation
- Krüger GmbH & Co. KG
- Luigi Lavazza SpA
- Maxingvest AG (Tchibo)
Report Details:
| Report Features | Details |
| Base Year |
2024 |
| Historical Period |
2021 - 2024 |
| Forecast Period |
2025 - 2033 |
| Market |
US$ Billion |
| Segment Covered |
Product Type, Distribution Channel and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.