Biodegradable Plastic Market Report by Material Type, Application, Countries and Company Analysis 2026-2034
Buy NowBiodegradable Plastic Market Size and Forecast
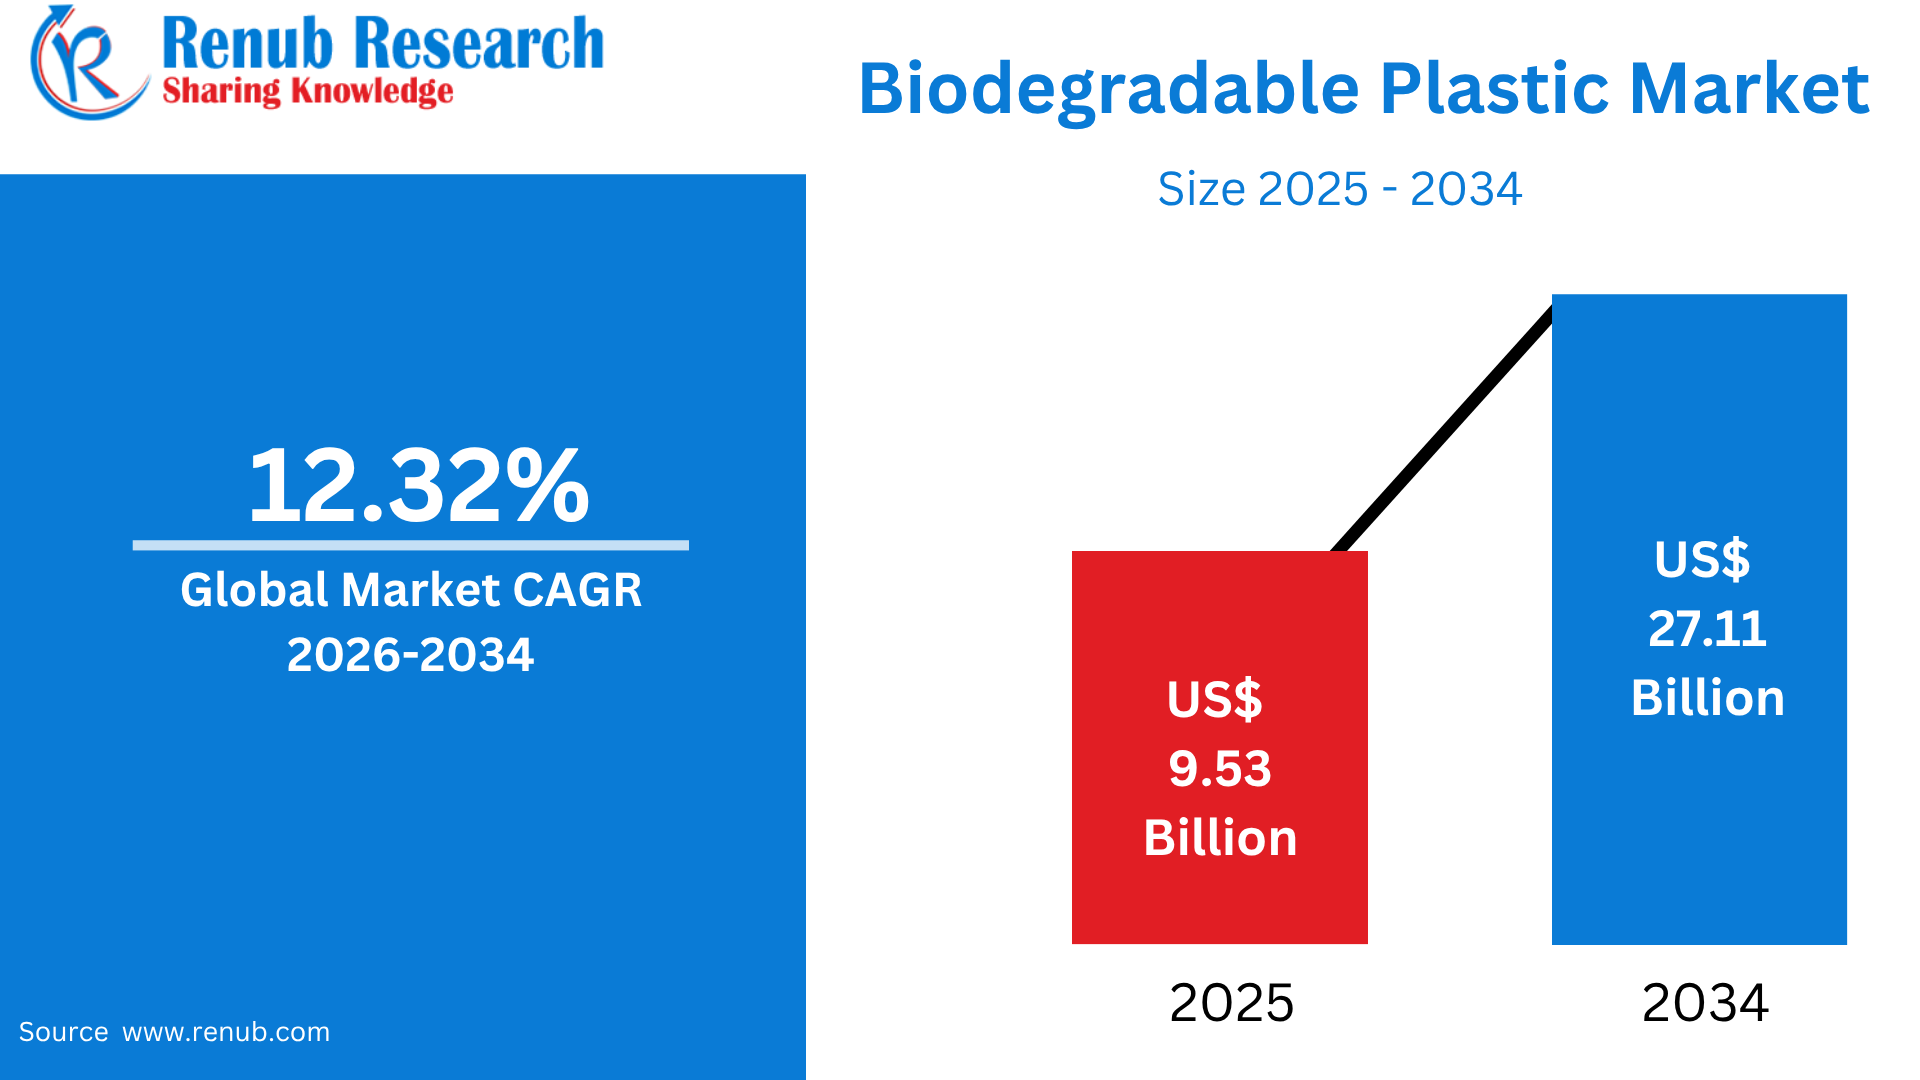
Biodegradable Plastic Market is projected to grow from US$ 9.53 billion in 2025 to US$ 27.11 billion by 2034, registering a CAGR of 12.32% during the forecast period from 2026 to 2034. The market is anticipated to witness significant growth, supported by increasing sustainability initiatives, stringent environmental regulations, and growing consumer awareness regarding eco-friendly products. Rising concerns over plastic pollution and the environmental impact of conventional plastics are encouraging businesses and manufacturers to adopt biodegradable alternatives.
What is Biodegradable Plastic and Its Uses & Popularity Worldwide
Biodegradable plastics are polymer materials designed to break down through the action of microorganisms into natural substances such as carbon dioxide, water, biomass, or other residues under suitable environmental conditions. Common materials include polylactic acid (PLA), polyhydroxyalkanoates (PHA), polybutylene adipate terephthalate (PBAT), polybutylene succinate (PBS), and starch-based blends. These materials are increasingly used as alternatives to conventional petroleum-based plastics in applications where reducing persistent plastic waste is particularly important. Packaging represents the leading application, covering food containers, films, bags, pouches, trays, disposable foodservice products, and other consumer packaging.
Biodegradable plastics are also used in agriculture, textiles, consumer products, automotive components, and selected medical applications. European Bioplastics reports that packaging represented 41.3% of global bioplastics production capacity in 2025, equivalent to approximately 0.95 million tonnes. Worldwide popularity is increasing as governments, manufacturers, retailers, and consumers seek lower-impact material solutions. Mainland China is currently the largest producer and consumer of biodegradable polymers, while Europe remains a major market driven substantially by regulatory initiatives.
Global Biodegradable Plastics Market Shares of Leading Manufacturers (2024)
·Kingfa Sci. & Tech. – ≈23.0%
- Main Polymer: PBAT
- Anchor Asset/Brand: ~320 kt PBAT base in Zhuhai, China
- Position: Largest estimated manufacturer share of global biodegradable plastics capacity in 2024.
·Novamont – ≈10.8%
- Main Polymers: PBAT/starch blends, Mater-Bi, and biopolyesters
- Anchor Asset/Brand: ~150 kt Mater-Bi and Origo-Bi capacity in Italy
- Position: Major European producer specializing in biodegradable and bio-based polymer solutions.
·NatureWorks – ≈10.8%
- Main Polymer: PLA
- Anchor Asset/Brand: 150 kt Ingeo® production capacity in Nebraska, USA
- Position: One of the leading global PLA manufacturers, with Ingeo® serving packaging and other applications.
·TotalEnergies Corbion – ≈5.4%
- Main Polymer: PLA
- Anchor Asset/Brand: 75 kt Luminy® capacity in Thailand
- Position: Major international PLA producer supplying biodegradable polymer materials for multiple applications.
·BASF – ≈5.3%
- Main Polymer: PBAT
- Anchor Asset/Brand: ecoflex® / ecovio®; Ludwigshafen PBAT facility
- Position: Established producer of biodegradable polymer solutions, particularly for packaging and agricultural applications.
·PTT MCC Biochem (GC × Mitsubishi Chemical) – ≈1.4%
- Main Polymer: PBS
- Anchor Asset/Brand: 20 kt BioPBS™ capacity in Thailand
- Position: Key producer of PBS-based biodegradable polymers used in packaging, foodservice, and other applications.
·Danimer Scientific – ≈0.7%
- Main Polymer: PHA
- Anchor Asset/Brand: ~9 kt capacity in the USA
- Position: Specialized PHA producer, with Nodax® targeting compostable packaging and related applications.
·CJ Biomaterials (CJ CheilJedang) – ≈0.4%
- Main Polymer: PHA
- Anchor Asset/Brand: ~5 kt a-PHA line in Indonesia
- Position: Emerging global PHA manufacturer offering PHACT™ materials for sustainable packaging and other applications.
Growth Drivers of the Biodegradable Plastic Market
Rising Environmental Concerns and Plastic-Waste Reduction
Growing concerns about persistent plastic pollution are accelerating the transition toward biodegradable and compostable alternatives. Conventional plastics can remain in the environment for long periods, increasing pressure on governments and businesses to reduce dependence on fossil-based materials. This environmental focus is supporting investment in PLA, PHA, PBAT, PBS, and starch-based polymers. European Bioplastics estimates that global biobased plastics production capacity will increase from 2.31 million tonnes in 2025 to approximately 4.69 million tonnes by 2030, effectively doubling within five years. Although biobased plastics currently represent only around 0.5% of the approximately 431 million tonnes of plastics produced globally each year, their capacity is expanding rapidly. Packaging is particularly important because biodegradable materials can provide alternatives for applications where food contamination or mixed waste makes conventional mechanical recycling difficult. Consequently, sustainability commitments from brands, retailers, and manufacturers are creating additional demand for biodegradable plastic materials worldwide.
Government Regulations and Sustainability Policies
Regulatory initiatives aimed at reducing plastic pollution are becoming an important growth catalyst for biodegradable plastics. Governments are implementing restrictions on selected single-use plastics, introducing extended producer responsibility requirements, promoting compostable materials, and establishing broader circular-economy policies. Europe remains particularly influential, with legislation such as the Waste Framework Directive and Packaging and Packaging Waste Directive supporting changes in packaging design and waste management. China is also a major growth market, with legislation designed to reduce plastic waste contributing significantly to the expansion of biodegradable polymer capacity. In India, plastic-packaging regulations include specific provisions for compostable plastic packaging and progressively increasing recycling requirements. These regulatory developments encourage manufacturers to replace or redesign conventional plastic products while stimulating investment in biodegradable polymer production. As environmental regulations become more stringent across major economies, companies are increasingly incorporating sustainable materials into packaging and product-development strategies.
Expanding Sustainable Packaging and Consumer Demand
The rapid expansion of sustainable packaging is creating substantial opportunities for biodegradable plastics across food and beverage, retail, personal care, pharmaceutical, and foodservice industries. Packaging remains the largest application for bioplastics, accounting for 41.3% of global bioplastics production capacity in 2025, or approximately 0.95 million tonnes. Biodegradable materials are increasingly used in bags, pouches, films, trays, containers, cups, and foodservice products as companies respond to consumer expectations for environmentally responsible packaging. In addition, growing brand commitments to sustainability are encouraging manufacturers to develop packaging with improved compostability, barrier properties, durability, and shelf life. Increasing awareness among consumers further supports adoption, particularly in developed markets where sustainability influences purchasing decisions. This combination of corporate sustainability targets, packaging innovation, and consumer preference is expected to strengthen biodegradable plastic demand worldwide.
Challenges of the Biodegradable Plastic Market
High Production Costs Compared with Conventional Plastics
The relatively high production cost of biodegradable plastics remains a major barrier to widespread adoption. Conventional petroleum-based plastics benefit from highly established manufacturing infrastructure, large production volumes, mature supply chains, and relatively inexpensive fossil-based feedstocks. In comparison, biodegradable and bio-based polymers can require specialized raw materials, processing technologies, and production facilities. The European Commission’s Joint Research Centre notes that recycled and bio-based alternatives can face production costs approximately 1.5 to 2 times higher than fossil-based alternatives. This cost differential can discourage adoption in price-sensitive applications, particularly where manufacturers compete primarily on product cost rather than environmental performance. Smaller producers may also face difficulties achieving economies of scale because biodegradable polymer production remains considerably smaller than conventional plastic manufacturing. Although technological improvements, increasing production capacity, and process optimization are expected to reduce costs over time, the price gap remains an important challenge. Greater investment in manufacturing efficiency, feedstock availability, research, and large-scale production will be necessary to improve the economic competitiveness of biodegradable plastics.
Limited Composting Infrastructure and End-of-Life Management
The environmental benefits of biodegradable plastics depend heavily on appropriate waste-management and disposal conditions. Not all biodegradable plastics break down rapidly in natural environments, and some require controlled industrial composting facilities to achieve the intended degradation. Limited availability of composting infrastructure therefore restricts adoption in several regions. Industry discussions have highlighted fragmented regulations, limited composting capacity, and labeling challenges as important barriers to effective end-of-life management. Confusion between terms such as biodegradable, compostable, bio-based, and recyclable can also lead to improper disposal and contamination of recycling streams. In addition, collection systems must be capable of separating biodegradable materials from conventional plastics and directing them toward suitable treatment facilities. These infrastructure limitations can reduce the real-world environmental benefits of biodegradable products and increase costs for waste-management operators. Expanding industrial composting networks, improving product labeling, harmonizing standards, and educating consumers about appropriate disposal methods will therefore be essential for supporting the long-term growth of the biodegradable plastic market.
Bioplastics Product Launches Worldwide
- 1. Emirates Biotech – Embio PLA Biopolymer (UAE, 2025): Emirates Biotech launched Embio, a plant-based PLA biopolymer range designed to provide a sustainable alternative to conventional plastics, with applications across packaging and other plastic products.
- 2. TripleW – Food-Waste-Based PLA (Global, 2025): TripleW introduced a PLA bioplastic produced from food waste, representing a circular approach to biopolymer production and reducing dependence on conventional fossil-based feedstocks.
- 3. BASF – Expanded ecovio® Biodegradable Mulch Film Portfolio (Global, 2025): BASF expanded its ecovio® biodegradable mulch-film portfolio, targeting agricultural applications in Asia and Latin America and supporting more sustainable crop-production practices.
- 4. Novamont – Marine-Biodegradable Film (Italy/Global, 2025): Novamont introduced a new marine-biodegradable film designed to degrade in marine environments, expanding the potential applications of biodegradable materials beyond conventional composting systems.
- 5. CJ Biomaterials – PHA Extrusion-Coating Platform (South Korea/Global, 2025): CJ Biomaterials launched a PHA extrusion-coating platform for paper and board applications and introduced PHACT™ masterbatch solutions, supporting compostable packaging development.
- 6. Lubrizol – Carbopol® BioSense™ & Sensomer™ Cassia 115 (Global, 2025): Lubrizol introduced new readily biodegradable polymer solutions, including Carbopol® BioSense Polymer and Sensomer™ Cassia 115 Polymer, targeting sustainable formulations and consumer-product applications.
- 7. BioPak – Home-Compostable PHA Cups (Australia, 2024): BioPak unveiled home-compostable PHA cups, representing an application of PHA bioplastics in foodservice products and expanding compostable alternatives for disposable beverage packaging.
- 8. CJ Biomaterials – PHACT™ Compostable Film Compounds (Global, 2024): CJ Biomaterials introduced two PHACT™ PHA-based compounds designed for compostable film packaging, strengthening its portfolio of PHA materials for flexible packaging applications.
- 9. Danimer Scientific & Ningbo Homelink – Home-Compostable PHA Extrusion-Coating Biopolymer (USA/China, 2024): Danimer Scientific and Ningbo Homelink announced the commercial launch of a home-compostable PHA extrusion-coating biopolymer, aimed at packaging and coated-paper applications.
- 10. CU & CJ Biomaterials – Compostable PHA-Coated Noodle Cup (South Korea, 2024): South Korean convenience-store chain CU launched a noodle cup incorporating CJ Biomaterials’ compostable and biodegradable PHA coating, demonstrating the use of PHA in commercial food packaging.
Strong Demand for Sustainable Packaging Supports USA Market Expansion
United States biodegradable plastic market is expanding as businesses and consumers increasingly seek alternatives to conventional petroleum-based plastics. Demand is particularly strong in packaging, food and beverage, retail, healthcare, and foodservice applications, where companies are under growing pressure to reduce plastic waste and improve sustainability performance. Regulatory initiatives, corporate sustainability commitments, and advances in PLA, PHA, PBAT, and other biodegradable materials are supporting market development. Manufacturers are also investing in materials that provide improved barrier properties, durability, and processing performance while maintaining environmental benefits. The growth of sustainable packaging is expected to remain a major opportunity as U.S. brands seek to balance functionality, regulatory compliance, and consumer expectations. Continued technological innovation and increasing production capacity should further strengthen adoption across diverse end-use industries. Innovation is becoming an important factor in the U.S. biodegradable plastics industry as manufacturers seek to improve material performance and reduce dependence on fossil-based feedstocks. Companies are developing biodegradable products using renewable resources, including plant-based and bio-derived raw materials, for packaging, foodservice, agriculture, and consumer applications. The market also benefits from the presence of established biopolymer producers and research institutions capable of developing new formulations and processing technologies. Product introductions such as new biodegradable packaging materials and plant-derived plastic alternatives demonstrate the industry’s focus on commercializing sustainable solutions.
Strong Environmental Regulations Encourage Sustainable Plastic Alternatives in United Kingdom
United Kingdom biodegradable plastic market is benefiting from stringent environmental policies, consumer awareness, and the country’s broader transition toward a circular economy. Regulations targeting single-use plastics are encouraging businesses to consider reusable, recyclable, compostable, and biodegradable alternatives. In England, regulations prohibit the supply of several single-use plastic products, including plastic cutlery, balloon sticks, drink stirrers, and expanded or extruded polystyrene food and drink containers. Importantly, the restrictions also cover products described as biodegradable, compostable, and recycled plastics for certain categories. The UK’s packaging policies are also increasing pressure on businesses to improve material sustainability and recycling performance. As of August 2026, 5,142 businesses were registered for the UK’s Plastic Packaging Tax, while 51% of plastic packaging tonnage outside the taxable portion met the 30% or higher recycled-plastic threshold. These regulatory measures are encouraging manufacturers to reconsider material selection and packaging design. Consequently, demand for advanced biodegradable and compostable materials is expected to grow where they can provide appropriate performance and meet specific environmental requirements. Packaging remains an important opportunity for biodegradable plastics in the United Kingdom because brands are under increasing pressure to reduce the environmental impact of disposable products. The UK’s household waste recycling rate reached 44.6% in 2023, up from 44.1% in 2022, demonstrating continued attention to resource recovery and waste management. Retailers, foodservice companies, and consumer-goods manufacturers are increasingly evaluating alternative packaging materials that can reduce dependence on conventional plastics.
India Rapid Growth in Bioplastics Creates Significant Market Potential
India represents a high-growth opportunity for biodegradable plastics because of increasing plastic-waste concerns, regulatory initiatives, expanding consumer awareness, and rising demand for sustainable packaging. The market is developing across packaging, food and beverage, e-commerce, agriculture, retail, personal care, and consumer goods. According to Energy Alternatives India (EAI), India’s bioplastic products market was estimated at Rs. 4,069 crore (US$457.19 million) in FY25 and could reach approximately Rs. 32,500 crore (US$3.65 billion) by FY35, implying growth of around 23% between 2025 and 2035. The opportunity is particularly significant in packaging, where technical studies indicate that bio-based packaging products could potentially replace 75% or more of conventional packaging types when supportive standards and take-back systems are available. Government measures restricting selected single-use plastics are encouraging manufacturers to explore alternative materials. At the same time, domestic investment in biopolymer production and processing is increasing. These factors are positioning India as an important emerging market for biodegradable and bio-based plastics, although cost, infrastructure, certification, and end-of-life management remain important considerations. India’s rapidly expanding consumer economy is creating additional opportunities for biodegradable plastics, particularly in applications where packaging is used extensively. Food delivery, e-commerce, organized retail, personal care, and packaged foods are encouraging companies to introduce more sustainable packaging formats. India’s biodegradable plastics landscape is strongly influenced by the Plastic Waste Management (PWM) Rules, which have progressively shifted the country’s approach from waste disposal toward lifecycle management and producer responsibility. The PWM Rules, 2016 established the foundation for Extended Producer Responsibility (EPR), placing greater responsibility on producers, importers, and brand owners for managing plastic packaging waste. Subsequent amendments strengthened registration, compliance, and management requirements. The 2018 amendments further emphasized the phase-out of non-recyclable multilayered plastic materials and compliance by producers and brand owners. The 2022 framework strengthened outcome-oriented requirements through recycling and reuse obligations, recycled-content provisions, and environmental compensation mechanisms. More recent amendments have further strengthened requirements related to biodegradable plastics, including certification, reporting, and transparency around production and waste management.
United Arab Emirates Government Plastic Restrictions Accelerate Demand for Sustainable Alternatives
UAE biodegradable plastic market is gaining momentum as federal and emirate-level policies increasingly target single-use plastic consumption. Dubai’s Executive Council Resolution No. 124 of 2023 established a phased approach to restricting single-use products. The policy began with plastic bags in January 2024, expanded to other single-use bags in June 2024, and subsequently covered additional products such as Styrofoam cups and food containers, plastic straws, cotton buds, stirrers, and table covers. The final phase covering products including plates, food containers, tableware, and beverage cups and lids took effect in January 2026. These regulations are creating opportunities for sustainable material suppliers while encouraging businesses to redesign disposable products. However, the UAE’s approach also demonstrates that biodegradable materials are not automatically exempt from plastic restrictions. The UAE’s sustainability initiatives are supported by measurable reductions in conventional single-use plastic consumption. In Abu Dhabi, the Environment Agency–Abu Dhabi reported that the emirate’s single-use plastic bag ban had saved 364 million bags by December 2024, equivalent to approximately 2,400 tonnes of plastic and an estimated 547,000 tonnes of greenhouse-gas emissions. The agency also reported that more than 130 million single-use plastic bottles had been collected through its bottle-return and recycling initiatives, demonstrating growing participation in alternative waste-management systems. These initiatives are encouraging retailers, foodservice operators, hotels, restaurants, and other businesses to reassess packaging and disposable-product choices. The UAE’s large tourism and hospitality sector provides an additional application opportunity for sustainable packaging, particularly food containers, cups, bags, and service products.
Recent Developments in Biodegradable Plastic Market
- In In May 2025, NEQASTM-OCEAN, a cellulose acetate resin, was used by Teijin Frontier to create biodegradable straws. The straws were made for jelly and bubble tea, combining marine degradability and transparency. They improved Teijin's THINK ECO strategy and decreased plastic trash that ends up in the ocean, earning them certification from the Japan Bio Plastics Association.
- Amcor PLC expanded its global packaging presence and strengthened its capacity to provide sustainable and biodegradable packaging solutions in April 2025 when it completed its all-stock acquisition of Berry Global, which was valued at USD 8.4 billion.
- NatureWorks LLC strengthened its position in the market by launching their new "Ingeo Extend" PLA platform in March 2025, which offers greater biodegradation and film-making efficiency.
Biodegradable Plastic Market Segments
Material Type
- Polybutylene adipate Terephthalate (PBAT)
- Polybutylene Succinate (PBS)
- Polylactic Acid (PLA)
- Polyhydroxyalkanoate (PHA)
- Starch Blends
- Others
Application
- Packaging
- Agriculture
- Consumer Goods
- Others
Countries
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Thailand
- Malaysia
- Indonesia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Company Analysis:
- Total Corbion
- Mitsubishi Chemical Holding Corporation
- Toray Industries
- BASF SE
- GREEN DOT BIOPLASTICS
- Amcor Limited
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Material Type, Application, and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Key Questions Answered in Report:
- What will be the market size of the biodegradable plastic industry by 2033?
- What is the current market size of biodegradable plastics in 2024?
- What is the expected CAGR for the biodegradable plastic market from 2025 to 2033?
- Which factors are driving the growth of the biodegradable plastic market globally?
- What are the key challenges faced by the biodegradable plastic industry?
- Which material type holds the largest share in the biodegradable plastic market?
- What are the main applications of biodegradable plastics across industries?
- How are government regulations influencing the adoption of biodegradable plastics?
- Which countries are the major markets for biodegradable plastics?
- Who are the key players in the global biodegradable plastic market, and what are their recent developments?
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.