Asia Pacific Soup Market Report by Type, Category, Distribution Channel, Countries and Companies Analysis 2026-2034
Buy NowAsia Pacific Soup Market Size and Forecast
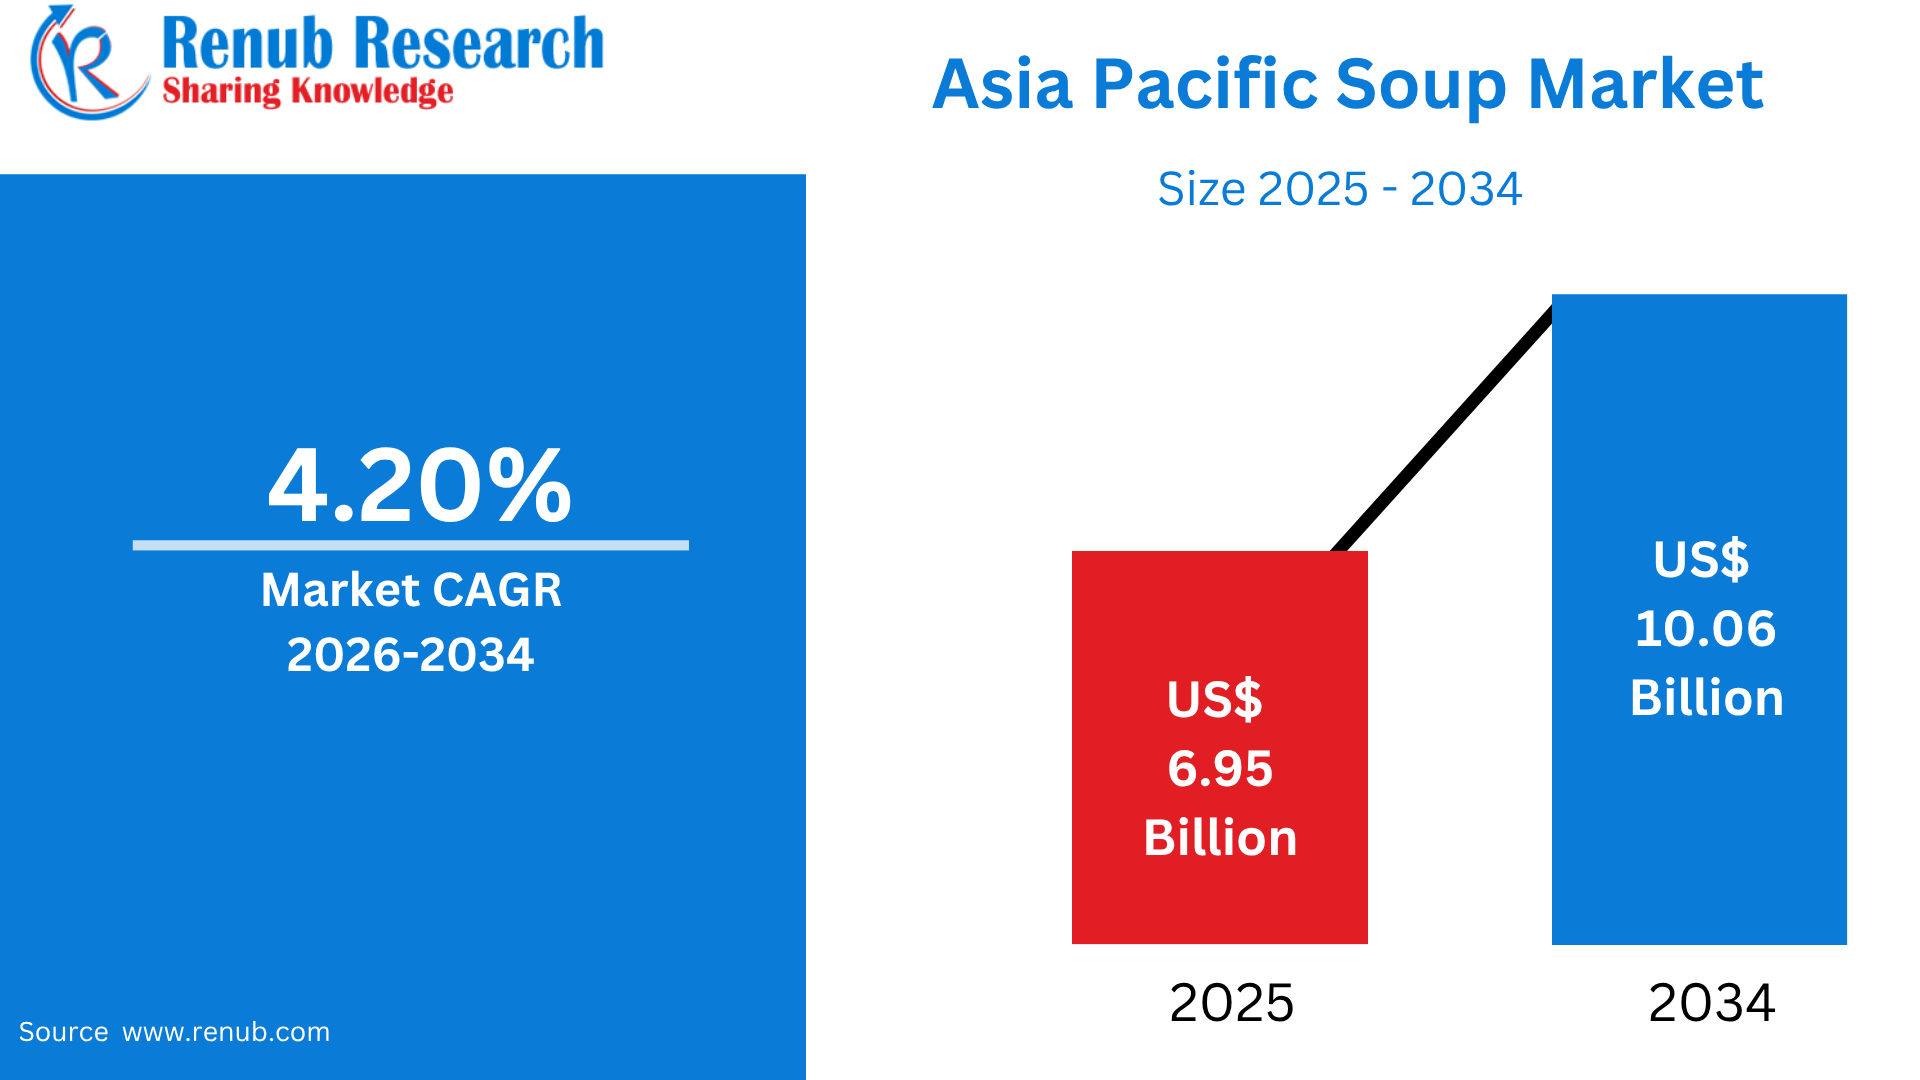
Asia Pacific Soup Market is poised for steady expansion throughout the forecast period, supported by increasing consumer preference for convenient, ready-to-eat, and easy-to-prepare food products. The market is projected to increase from US$ 6.95 Billion in 2025 to US$ 10.06 Billion by 2034, registering a Compound Annual Growth Rate (CAGR) of 4.20% during 2026–2034. Rapid urbanization, evolving lifestyles, rising health consciousness, and the growing presence of modern retail and e-commerce platforms are driving market growth.
What is the Asia Pacific Soup Market and What Are Its Uses & Popularity?
Asia Pacific Soup Market comprises the production, distribution, and consumption of soup products in countries including China, Japan, India, South Korea, Australia, Thailand, Indonesia, and other regional economies. Soup is a liquid or semi-liquid food prepared from ingredients such as vegetables, legumes, meat, seafood, noodles, grains, herbs, and broth. Products are available in multiple formats, including instant, dehydrated, canned, chilled, frozen, and ready-to-eat varieties.
Soup is used as an appetizer, light meal, side dish, nutritional food, and convenient snack. Its popularity across Asia Pacific is supported by strong traditional consumption patterns, particularly in China, Japan, South Korea, and Southeast Asia, where soups are integrated into everyday cuisine. Rising urbanization and changing lifestyles are also increasing demand for convenient packaged formats. Asia Pacific’s urban population reached approximately 2.5 billion in 2023 and is projected to reach 3.4 billion by 2050, supporting demand for time-saving foods. Health-conscious consumers are additionally showing interest in vegetarian, low-sodium, organic, protein-rich, and nutrient-enriched soups.
Growth Drivers of the Asia Pacific Soup Market
Rising Urbanization and Demand for Convenient Foods
Rapid urbanization, longer working hours, dual-income households, and changing eating habits are increasing demand for convenient meal solutions across Asia Pacific. Consumers increasingly prefer foods that require limited preparation while providing satisfying taste and nutritional value. Instant, dehydrated, chilled, and ready-to-eat soups are particularly suited to these requirements because they can be prepared quickly and consumed at home, workplaces, or while traveling. Asia Pacific’s urban population was approximately 2.5 billion in 2023 and is expected to reach 3.4 billion by 2050, creating a substantial consumer base for convenience-oriented food products. Countries such as China, India, Japan, South Korea, Indonesia, and Vietnam are experiencing lifestyle changes that favor packaged foods. The growth of quick-commerce and online grocery services is further strengthening accessibility. In addition, instant soups are gaining traction among students, office workers, and younger consumers seeking affordable and easy-to-prepare meals. This combination of urban population growth, limited meal-preparation time, and increasing preference for convenience is expected to remain a major catalyst for the regional soup market.
Growing Health Awareness and Demand for Nutritious Soups
Increasing consumer awareness of healthy eating is encouraging manufacturers to develop soups positioned around nutrition, wellness, and functional benefits. Consumers are increasingly seeking products containing vegetables, legumes, protein, vitamins, minerals, and other beneficial ingredients while showing greater interest in vegetarian and plant-based formulations. Manufacturers are also responding through reduced-sodium, organic, high-protein, fortified, and clean-label products. For example, Hikari Miso introduced a freeze-dried miso soup with 25% less salt than its regular counterpart, illustrating how brands are adapting products to health-conscious consumers. Japan’s aging population is another important factor, as older consumers increasingly seek convenient foods aligned with nutritional requirements. Health-focused product innovation is therefore helping transform soup from a simple comfort food into a convenient nutritional meal, supporting premiumization and broader consumption across Asia Pacific.
Expansion of Modern Retail and Online Distribution
The expansion of supermarkets, hypermarkets, convenience stores, and e-commerce platforms is significantly improving the availability of soup products across Asia Pacific. Modern retail allows manufacturers to offer wider product ranges, including premium, imported, organic, chilled, and specialty soups, while online channels provide consumers with greater convenience and product choice. The rapid development of digital grocery shopping is particularly important in China, India, Southeast Asia, and other emerging markets. E-commerce platforms also enable brands to reach consumers beyond major metropolitan areas and use promotions, subscriptions, and targeted digital marketing to encourage purchases. Meanwhile, convenience stores provide easy access to single-serving instant and ready-to-eat soups for commuters and office workers. The combination of physical retail expansion and digital commerce is therefore increasing product visibility, accessibility, and consumer adoption throughout the region.
Challenges of the Asia Pacific Soup Market
High Sodium Content and Health Concerns
One of the major challenges facing the Asia Pacific soup market is consumer concern regarding the nutritional composition of processed and instant soup products, particularly their sodium content. Many instant and packaged soups traditionally rely on salt and seasoning blends to enhance flavor and extend product appeal. However, increasing awareness of healthy diets is making consumers more cautious about excessive sodium consumption. This creates pressure on manufacturers to reformulate products without compromising taste, shelf life, or affordability. The challenge is particularly relevant in markets where instant soups are positioned as inexpensive convenience foods. Manufacturers are responding by introducing reduced-sodium, natural-ingredient, organic, and clean-label alternatives. For instance, Hikari Miso’s Mainichi Miso Soup Mild Sodium Freeze-dried Miso contains 25% less salt than its regular counterpart, demonstrating the direction of product innovation. Nevertheless, reducing sodium can increase formulation costs and may require alternative flavoring ingredients. Companies must therefore balance health expectations with taste preferences, pricing, and product stability. Growing scrutiny of processed foods could influence purchasing behavior and increase reformulation requirements across the regional soup industry.
Diverse Consumer Preferences and Rising Production Costs
Asia Pacific region represents a highly diverse consumer market, creating significant challenges for soup manufacturers attempting to develop products suitable for multiple countries. Taste preferences vary substantially across China, Japan, India, South Korea, Thailand, Indonesia, and Australia. Consumers may prefer spicy, sour, umami, miso, curry, seafood, vegetable, or meat-based flavors depending on local culinary traditions. Manufacturers therefore need to localize recipes, packaging sizes, ingredients, and pricing strategies, increasing product-development and marketing complexity. At the same time, fluctuating prices of vegetables, grains, meat, seafood, spices, packaging materials, energy, and transportation can put pressure on production margins. The challenge is particularly significant for chilled and fresh soup products because they require stronger cold-chain infrastructure. Market research indicates that shelf-stable soup remained the dominant format, while chilled soup is growing as cold-chain infrastructure improves. Companies must consequently balance affordability with quality, localization, packaging innovation, and distribution efficiency. These factors can make expansion across multiple Asia Pacific markets more complex and costly, particularly for smaller regional manufacturers.
Soup Product Launches in Asia
- Otsuka Foods Bon Curry Udon Soup Base – Japan (2024): Otsuka Foods introduced Bon Curry Umami wo Ajiwau Curry Udon no Moto, a curry-flavored soup base specifically formulated for preparing curry udon.
- SAARRU Traditional Indian Soup Mixes – India (2024): The Peninsular Export Company expanded its SAARRU range of indigenous soup mixes, incorporating traditional Indian flavors and targeting retail and online consumers.
- Nissin Cup Soup Premium Series – Japan (2024): Nissin Foods expanded its instant cup soup portfolio with premium seafood- and miso-based varieties designed for consumers seeking convenient meal options.
- Campbell’s Ready-to-Eat Soup Expansion – Australia (2025): Campbell’s Australia expanded its ready-to-eat soup offerings with healthier formulations emphasizing reduced sodium and plant-based ingredients.
- Knorr Asian Signature Soups – Southeast Asia (2024): Knorr introduced Asian-inspired soup varieties featuring popular regional flavors such as Tom Yum, hot and sour, and seafood.
- Ajinomoto Frozen Soup Bowls – Japan (2025): Ajinomoto expanded convenient frozen meal options with soup bowls combining broth, noodles, and vegetables for quick preparation at home.
- Maruchan Instant Soup Cups – Japan (2024): Maruchan introduced upgraded instant soup cup formulations featuring richer broths and flavors inspired by different Japanese regional cuisines.
- Nestlé MAGGI Nutritious Soup Range – India (2025): MAGGI broadened its instant soup portfolio with vegetable-focused and nutrition-oriented varieties aimed at health-conscious Indian consumers.
- Sempio Korean Soup Kits – South Korea (2024): Sempio Foods expanded its convenient Korean soup meal-kit offerings with traditional flavors such as soybean paste soup and kimchi stew.
- House Foods Ready Soup Pouches – Japan (2025): House Foods introduced convenient microwavable soup pouches designed to provide quick preparation while retaining traditional Japanese-style soup flavors.
Rising Demand for Convenience and Time-Saving Foods
Asia Pacific instant soup market is benefiting from rapid urbanization, busy lifestyles, and increasing demand for meals that require minimal preparation. Instant soups provide an affordable and convenient option for students, office workers, and urban households. Within this market, instant products benefit from their portability, long shelf life, and simple preparation. Japan, China, South Korea, India, and Thailand are important markets where consumers are familiar with instant and packaged food formats. Manufacturers are also expanding product ranges with noodle, vegetable, mushroom, seafood, chicken, and spicy regional flavors. Single-serve cups and sachets are particularly attractive for on-the-go consumption. The expansion of supermarkets, convenience stores, and e-commerce platforms is further improving accessibility. As consumers increasingly prioritize convenience without abandoning taste and affordability, instant soup is expected to remain an important product category across Asia Pacific. The development of modern retail and digital grocery channels is substantially improving access to instant soup products throughout Asia Pacific. Supermarkets, hypermarkets, convenience stores, and online marketplaces provide manufacturers with multiple avenues for reaching consumers. Convenience stores are particularly important for instant soup because they cater to consumers seeking quick, affordable, single-serving meals. E-commerce platforms further expand product selection and allow smaller brands to reach consumers outside major cities. Digital promotions, discounts, subscription purchases, and quick-commerce delivery are also encouraging trial and repeat purchases. In countries such as China, India, Japan, South Korea, and Southeast Asian economies, the combination of physical and online distribution is increasing product visibility. Consequently, stronger retail penetration and digital accessibility are expected to support sustained growth in instant soup consumption.
Longer Shelf Life and Convenient Preparation
The Asia Pacific dehydrated soup market is expanding as consumers increasingly seek shelf-stable, easy-to-store, and convenient food products. Dehydrated soups are manufactured by removing moisture from ingredients, substantially extending shelf life while reducing storage and transportation requirements. They are commonly sold as powders, cubes, flakes, and dry mixes that can be prepared by adding hot water. Their lightweight nature makes them suitable for households, offices, travel, camping, and emergency food supplies. Products are available in chicken, mushroom, tomato, vegetable, seafood, and mixed-flavor formulations. Dehydrated soup also reduces dependence on refrigerated distribution compared with chilled products, making it particularly suitable for markets with developing cold-chain infrastructure. Rising urban populations and changing meal-preparation habits are further encouraging consumers to adopt products that can provide a quick meal with minimal preparation and storage requirements. Affordability and versatility are important factors driving dehydrated soup consumption across Asia Pacific. Compared with some ready-to-eat and chilled alternatives, dry soup mixes can provide consumers with a relatively inexpensive meal or side dish while requiring limited storage space. The products can be prepared in homes, offices, institutional kitchens, and foodservice establishments simply by adding hot water or cooking them with other ingredients. This versatility makes them particularly attractive in densely populated urban markets. Dehydrated soups are also increasingly available in different portion sizes and flavor profiles to accommodate diverse regional preferences. Manufacturers are introducing vegetable-rich, reduced-preservative, organic, and premium formulations to capture health-conscious and higher-income consumers.
Strong Cultural Preference for Meat and Seafood Soups
The Asia Pacific non-vegetarian soup market benefits from long-established culinary traditions involving chicken, seafood, beef, pork, and other animal-based ingredients. Meat and seafood soups are particularly embedded in cuisines across China, Japan, South Korea, Thailand, Vietnam, and other Southeast Asian countries. Traditional dishes such as chicken broth, seafood soups, pork-based soups, and regional meat broths are consumed as appetizers, main meals, or comfort foods. Consumers increasingly expect packaged products to replicate authentic local flavors, encouraging manufacturers to use familiar ingredients and regional seasonings. Instant and ready-to-eat formats allow traditional flavors to be consumed with less preparation time. Rising disposable incomes are also supporting demand for premium meat and seafood formulations. As packaged food manufacturers combine convenience with authentic culinary profiles, non-vegetarian soup products can attract consumers seeking familiar flavors in modern, convenient formats. Increasing consumer focus on protein intake and nutritional benefits is supporting demand for non-vegetarian soups containing chicken, seafood, meat, and bone broth. Consumers increasingly associate protein-rich meals with satiety, strength, and balanced nutrition, creating opportunities for manufacturers to position meat-based soups as more than simple convenience products. Premium bone broths and collagen-oriented formulations are particularly relevant to wellness-focused consumers. Manufacturers are also developing soups with vegetables, grains, herbs, and protein ingredients to provide more complete meal solutions.
Rapid Expansion of Convenience Retail
Convenience stores are an important sales channel for soup products because they provide consumers with immediate access to affordable and easy-to-consume food. Japan, South Korea, China, Thailand, Indonesia, and other Asian markets have extensive convenience retail networks, particularly in urban areas. The extended operating hours of many convenience stores further support demand for quick meal solutions. Retailers can also use prominent shelf placement, promotional campaigns, meal bundles, and limited-edition flavors to encourage impulse purchases. Manufacturers benefit from convenience stores because these outlets provide high-frequency consumer exposure and enable rapid product rotation. As urban populations grow and consumers spend more time away from home, convenience stores are becoming increasingly important for food-to-go and quick-meal consumption. Their accessibility therefore provides a strong distribution platform for expanding soup sales across Asia Pacific. The growing preference for portion-controlled and ready-to-consume foods is strengthening soup sales through convenience stores. Single-serve cup soups, microwaveable bowls, and ready-to-eat pouches are particularly suitable for convenience retail because consumers can purchase them for immediate or near-immediate consumption. These formats reduce preparation time and appeal to office workers, students, commuters, and travelers. Manufacturers are responding by developing compact packaging, resealable formats, and microwave-compatible containers. Flavor innovation is also important, with retailers offering products inspired by local preferences such as miso, kimchi, curry, tom yum, seafood, and spicy vegetable soups. Convenience-store soup sales are increasingly supported by digital technologies and changing urban purchasing behavior. Mobile ordering, loyalty applications, digital coupons, delivery services, and quick-commerce platforms allow consumers to discover and purchase soup products more conveniently. This development is particularly relevant in densely populated Asian cities, where consumers increasingly expect fast access to prepared and packaged foods. Convenience retailers can use digital platforms to promote new flavors, limited editions, discounts, and meal combinations while collecting purchasing insights that help optimize product assortments.
China Soup Market
China is one of the largest and most dynamic soup markets in the Asia Pacific region, supported by a deeply rooted culinary tradition in which herbal, medicinal, and nourishing soups play an important role. Traditional soups remain a regular component of household meals, while demand for packaged, instant, and ready-to-eat varieties is increasing, particularly among younger consumers and busy urban professionals. Growing health consciousness is encouraging manufacturers to develop functional soups featuring collagen, herbs, mushrooms, and ingredients associated with traditional Chinese medicine. Consumers are also showing increasing interest in nutritious broths and products positioned around immunity and wellness. At the same time, innovative packaging, convenient preparation formats, and expanding e-commerce platforms are improving product accessibility throughout the country. Online grocery platforms and food-delivery services are also helping premium and specialty soup brands reach a wider consumer base. With urban lifestyles becoming increasingly fast-paced, the China soup market is expected to maintain steady growth, supported by the combination of nutrition, traditional authenticity, convenience, and product innovation.
Japan Soup Market
Japan soup market is deeply connected to the country’s established food culture, with traditional products such as miso soup remaining an important part of everyday meals. Demand for convenient and high-quality food products continues to support sales of instant soups, noodle soups, packaged broths, and ready-to-eat varieties. Japanese consumers are increasingly attentive to nutritional composition, creating opportunities for low-sodium, preservative-free, clean-label, and naturally formulated soups. The country’s aging population is another important factor, increasing demand for convenient, easy-to-digest, and nutritionally balanced meal solutions. Manufacturers are responding through premium ingredients, new flavor combinations, portion-controlled formats, and attractive packaging. In March 2024, Otsuka Foods Co., Ltd. introduced two products under its Bon Curry range, “Bon Curry Umami wo Ajiwau Curry Udon no Moto,” designed specifically for preparing curry udon dishes. Such innovations demonstrate how manufacturers are combining convenience with familiar Japanese flavors. Continued product diversification and premiumization are expected to sustain the development of Japan’s soup market.
India Soup Market
The India soup market is expanding steadily, driven by rapid urbanization, rising disposable incomes, changing lifestyles, and growing exposure to international food trends. Although homemade soups continue to have a strong presence, packaged and instant soups are becoming increasingly popular among working professionals, students, and younger consumers seeking convenient meal and snack options. Tomato, sweet corn, hot and sour, and mixed vegetable soups remain among the widely preferred varieties. Vegetarian formulations are particularly important because of prevailing dietary preferences, while demand for chicken and other non-vegetarian soups is also gradually developing. Manufacturers are increasingly focusing on affordable products, smaller pack sizes, convenient preparation, and regionally relevant flavors to expand their reach across different consumer groups. In November 2023, The Peninsular Export Company launched SAARRU, an indigenous Indian soup brand featuring locally inspired soup mixes. The initial portfolio comprised three soup mixes and was distributed through retail outlets, e-commerce platforms, and business-to-business channels across Tamil Nadu and other parts of India. Such domestic innovations are strengthening the diversity and accessibility of packaged soup products in India.
Australia Soup Market
Australia soup market is supported by growing consumer interest in healthy, premium, and convenient food options. Australian consumers increasingly seek products featuring natural ingredients, reduced sodium, plant-based formulations, and clean-label positioning, reflecting broader health and wellness trends. Soup also benefits from seasonal demand, with consumption generally increasing during colder months as consumers look for warm and comforting meal options. Canned soups remain widely accessible, while chilled fresh soups, ready-to-eat meals, and premium packaged varieties are gaining attention among consumers seeking convenience combined with nutritional value. Demand for gluten-free, preservative-free, organic, and plant-based products is encouraging manufacturers to diversify their portfolios and introduce more specialized formulations. Supermarkets and hypermarkets remain important distribution channels, while online grocery and food-delivery platforms are improving accessibility to premium and niche products. Competition between domestic and international brands is encouraging continued investment in sustainable packaging, premium ingredients, innovative flavors, and healthier formulations, supporting the long-term development of the Australian soup market.
Asia-Pacific Soup Market Overview
Type
- Instant
- Canned
- Dehydrated
- Chilled
- Others
Category
- Vegetarian
- Non-Vegetarian
Distribution Channel
- Supermarkets & Hypermarkets
- Convenience Stores
- Online
Countries
- China
- Japan
- India
- South Korea
- Thailand
- Malaysia
- Indonesia
- Australia
- New Zealand
- Rest of Asia Pacific
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- The Campbell Soup Company
- Nestle S.A.
- General Mills Inc.
- Baxters Food Group Lmt.
- Conagra Brands, Inc.
- Hindustan Unilever Group
- Premier Foods
- Associated British Food Inc
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Type, Category, Distribution Channel and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.