Asia Pacific Fast Food Market Report by Product, End User, Countries and Companies Analysis 2026-2034
Buy NowAsia Pacific Fast Food Market Size and Forecast
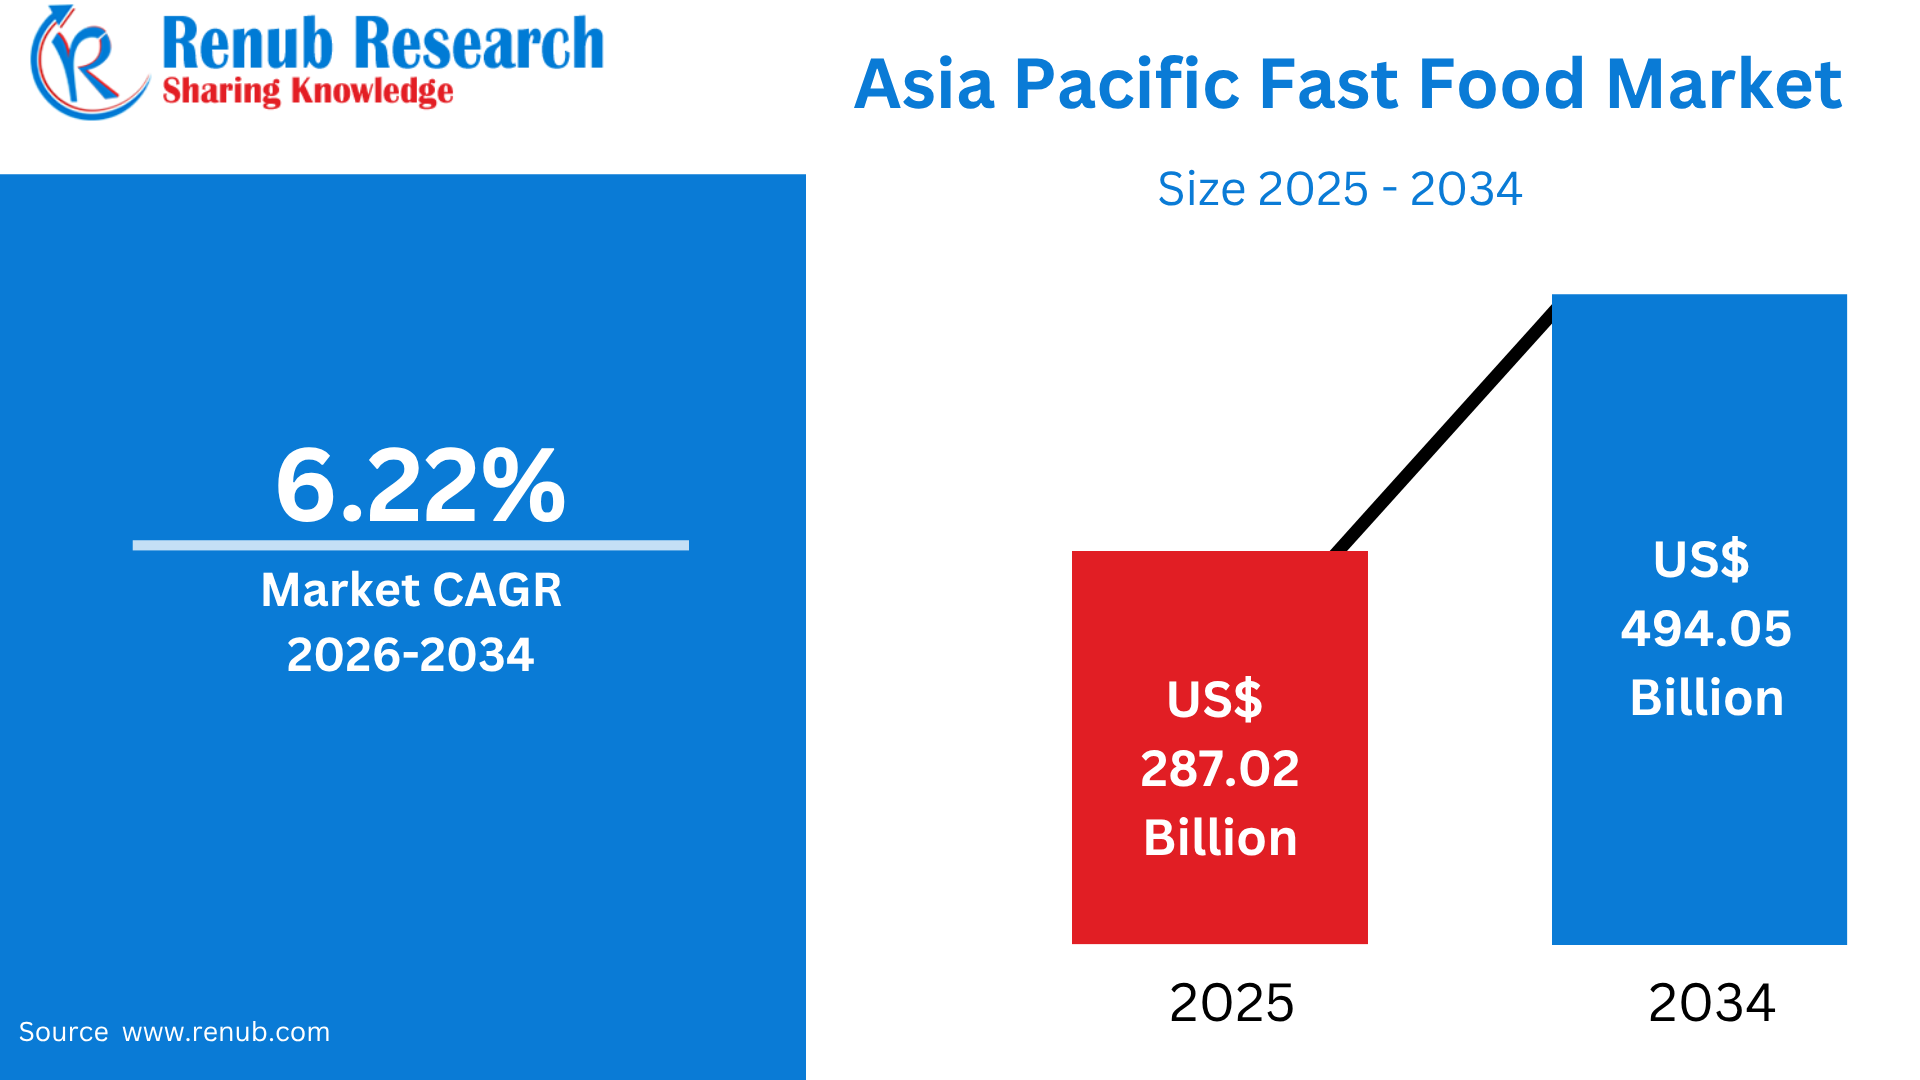
Asia Pacific Fast Food Market is expected to expand from US$ 287.02 Billion in 2025 to US$ 494.05 Billion by 2034, advancing at a Compound Annual Growth Rate (CAGR) of 6.22% during 2026–2034. The market’s expansion is being fueled by rapid urbanization, improving disposable incomes, evolving lifestyles, and consumers’ growing preference for convenient and time-saving meal options.
What is Fast Food and its Uses & Popularity in Asia Pacific
Fast food refers to commercially prepared meals that are produced and served quickly, generally through quick-service restaurants (QSRs), takeaway outlets, drive-throughs, convenience stores, cloud kitchens, and online delivery platforms. Common products include burgers, fried chicken, pizza, sandwiches, noodles, wraps, rice-based meals, snacks, and beverages. Fast food is primarily valued for convenience, affordability, standardized quality, and shorter preparation times, making it particularly suitable for consumers with busy lifestyles. In Asia Pacific, its popularity has increased alongside urbanization, rising incomes, expanding middle-class populations, and changing eating habits.
More than 2.2 billion people, representing over half of the world’s urban population, live in Asia, creating a substantial consumer base for convenient food services. Fast food has become increasingly integrated into everyday consumption among students, working professionals, young consumers, and families. International brands have also adapted menus to local tastes, while domestic chains offer region-specific products. The expansion of food-delivery applications and digital ordering has further increased accessibility across metropolitan and emerging cities.
Top Western Fast Food Chains in China
- 1. Yum! China (KFC, Pizza Hut, Taco Bell) – 17,514 restaurants, including 12,640 KFC outlets, 4,022 Pizza Hut outlets, and Taco Bell locations.
- 2. McDonald’s – 7,227 outlets across China, making it one of the country’s largest international fast-food operators.
- 3. Wallace – 20,300 outlets. Although a Chinese fast-food chain rather than a Western brand, Wallace is a major competitor in China’s burger and fast-food segment.
- 4. Tastien – 10,000 outlets, offering a Chinese-style interpretation of burgers and other fast-food products.
- 5. Burger King – Approximately 1,200 outlets, primarily focused on burgers, fries, beverages, and related QSR products.
- 6. Champion Pizza – Around 3,000 outlets, representing a significant presence in China’s pizza and quick-service food market.
- 7. Dicos – Approximately 2,500 outlets, offering fried chicken, burgers, and other Western-style fast-food products.
- 8. Domino’s Pizza – Around 1,280 outlets, with its network focused primarily on pizza delivery and dine-in/takeaway services.
- 9. Subway – Approximately 1,000 outlets, specializing in made-to-order sandwiches, salads, and related quick-service meals.
- 10. Xiang Dia Wei Burger – More than 3,000 outlets, representing a large Chinese fast-food burger network competing in the value-oriented QSR segment.
Source: Food Service – Hotel, Restaurant, Institutional Annual, China 2025.
Growth Drivers of Asia Pacific Fast Food Market
Rapid Urbanization and Busy Consumer Lifestyles
Rapid urbanization is one of the strongest factors supporting fast food consumption across Asia Pacific. Growing city populations, longer commuting times, expanding employment opportunities, and increasingly time-constrained lifestyles are encouraging consumers to choose convenient meals rather than preparing food at home. Asia already contains more than 2.2 billion urban residents, representing approximately 54% of the world’s urban population, and the region’s urban population is expected to increase substantially through 2050. This demographic transformation creates opportunities for quick-service restaurants near offices, transportation hubs, shopping centers, educational institutions, and residential developments. Fast food is particularly attractive to younger consumers, working professionals, students, and dual-income households because meals can be purchased quickly and consumed either on-site or while travelling. The expansion of organized retail and commercial infrastructure is also increasing restaurant accessibility beyond major metropolitan areas. As urban lifestyles become increasingly fast-paced, demand for affordable, convenient, and readily available meals is expected to remain a major contributor to regional market expansion.
Rising Disposable Income and Expanding Middle-Class Consumers
Increasing household purchasing power across developing Asia Pacific economies is encouraging consumers to spend more frequently on prepared meals, dining out, and food delivery. Economic development in countries such as China, India, Indonesia, Vietnam, and the Philippines has contributed to the expansion of middle-income consumer groups with greater discretionary spending capacity. Rising incomes are changing food preferences, with consumers increasingly willing to pay for convenience, branded products, restaurant experiences, and customized meals. Fast food also benefits from its broad price range, allowing brands to serve both value-oriented customers and consumers seeking premium products. International and regional chains are consequently expanding into secondary cities and suburban markets where rising incomes are creating new demand. Industry research identifies rising disposable income as a major factor behind fast-food consumption across Asia Pacific, particularly in emerging economies. Menu localization further strengthens this opportunity by combining familiar local flavors with standardized restaurant formats. As purchasing power continues to improve, consumers are expected to increase their frequency of eating outside the home.
Digital Food Delivery and Expansion of QSR Chains
The rapid adoption of smartphones, digital payments, restaurant applications, and food-delivery platforms is transforming how fast food is ordered and consumed across Asia Pacific. Consumers can now discover restaurants, compare menus, receive promotional offers, place orders, make cashless payments, and track deliveries through integrated digital platforms. This has significantly expanded the addressable market for restaurants beyond customers physically visiting outlets. Delivery platforms and cloud kitchens have also enabled brands to enter locations where traditional restaurants may face higher operating costs. At the same time, international QSR companies and local restaurant chains are increasing their outlet networks and adapting menus to regional preferences. Industry research highlights the combination of mobile ordering, delivery partnerships, and cloud kitchens as an important factor supporting fast-food penetration in China, India, and Indonesia.Digital ordering also generates customer data that restaurants can use for targeted promotions, loyalty programs, personalized recommendations, and demand forecasting. Continued digitalization is therefore expected to improve convenience while strengthening restaurant reach, customer engagement, and sales frequency.
Challenges of Asia Pacific Fast Food Market
Growing Health and Nutrition Concerns
Health concerns associated with frequent consumption of highly processed, calorie-dense, high-sodium, high-sugar, and high-fat foods represent an important challenge for the fast food industry. Consumers and governments across Asia Pacific are becoming increasingly attentive to obesity, diabetes, cardiovascular diseases, and other diet-related health conditions. The World Health Organization reports that around 1 billion people in the Asia-Pacific region were overweight or obese, representing approximately 40% of the global total in the cited regional assessment. In Southeast Asia, WHO also identifies rapid dietary changes toward highly processed and out-of-home foods as part of a broader nutrition transition. These trends can increase regulatory scrutiny of nutritional labeling, advertising, portion sizes, and ingredients. In response, fast-food companies are introducing salads, grilled products, vegetarian meals, reduced-sugar beverages, smaller portions, and other comparatively health-oriented alternatives. However, reformulating products while maintaining affordability, taste, and consumer appeal remains challenging. Health-conscious consumers may increasingly favor brands that demonstrate transparency and provide more balanced menu choices.
Intense Competition, Cost Pressures, and Regulatory Requirements
The Asia Pacific fast food market is highly competitive, with international QSR brands competing against established domestic chains, independent restaurants, convenience stores, delivery-only kitchens, and emerging food-service concepts. This competition places pressure on pricing, promotional spending, restaurant locations, menu innovation, and customer retention. At the same time, operators face fluctuations in food ingredients, packaging, energy, labor, rent, and logistics costs, which can reduce profit margins. Regulatory requirements related to food safety, hygiene, nutrition, labor practices, waste management, and advertising can further increase operating complexity. Market competition is particularly intense in major cities where consumers have numerous restaurant and delivery choices. Companies must therefore continually invest in digital platforms, loyalty programs, localized menus, delivery capabilities, and efficient supply chains. The expansion of both global and local chains has increased market choice, while localized offerings have intensified competition for consumer attention. Maintaining consistent quality across rapidly expanding restaurant networks while controlling costs will remain a significant challenge for fast-food operators throughout Asia Pacific.
Asia Pacific Fast Food Recent Developments
- May 2025 – Burger King: Burger King intensified its value-led promotions and digital initiatives in India to stimulate restaurant traffic amid cautious consumer spending. Its India business reported positive same-store sales growth, supported by stronger dine-in traffic and affordable menu offerings.
- April–May 2025 – KFC: KFC India continued emphasizing menu innovation, value offerings, sauces, dips, and boneless chicken products to attract younger consumers. The brand also expanded its digital self-ordering kiosk network, with kiosks implemented across hundreds of restaurants.
- April 2025 – Burger King: Burger King India launched its Korean Spicy Fest, featuring Korean-inspired burgers, chicken, wings, and fries. The limited-time range was designed to capitalize on growing consumer interest in Korean culture and bold flavors, particularly among Gen Z consumers.
- May 2025 – Domino’s Pizza: Domino’s India continued its rapid expansion and digital-delivery strategy. During Q4 FY2025, the brand recorded 18.8% revenue growth, while order growth reached 24.6%, with delivery remaining a major contributor to performance.
- 2025 – Burger King Digital Transformation: Burger King India continued shifting toward a digital-first restaurant model through self-ordering kiosks, QR-based table ordering, app ordering, and delivery platforms. The company reported that digital channels represented around 90% of orders at certain locations, highlighting the growing importance of technology in Asia Pacific QSR operations.
- 2024–2025 – KFC Menu Innovation: KFC increased its focus on premium and sauce-led products, including its KFC Gold burger and expanded popcorn and boneless ranges. The strategy reflects the broader fast-food trend toward limited-time products, customization, and flavor experimentation to attract younger consumers.
Growing Demand for Seafood-Based Convenience Meals
Asia Pacific seafood fast food market is expanding as consumers increasingly seek convenient meals that combine quick preparation with protein and nutritional value. Seafood has a strong cultural presence across Japan, China, South Korea, Thailand, Indonesia, Vietnam, and other coastal economies, creating a favorable foundation for seafood-based fast-food products. Restaurants are expanding offerings such as fish burgers, shrimp burgers, crispy prawns, seafood wraps, fish sandwiches, squid snacks, and seafood rice bowls. Product localization is particularly important, with operators incorporating flavors such as teriyaki, chili, garlic butter, tempura, and spicy sauces. Increasing demand for healthier alternatives to conventional red-meat fast food, together with premium seafood options and delivery-friendly products, is encouraging restaurant chains to expand seafood menus. Sustainable sourcing, traceability, and responsible fisheries are also becoming increasingly important differentiators for consumers and foodservice operators.
Chicken Remains a Dominant Fast-Food Protein
Asia Pacific chicken fast food market continues to benefit from the protein’s affordability, broad consumer acceptance, and adaptability to regional cuisines. Chicken can be incorporated into fried chicken, burgers, wraps, wings, grilled products, rice bowls, sandwiches, and snack meals, allowing QSR operators to serve different consumer preferences at multiple price points. International brands such as KFC and McDonald’s compete alongside strong domestic and regional chains by introducing localized flavors, limited-time products, spicy variants, and value meals. India, Indonesia, the Philippines, Thailand, and South Korea remain important growth markets because of expanding urban populations and rising demand for convenient meals. Delivery platforms, family bundles, loyalty programs, and promotional pricing are further increasing chicken fast-food consumption, while healthier grilled and lower-oil options are broadening the segment’s consumer base.
Rising Demand for Comfortable and Social Dining
The full-service restaurant segment is gaining importance as Asia Pacific consumers increasingly combine convenience-oriented eating with social dining experiences. Full-service establishments generally provide table service, broader menus, enhanced interiors, and a more relaxed atmosphere than conventional QSR outlets, making them suitable for families, groups, celebrations, and business meals. China, Japan, South Korea, Australia, and major Southeast Asian economies represent important markets where consumers are willing to spend more for improved food quality, ambiance, and service. Restaurant operators are increasingly integrating digital reservations, QR-code menus, mobile ordering, loyalty applications, and delivery services to improve customer engagement. Premium fast-food concepts, localized menus, family-oriented restaurants, and hybrid fast-casual formats are also helping operators capture consumers seeking greater quality without sacrificing convenience.
QSRs Lead Through Convenience, Digitalization, and Scale
Quick-service restaurants remain a central growth engine for the Asia Pacific fast food market because they provide affordable meals with short service times and increasingly convenient digital ordering options. Across China, India, Indonesia, Japan, South Korea, Vietnam, and Australia, operators are expanding restaurant networks while adapting menus to local tastes. QSR operators are therefore investing in mobile applications, self-service kiosks, digital payments, loyalty programs, cloud kitchens, and delivery integrations. Menu localization, value meals, limited-time promotions, and increasingly sophisticated customer-data analytics are further strengthening QSR competitiveness and supporting continued regional expansion.
China Rapid Expansion of Domestic and International Fast-Food Chains
China is one of the most dynamic fast-food markets in Asia Pacific, supported by urbanization, rising consumer spending, digital ordering, and changing lifestyles. International brands such as KFC, McDonald’s, Pizza Hut, Burger King, and Domino’s compete alongside rapidly expanding domestic operators that differentiate themselves through localized flavors and Chinese-style products. Tastien, for example, had more than 7,000 stores across China by May 2024, illustrating the rapid rise of domestic burger chains. Its positioning around “Chinese culture with Chinese taste” includes burgers inspired by traditional flavors such as Peking duck and Mapo tofu. Domestic brands are increasingly using localized menus, lower pricing, smaller-format outlets, and franchise-led expansion to compete with global chains. At the same time, mobile ordering, QR-code payments, delivery applications, and loyalty programs are becoming integral to restaurant operations. Younger consumers are particularly receptive to innovative products combining Western fast-food formats with Chinese culinary traditions. This combination of digitalization, localization, and aggressive store expansion is expected to maintain China’s importance in the regional fast-food industry.
India Urbanization and Digital Delivery Drive Market Expansion
India’s fast-food market is expanding rapidly as urbanization, rising disposable incomes, a growing working population, and changing eating habits increase demand for convenient meals. International QSR brands are strengthening their presence through localized products, while domestic chains compete with Indian snacks, regional flavors, vegetarian offerings, and affordable meal combinations. Online food delivery and mobile ordering have become important growth channels, enabling restaurants to reach consumers beyond traditional high-street and shopping-mall locations. Burger King India operates more than 290 restaurants nationally, according to its official restaurant locator, demonstrating the continued expansion of international QSR brands. The company’s Raipur expansion also illustrates the increasing penetration of organized fast food into emerging urban markets: its City Centre Mall outlet became the brand’s first restaurant in Raipur in December 2024, followed by another location in Shankar Nagar. Tier-2 and Tier-3 cities are becoming increasingly important as infrastructure, digital payments, delivery networks, and consumer purchasing power improve. Menu affordability, vegetarian choices, regional customization, and promotional campaigns will remain key competitive factors.
South Korea Plant-Based Innovation and Technology Reshape Fast Food
South Korea’s fast-food market combines international QSR brands with technologically sophisticated domestic operators, supported by high urbanization, smartphone penetration, and an established food-delivery ecosystem. Burgers, fried chicken, sandwiches, and fusion products remain popular, while Korean flavors such as gochujang, bulgogi, kimchi, and spicy sauces are frequently incorporated into fast-food menus. Health, sustainability, and alternative proteins are also becoming increasingly relevant, particularly among younger consumers. In April 2023, Shinsegae Food announced that No Brand Burger would transition all of its burger buns to 100% plant-based ingredients, replacing butter, milk, and eggs. In May 2023, the company subsequently introduced its Better Burger, using plant-based buns, alternative-meat patties, plant-based cheese, and plant-based sauces. The company described it as the first burger franchise product using all four major burger ingredients in plant-based form. The Better Burger sold more than 20,000 units within its first 10 days, averaging roughly 2,000 units per day, demonstrating consumer interest in plant-based fast-food innovation.
Thailand Hybrid Restaurant Concepts Expand Consumer Choice
Thailand’s fast-food market is benefiting from urbanization, tourism, rising disposable incomes, food-delivery adoption, and consumers’ growing preference for convenient dining. International chains compete with strong local and regional operators that incorporate Thai and Asian flavors into familiar fast-food formats. Japanese-inspired food is also particularly influential, reflecting Thailand’s well-established Japanese restaurant culture. In April 2022, Oishi launched Oishi Biztoro, a hybrid fast-casual Japanese restaurant concept designed to provide convenient and affordable meals. The concept combines elements of fast food and full-service dining and offers dishes across categories including Ramen and Soba, Donburi, and Snacks. By early April 2022, the concept had already opened three outlets, indicating an effort to establish a new format within Thailand’s competitive restaurant sector. The market is also being transformed by food-delivery applications, digital payments, loyalty programs, and promotional campaigns. Younger consumers are increasingly attracted to limited-time products, fusion menus, affordable meal bundles, and visually appealing food. Meanwhile, healthier options, plant-based meals, and sustainable packaging are creating additional opportunities for fast-food operators.
Market Segments
Product
- Pizza/Pasta
- Burgers/Sandwiches
- Chicken
- Asian/Latin American
- Seafood
- Others
End User
- Full-Service Restaurants
- Quick-Service Restaurants
- Catering
- Others
Countries
- China
- Japan
- India
- South Korea
- Thailand
- Malaysia
- Indonesia
- Australia
- New Zealand
- Rest of Asia Pacific
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- McDonald's Corporation
- Yum! Brands, Inc
- Domino's Pizza Inc
- Wendy's International Inc
- Jack in the Box Inc
- Starbucks Corp
- Papa John's International Inc
- Kentucky Fried Chicken (KFC)
- Corteva Agriscience
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Product, End User and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.