United States Defense Market Report by Armed Force, Type, States and Companies Analysis 2026-2034
Buy NowUnited States Defense Market Size and Forecast
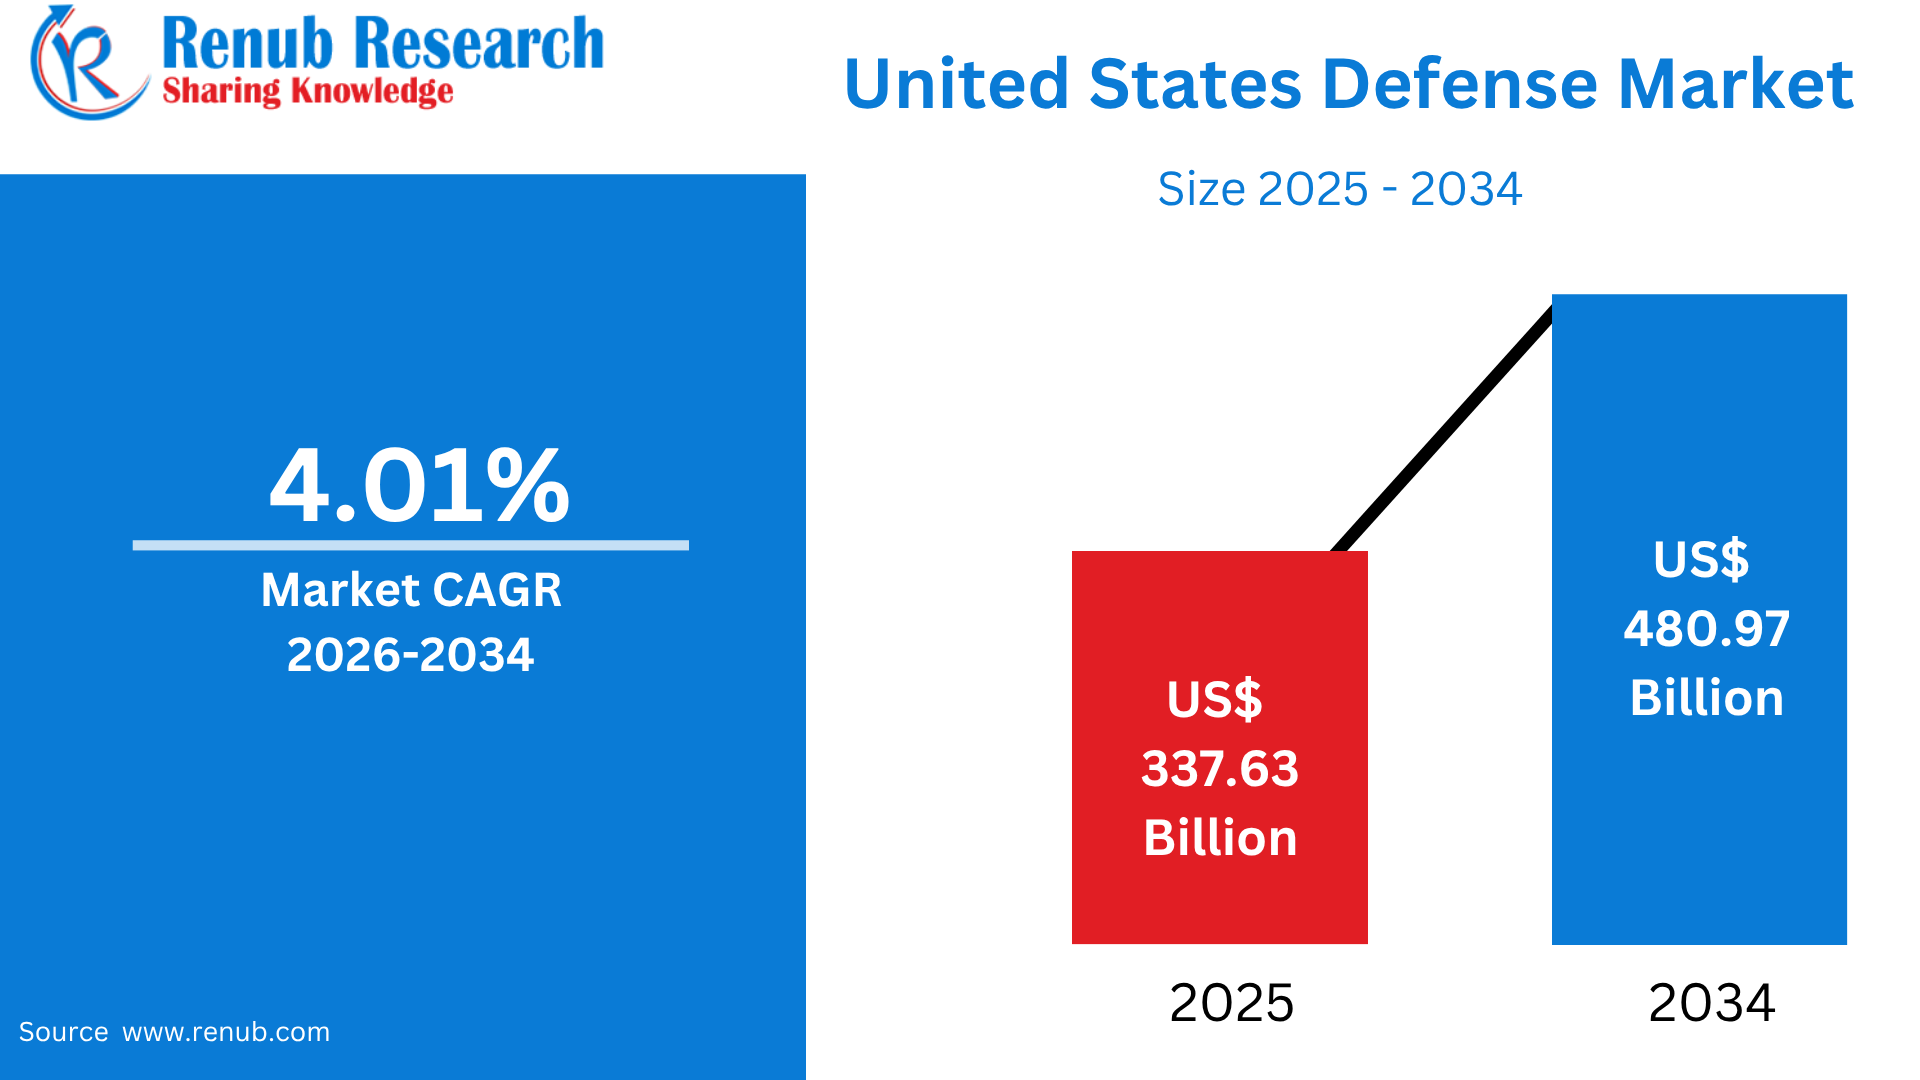
United States Defense Market is projected to grow from US$ 337.63 billion in 2025 to US$ 480.97 billion by 2034, registering a CAGR of 4.01% during 2026–2034. The U.S. defense market is anticipated to maintain consistent growth throughout the forecast period, supported by increasing defense expenditure, military modernization initiatives, rapid technological advancements, evolving geopolitical tensions, and the growing need for sophisticated defense systems and advanced military capabilities.
What is Defense and Its Uses & Popularity in the USA
Defense refers to the systems, technologies, equipment, services, personnel, and infrastructure used by a nation to protect its territory, population, national interests, and armed forces from external and emerging threats. In the United States, defense encompasses the Army, Navy, Air Force, Marine Corps, Space Force, cybersecurity, missile defense, intelligence, military communications, logistics, and advanced weapons systems. Defense capabilities are used for national security, deterrence, border and homeland protection, overseas military operations, protection of critical infrastructure, and support of allies. The sector also plays an important role in technological innovation through investments in artificial intelligence, autonomous systems, cybersecurity, satellites, advanced aircraft, naval platforms, and hypersonic weapons. Its popularity and strategic importance in the U.S. remain high because of the country’s global military commitments and evolving security environment. The proposed FY2026 national defense budget reached approximately US$1.01 trillion, representing a 13.4% increase from FY2025, highlighting the government’s continued emphasis on military readiness, modernization, homeland security, and technological superiority.
U.S. Defense Spending by Activity – FY2025
- Total Defense Spending: The United States spent approximately US$916 billion on national defense in Fiscal Year 2025. Defense spending represented around 13% of total federal spending.
- Operation & Maintenance – 37%: The largest share of defense spending was allocated to operation and maintenance, covering military operations, training, equipment maintenance, logistics, and much of military healthcare. This category accounted for approximately 37% of defense spending.
- Military Personnel – 23%: Around 23% of defense spending supported military personnel, including pay, benefits, retirement, and other personnel-related costs.
- Procurement – 18%: Approximately 18% of defense spending was directed toward procurement of weapons, military equipment, aircraft, ships, vehicles, and other defense systems.
- Research & Development – 15%: About 15% was allocated to research and development, supporting the development and testing of advanced weapons, military technologies, equipment, and next-generation defense capabilities.
- Other Defense Activities – 7%: The remaining 7% covered activities such as military construction, family housing, atomic energy defense activities, and other defense-related expenditures.
- Defense Spending Priorities: The distribution highlights the broad scope of U.S. defense expenditure, balancing current military operations and personnel requirements with procurement and investment in future defense technologies.
Source: Office of Management and Budget (OMB), as presented by the Peter G. Peterson Foundation (PGPF), FY2025 Defense Spending.
Growth Drivers of the United States Defense Market
Rising Defense Spending and Military Modernization
Increasing government expenditure on national security is one of the strongest growth drivers for the U.S. defense market. The proposed FY2026 national defense budget was approximately US$1.01 trillion, representing a 13.4% increase over FY2025. The budget places significant emphasis on shipbuilding, missile defense, munitions, military readiness, infrastructure, and modernization. The Department of Defense’s FY2026 request also included substantial increases across procurement and research and development, supporting new aircraft, naval platforms, ground equipment, and advanced technologies. In addition, the CBO reported that DoD’s FY2026 acquisition funding totaled approximately US$384 billion, covering procurement and research, development, testing, and evaluation. These investments create sustained demand for fighter aircraft, submarines, missiles, armored vehicles, surveillance systems, communications equipment, and other defense technologies. Modernization is particularly important as the U.S. seeks to replace aging platforms while maintaining technological superiority. Continued funding for strategic systems such as the B-21 bomber, Columbia-class submarines, missile defense, and nuclear modernization is therefore expected to support market expansion.
Growing Demand for Advanced Military Technologies
Rapid technological development is transforming modern warfare and generating significant opportunities for U.S. defense companies. The military is increasingly investing in artificial intelligence, autonomous and unmanned systems, cybersecurity, advanced sensors, space-based capabilities, electronic warfare, directed-energy weapons, and hypersonic systems. The FY2026 defense budget specifically allocated funding toward advanced missile defense and emerging technologies, including US$25 billion for the Golden Dome missile-defense initiative. The initiative includes investments in interceptors, advanced sensors, integrated command-and-control systems, and space-based capabilities. Hypersonic technology is another major investment area: the Department of Defense requested substantial funding for offensive and defensive hypersonic warfare programs, while the Army and Navy are jointly pursuing capabilities requiring more than US$50 billion in investment across related programs. These developments increase demand for sophisticated electronics, propulsion systems, software, communications infrastructure, sensors, and precision-guided weapons. As military operations become increasingly technology-driven, continuous innovation and the need to counter sophisticated adversary capabilities are expected to stimulate long-term defense-market growth.
Rising Geopolitical Tensions and Strategic Threats
Increasing geopolitical competition is encouraging the United States to strengthen military capabilities across land, sea, air, cyberspace, and space. Strategic competition with China, Russia’s military activities, missile proliferation, cyber threats, and emerging technologies are encouraging greater investment in deterrence and military readiness. The Department of Defense has identified China as a major pacing challenge and Russia as an acute security threat, contributing to increased spending on advanced combat capabilities and the defense industrial base. The FY2025 defense budget request included US$28.4 billion for missile-defense capabilities, reflecting concerns about increasingly sophisticated missile threats. The United States is also expanding capabilities in space as competition increasingly extends beyond traditional military domains. Recent developments involving U.S.-China space capabilities highlight the growing strategic importance of satellites, space surveillance, and counter-space technologies. These evolving threats encourage government agencies to accelerate procurement and modernization programs. Consequently, geopolitical uncertainty is expected to sustain demand for missiles, air-defense systems, surveillance technologies, military aircraft, naval platforms, cybersecurity, and other defense solutions.
Challenges of the United States Defense Market
Supply Chain Vulnerabilities and Defense Industrial Base Constraints
Supply chain dependency represents a major challenge for the U.S. defense market. The Department of Defense relies on a global network of more than 200,000 suppliers to produce weapons systems and noncombat products such as batteries and manufacturing equipment. Dependence on foreign sources for critical materials, components, and microelectronics can create risks if geopolitical disputes, export restrictions, transportation disruptions, or trade restrictions affect availability. The Government Accountability Office has highlighted foreign dependency as a national-security risk, particularly where adversarial countries could restrict access to critical materials or introduce vulnerabilities into technology. For example, China imposed export restrictions on gallium and germanium in 2024, two materials important to military-grade electronics. Defense manufacturers also face difficulties scaling production of critical munitions and advanced systems quickly enough to meet growing demand. These constraints can increase procurement costs, extend delivery timelines, and delay modernization programs. Strengthening domestic manufacturing capacity, diversifying suppliers, and improving supply-chain visibility will therefore remain essential for sustainable U.S. defense-market growth.
High Costs, Procurement Complexity, and Program Delays
High development costs and complex procurement processes can restrict the speed and efficiency of defense-market expansion. Advanced military systems often require years of research, testing, certification, production, and integration before reaching operational deployment. The Government Accountability Office recently reported challenges in U.S. hypersonic programs, including production issues, funding and testing challenges, and delays in integrating the Conventional Prompt Strike system. The modernization of certain Zumwalt-class destroyers for hypersonic missile deployment was 24 months behind schedule as of 2026. More broadly, industry participants continue to identify procurement complexity as a major concern. A 2026 defense-industry survey found that 66% of private-sector respondents identified complex and prolonged procurement processes as a pressing issue, while 55% cited federal budget processes and 50% cited government-contracting compliance burdens. Such challenges can raise program costs, discourage smaller suppliers, slow technology adoption, and delay delivery of critical capabilities. Improving acquisition processes, coordinating programs across military services, and providing clearer demand signals could help address these structural constraints.
Defense Product Launches in the USA
- Mako Hypersonic Missile – 2024: Lockheed Martin unveiled the Mako hypersonic weapon, designed to operate at speeds above Mach 5 and engage time-sensitive, high-value targets.
- Next Generation Interceptor (NGI) – 2024: Lockheed Martin was selected by the U.S. Missile Defense Agency to continue development of the NGI for homeland ballistic-missile defense.
- Long-Range Hypersonic Weapon (LRHW) – 2024: The U.S. Army and Navy conducted a successful end-to-end flight test of the conventional hypersonic missile system from Cape Canaveral, Florida.
- PAC-3 MSE Interceptor – 2024: Lockheed Martin demonstrated a PAC-3 MSE interceptor launched from an MK-70 containerized platform, successfully engaging a cruise-missile-type target.
- HBTSS Missile-Tracking Satellites – 2024: Five missile-tracking satellites developed by L3Harris were launched from Cape Canaveral under U.S. missile-defense and space-tracking programs.
- Switchblade 600 Loitering Munition – 2024: AeroVironment’s Switchblade 600 became the first confirmed procurement under the Pentagon’s Replicator initiative, supporting the rapid adoption of autonomous and uncrewed systems.
- Autonomous HIMARS Capability – 2024: Lockheed Martin demonstrated an autonomous HIMARS surrogate launcher capable of navigating without a driver using non-emitting perception sensors.
- AGM-158 XR Cruise Missile – 2024: Lockheed Martin introduced the AGM-158 eXtreme Range cruise missile, designed as an extended-range evolution of the JASSM family.
- New Glenn National Security Launch Vehicle – 2025: Blue Origin’s New Glenn entered orbital operations with its first launch in January 2025 and is being developed for future U.S. national-security space missions.
- Vulcan National Security Launch Vehicle – 2025: United Launch Alliance’s Vulcan rocket achieved certification for U.S. National Security Space Launch missions, expanding the country’s heavy-lift launch capability.
Army Modernization and Transformation
United States Army defense market is being driven by extensive modernization of ground forces, including investments in precision fires, air and missile defense, unmanned systems, electronic warfare, next-generation vehicles, communications, and battlefield intelligence. The Army’s FY2026 end strength is planned at approximately 954,000 personnel, compared with about 943,100 in FY2025. Army military personnel funding, including applicable healthcare accruals, is approximately US$58.4 billion for FY2026. Modernization is increasingly focused on creating a more mobile, networked, and technology-intensive force capable of operating against sophisticated adversaries. The Army is also emphasizing drones and counter-drone capabilities, long-range fires, artificial intelligence, and advanced battlefield networks. Programs involving next-generation combat vehicles, precision missile systems, and integrated air-defense platforms are creating opportunities for defense manufacturers. Rising demand for battlefield connectivity and autonomous technologies is further expanding the addressable market. These investments are expected to sustain demand for military vehicles, weapons, communications equipment, sensors, ammunition, and electronic systems across the U.S. Army defense ecosystem. The increasing importance of long-range precision fires and unmanned technologies is reshaping the U.S. Army defense market. Modern conflicts have demonstrated the effectiveness of drones, loitering systems, precision missiles, electronic warfare, and battlefield surveillance technologies. Consequently, the Army is increasing its emphasis on systems capable of detecting, targeting, and engaging threats at extended ranges. The FY2026 defense budget includes substantial funding for long-range weapons and hypersonic capabilities, while the broader Department of Defense budget allocates US$6.5 billion for conventional and hypersonic munitions, supporting procurement of nearly 2,000 critical weapons. The Army’s development and deployment of the Long-Range Hypersonic Weapon further illustrates the shift toward high-speed, precision strike capabilities. At the same time, counter-unmanned aircraft systems are becoming increasingly important for protecting troops and installations. These trends are creating new demand for missiles, launchers, drones, sensors, targeting systems, electronic warfare equipment, and command-and-control technologies, supporting continued growth of the Army defense market.
Fleet Expansion and Naval Modernization
United States Navy defense market is supported by the country’s strategic requirement to maintain maritime superiority across the Indo-Pacific, Atlantic, and other critical regions. The Navy’s FY2026 planning provides for a deployable battle force of approximately 287 ships, including 11 aircraft carriers, 63 submarines, 115 surface combatants, 36 support ships, 31 combat-logistics ships, and 31 amphibious ships. Shipbuilding and modernization are therefore major components of defense spending. The FY2026 Shipbuilding and Conversion, Navy account totals approximately US$47.38 billion, including funding for ballistic-missile ships, other warships, amphibious vessels, auxiliaries, and related programs. The Navy is also pursuing modernization of aircraft carriers, destroyers, submarines, unmanned vessels, and maritime surveillance systems. Investments in Virginia-class and Columbia-class submarines are particularly significant because nuclear-powered platforms remain central to U.S. strategic deterrence. Continued procurement of advanced ships, weapons, sensors, propulsion systems, and communications equipment is expected to create sustained opportunities for shipbuilders and defense suppliers. The increasing complexity of maritime competition is creating strong demand for advanced naval platforms and autonomous technologies. Submarines remain one of the most strategically important areas because they provide stealth, long-range strike capabilities, intelligence collection, and nuclear deterrence. The FY2026 defense plan includes funding for two Virginia-class submarines at approximately US$11 billion and one Columbia-class submarine at approximately US$11 billion. The Navy is also investing in aircraft carriers, guided-missile destroyers, frigates, amphibious platforms, and unmanned maritime systems. Future fleet concepts increasingly incorporate autonomous surface and underwater vehicles that can perform surveillance, reconnaissance, mine countermeasures, communications, and potentially combat missions. The Navy’s long-term shipbuilding strategy targets a substantially larger fleet, with plans indicating an objective of reaching approximately 355 manned battle-force ships by FY2040. This expansion would require significant investment in shipyards, skilled labor, propulsion systems, naval electronics, weapons, and maintenance infrastructure. Consequently, fleet expansion and industrial-base investment are expected to remain major growth opportunities for the U.S. Navy defense market.
Increasing Procurement and Munitions Stockpiling
United States weapons and ammunition market is experiencing strong demand as the government seeks to replenish inventories, strengthen deterrence, and increase production capacity for high-priority munitions. Recent conflicts have demonstrated the importance of maintaining adequate stocks of missiles, artillery rounds, air-defense interceptors, precision-guided weapons, and other ammunition. The FY2026 defense plan allocates approximately US$6.5 billion to conventional and hypersonic munitions, supporting procurement of nearly 2,000 critical weapons. Investment is also being directed toward expanding domestic production capacity for missiles and interceptors. Long-term procurement contracts are intended to provide manufacturers with greater visibility and encourage expansion of production lines. Demand is particularly strong for precision-guided weapons, air-defense interceptors, long-range missiles, artillery ammunition, and advanced warheads. The replenishment of inventories used for overseas military assistance and operational requirements is another important market factor. As the United States seeks a larger and more resilient ammunition stockpile, manufacturers are expected to invest in additional production facilities, automation, workforce development, and supply-chain capabilities. Advanced missile systems, hypersonic weapons, precision-guided munitions, and integrated air-defense technologies are becoming increasingly important components of the U.S. weapons and ammunition market. The United States is investing in systems designed to counter ballistic missiles, cruise missiles, drones, and increasingly sophisticated aerial threats. The FY2026 defense plan includes more than US$3.9 billion for hypersonic weapons, reflecting the strategic importance of high-speed offensive and defensive capabilities. Missile-defense programs such as Patriot and THAAD are also receiving increased attention as the United States seeks to strengthen protection against sophisticated missile threats. In addition, investment in long-range precision fires is increasing the demand for advanced propulsion, seekers, guidance systems, warheads, and launch platforms. The market is also benefiting from efforts to expand domestic industrial capacity, including multiyear procurement agreements that provide manufacturers with incentives to increase production. This combination of higher inventories, advanced weapon development, and industrial-base expansion is expected to support sustained growth across the U.S. weapons and ammunition sector.
Fighter Aircraft Modernization and F-35 Demand
U.S. fixed-wing aircraft market is strongly supported by ongoing modernization of fighter and combat aircraft fleets. The F-35 Lightning II remains one of the most important programs, providing the U.S. military with a fifth-generation multirole aircraft featuring stealth, advanced sensors, network connectivity, and precision-strike capabilities. Continued procurement and sustainment of F-35 aircraft generate demand across aircraft manufacturing, engines, avionics, radar, electronic warfare, weapons integration, software, maintenance, and spare parts. At the same time, the U.S. Air Force is developing the B-21 Raider as a next-generation stealth bomber intended to strengthen long-range strike capabilities. The modernization of existing fleets is also creating opportunities for manufacturers involved in upgrading fourth-generation aircraft, transport aircraft, tankers, and surveillance platforms. The growing importance of air superiority and long-range strike capabilities is encouraging investments in advanced sensors, autonomous technologies, artificial intelligence, and electronic warfare. Consequently, replacement of aging aircraft and the introduction of next-generation platforms are expected to remain major growth drivers for the U.S. fixed-wing aircraft market. Technological advancement is transforming the U.S. fixed-wing aircraft market, with growing emphasis on sixth-generation combat aircraft, autonomous systems, advanced propulsion, artificial intelligence, and networked warfare. The U.S. Air Force’s Next Generation Air Dominance (NGAD) initiative is intended to develop highly advanced air-combat capabilities incorporating stealth, long-range weapons, sophisticated sensors, and manned-unmanned teaming. The broader concept of Collaborative Combat Aircraft is also expected to introduce lower-cost autonomous aircraft capable of operating alongside crewed fighters. These systems can perform surveillance, electronic warfare, targeting, and potentially strike missions while reducing risks to human pilots. The U.S. military’s continued investment in advanced aircraft is supported by the need to counter increasingly capable air-defense networks and fighter aircraft operated by strategic competitors. In addition to combat aircraft, demand for aerial refueling tankers, military transport aircraft, intelligence and surveillance aircraft, and special-mission platforms remains important. The combination of fleet replacement, technological modernization, and autonomous aviation is therefore expected to sustain long-term growth in the U.S. fixed-wing aircraft market.
California Defense Market
California represents a significant contributor to the United States defense market, supported by its highly developed aerospace, technology, and innovation ecosystem. The state hosts a large concentration of defense contractors, technology firms, research institutions, and specialized engineering organizations involved in aerospace systems, satellites, cybersecurity, advanced electronics, and space technologies. Strong cooperation between government agencies, private companies, universities, and research organizations encourages continuous development of advanced defense capabilities. California is particularly important in areas such as space-based defense, unmanned systems, artificial intelligence, digital technologies, and electronic warfare. The availability of a highly skilled workforce and established innovation centers further strengthens the state’s defense industrial base. Increasing federal investments in space security, advanced military technologies, and next-generation defense systems are expected to sustain California’s importance and support continued expansion of its defense-related activities.
Texas Defense Market
Texas is a major defense hub in the United States, benefiting from its extensive military infrastructure, aerospace manufacturing capabilities, industrial base, and strategic geographic position. The state is home to numerous military installations, defense contractors, aerospace manufacturers, and research organizations supporting land, air, missile, and cybersecurity operations. Texas has a strong presence in aircraft production and maintenance, missile and weapons development, defense logistics, military training, and advanced engineering. Its well-established manufacturing ecosystem enables defense companies to support large-scale production and modernization programs. In addition, investments in research and development are encouraging innovation in areas such as autonomous systems, aerospace technologies, cybersecurity, and advanced military platforms. Continued federal spending on military modernization and infrastructure is expected to strengthen Texas’s role in the national defense industry. Its combination of industrial capacity, skilled talent, military facilities, and technological capabilities makes the state an important center for defense production and innovation.
New York Defense Market
New York contributes substantially to the United States defense market through its advanced technology ecosystem, research capabilities, financial resources, and concentration of technology-oriented companies. The state has an important role in cybersecurity, intelligence, communications, aerospace technologies, surveillance systems, software development, and data analytics used for defense and homeland security applications. Defense organizations and technology companies are increasingly developing sophisticated digital platforms capable of supporting intelligence gathering, secure communications, threat detection, and military decision-making. New York’s universities and research institutions also contribute to innovation by supporting research in engineering, computer science, artificial intelligence, cybersecurity, and other defense-related technologies. Furthermore, the state’s strategic importance extends to homeland security and protection of critical infrastructure against physical and cyber threats. Growing adoption of advanced digital technologies and increased emphasis on cybersecurity and intelligence capabilities are expected to reinforce New York’s contribution to the broader U.S. defense market.
Florida Defense Market
Florida is an important component of the United States defense market, supported by its strategic coastal location, extensive military infrastructure, aerospace industry, and strong presence in space-related activities. The state plays a critical role in space launches, missile testing, naval operations, military aviation, and defense training. Florida hosts numerous military installations, defense contractors, aerospace companies, and specialized facilities involved in satellite systems, aircraft operations and maintenance, missile technologies, and unmanned aerial systems. The rapid expansion of the commercial space sector has further strengthened the state’s strategic relevance by supporting technologies and infrastructure with potential defense applications. Continued investment in military facilities, aerospace infrastructure, training centers, and advanced technologies is expected to sustain demand for defense-related capabilities across the state. Florida’s combination of space, aviation, maritime, and military capabilities positions it as a key center for U.S. national defense operations and next-generation aerospace development.
Recent Developments in United States Defense Market
- January 2026: Lockheed Martin and the US Department of Defense reached a deal to more than treble PAC-3 Missile Segment Enhancement unit manufacturing over a seven-year period.
- October 2025: The US Army granted General Dynamics Mission Systems a USD 28.30 million contract to supply crucial C5ISR/EW Modular Open Suite of Standards (CMOSS) Mounted Form Factor (CMFF) prototype systems.
- September 2025: Top defense contractors, including Anduril, Lockheed Martin, General Atomics, Boeing, and Northrop Grumman, received contracts from the Navy to construct Collaborative Combat Aircraft (CCA) drones.
United States Defense Market Segments
Armed Force
- Army
- Navy
- Air Force
Type
- Fixed-wing Aircraft
- Rotorcraft
- Ground Vehicles
- Naval Vessels
- C4ISR
- Weapons and Ammunition
- Protection and Training Equipment
- Unmanned Systems
States
- California
- Texas
- New York
- Florida
- Illinois
- Pennsylvania
- Ohio
- Georgia
- New Jersey
- Washington
- North Carolina
- Massachusetts
- Virginia
- Michigan
- Maryland
- Colorado
- Tennessee
- Indiana
- Arizona
- Minnesota
- Wisconsin
- Missouri
- Connecticut
- South Carolina
- Oregon
- Louisiana
- Alabama
- Kentucky
- Rest of United States
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Lockheed Martin Corporation
- The Boeing Company
- RTX Corporation
- General Dynamics Corporation
- Northrop Grumman Corporation
- L3Harris Technologies Inc.
- CACI International Inc.
- Textron Inc.
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Armed Force, Type and States |
| States Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.