North America Salmon Fish Market Report by Form, Species, Distribution Channel, Countries and Companies Analysis 2026-2034
Buy NowNorth America Salmon Fish Market Size and Forecast
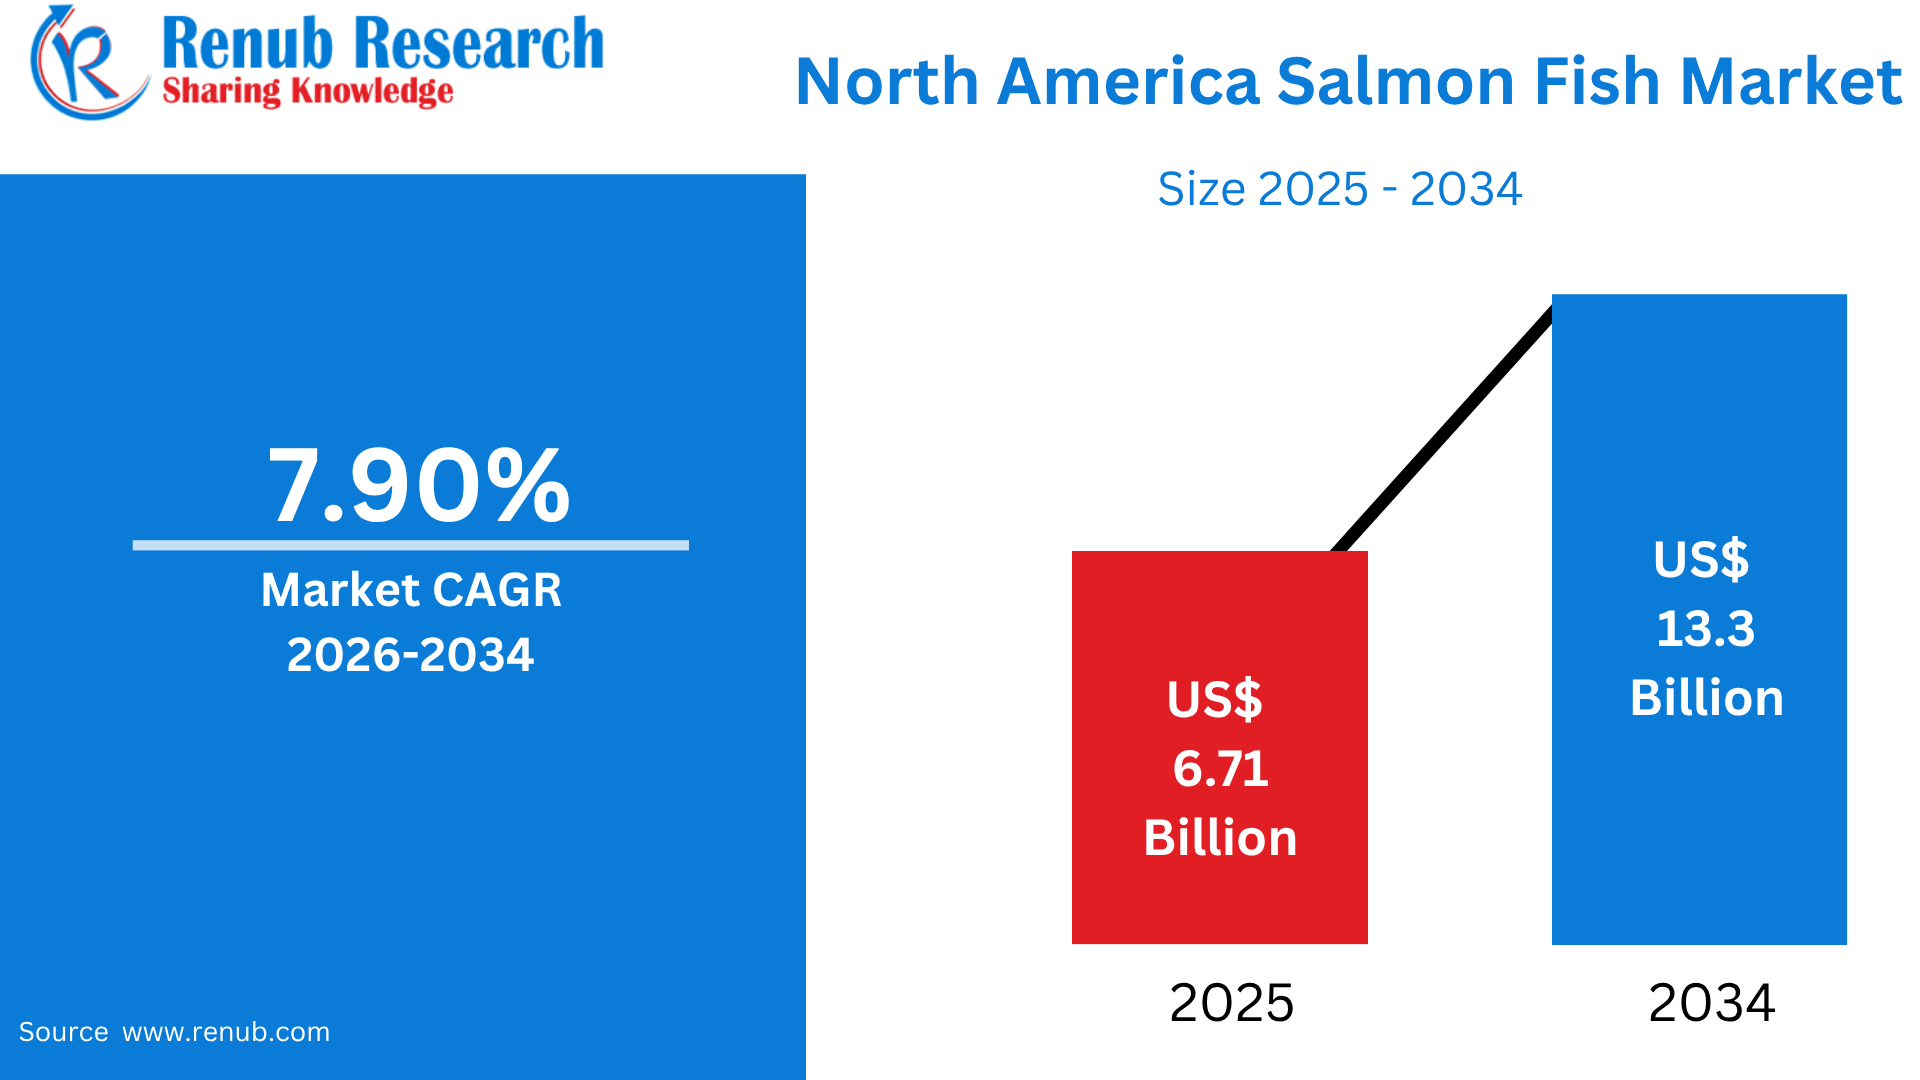
North America Salmon Fish Market is projected to reach US$ 13.3 billion by 2034, rising from US$ 6.71 billion in 2025 and registering a CAGR of 7.9% during 2026–2034. The market is anticipated to experience robust growth, driven by increasing seafood consumption, growing consumer awareness of the nutritional benefits of salmon, and rising demand for high-quality protein-rich foods. In addition, advancements in salmon aquaculture, improved cold-chain and distribution infrastructure, and the expanding presence of salmon products across supermarkets, foodservice outlets, and online retail channels are supporting market development.
What is Salmon Fish and its Uses & Popularity in North America
Salmon is a nutrient-rich, oily fish belonging primarily to the Salmonidae family and is widely consumed across North America because of its high-quality protein, omega-3 fatty acids, vitamins, and minerals. Common varieties include Atlantic salmon, Chinook, Sockeye, Coho, and Pink salmon. Salmon is used extensively in fresh, frozen, smoked, canned, marinated, and ready-to-cook formats, making it suitable for households, restaurants, hotels, catering businesses, and foodservice operators. It is also increasingly incorporated into salads, sushi, sandwiches, pasta, bowls, and premium seafood meals. In the United States, Atlantic salmon available in seafood markets is farm-raised, while most of the Atlantic salmon consumed is imported. Salmon’s popularity is supported by growing seafood consumption and consumer interest in nutrient-dense protein. U.S. per-capita seafood consumption reached 19.1 pounds in 2023, while Atlantic salmon ranked among the leading marine aquaculture species. Canada is also a major salmon-producing market, recording approximately 88,076 tonnes of salmon aquaculture production worth CAD 883.4 million in 2024.
Total Adult Salmon Returns to North America, 2003–2023
Approximate values, in thousands of fish
- 2013: Small salmon – ~570, Large salmon – ~260, Total – ~720
- 2014: Small salmon – ~530, Large salmon – ~280, Total – ~710
- 2015: Small salmon – ~640, Large salmon – ~260, Total – ~790
- 2016: Small salmon – ~710, Large salmon – ~310, Total – ~910
- 2017: Small salmon – ~570, Large salmon – ~290, Total – ~770
- 2018: Small salmon – ~530, Large salmon – ~280, Total – ~710
- 2019: Small salmon – ~560, Large salmon – ~240, Total – ~690
- 2020: Small salmon – ~520, Large salmon – ~230, Total – ~640
- 2021: Small salmon – ~590, Large salmon – ~270, Total – ~750
- 2022: Small salmon – ~790, Large salmon – ~270, Total – ~960
- 2023: Small salmon – ~670, Large salmon – ~300, Total – ~860
Source: ICES Working Group on North Atlantic Salmon.
Growth Drivers of the North American Salmon Fish Market
Rising Seafood Consumption and Health-Conscious Diets
Increasing consumer awareness of the nutritional benefits of seafood is supporting salmon demand across North America. Salmon provides high-quality protein and is naturally rich in omega-3 fatty acids, making it attractive to consumers seeking heart-healthy and nutrient-dense foods. In the United States, per-capita seafood consumption reached 19.1 pounds in 2023, demonstrating a substantial consumer base for fish and seafood products. Salmon is particularly well positioned within this market because it is available in convenient fresh, frozen, smoked, canned, and ready-to-cook formats. Restaurants and foodservice operators also use salmon extensively in premium meals, sushi, salads, sandwiches, and bowls. Growing interest in protein-rich diets and healthier alternatives to some red and processed meats is further supporting consumption. The popularity of salmon among health-conscious consumers is therefore encouraging retailers and foodservice businesses to expand product variety, while producers are investing in processing and distribution capabilities to meet demand across North America.
Expansion of Aquaculture and Reliable Salmon Supply
The development of aquaculture is a major growth driver because farmed salmon provides a consistent year-round supply for North American consumers and foodservice businesses. In the United States, Atlantic salmon was among the leading marine aquaculture species in 2023, highlighting its importance to domestic seafood production. Canada has an especially strong salmon aquaculture industry. In 2024, Canadian salmon production reached approximately 88,076 tonnes, generating around CAD 883.4 million in production value. Salmon accounted for approximately 55% of Canada’s total aquaculture production volume and 65% of its total aquaculture value in 2024. Improvements in hatchery systems, feed management, fish health monitoring, farm technology, and production practices are helping producers improve efficiency and supply consistency. The expansion of aquaculture therefore supports market availability while helping retailers and processors maintain dependable supplies of salmon throughout the year.
Growth of Retail, Foodservice, and Premium Seafood Channels
Expansion across supermarkets, specialty seafood retailers, restaurants, and online grocery platforms is increasing the accessibility of salmon products throughout North America. Consumers can purchase salmon as fresh fillets, frozen portions, smoked products, prepared meals, and other value-added formats, broadening its appeal beyond traditional seafood consumption. The U.S. seafood market also has substantial dependence on international supply: the country imported 6.3 billion pounds of edible seafood products in 2023, while approximately 80% of seafood consumed by Americans came from foreign imports. This extensive trade network enables retailers and foodservice operators to source salmon from major producing countries and maintain product availability. Canada also has strong trade connections with the U.S.; 94% of Canada’s aquaculture exports are destined for the United States, with farmed Atlantic salmon representing the largest aquaculture export commodity at approximately $945 million. Premium seafood positioning, restaurant demand, and expanding retail distribution are consequently strengthening salmon sales across the region.
Challenges of the North America Salmon Fish Market
Environmental and Sustainability Concerns in Salmon Aquaculture
Environmental sustainability remains a significant challenge for the North American salmon industry, particularly for farmed salmon. Concerns can include interactions with wild fish populations, marine ecosystem impacts, disease management, waste, feed sourcing, and the environmental footprint of farming systems. Canada illustrates the complexity of the issue. Although salmon production reached approximately 88,076 tonnes in 2024, salmon production in British Columbia has declined substantially from earlier levels. Fisheries and Oceans Canada notes that farm closures and the planned mandatory shutdown of open-net pen farms by 2029 have contributed to changes in production in the province. Producers therefore face increasing pressure to demonstrate responsible production and improve environmental performance. Investments in closed-containment systems, improved monitoring, alternative feeds, fish-health technologies, and more sustainable farming practices can increase operating costs. Balancing production growth with environmental protection and consumer expectations will remain important for the long-term expansion of the North American salmon market.
Dependence on Imports and Supply-Chain Volatility
The North American salmon market is exposed to international supply-chain conditions because the United States relies heavily on imported seafood, while much of its Atlantic salmon supply originates outside the country. NOAA reports that approximately 80% of seafood consumed in the United States was imported in 2023. NOAA also notes that all Atlantic salmon sold in U.S. seafood markets is farm-raised and most is imported. Dependence on international suppliers can expose the market to transportation costs, currency movements, trade policies, geopolitical disruptions, disease outbreaks, production shortages, and fluctuations in feed and energy costs. Salmon prices can consequently vary across retail and foodservice channels, affecting purchasing decisions and producer margins. While Canada provides an important regional supply base, its aquaculture sector is also undergoing structural changes. In 2024, Canadian salmon production remained significant, but British Columbia’s output was well below its 2022 level. These supply considerations can create challenges for maintaining stable pricing and consistent availability.
Salmon Fish Launches in North America
- MOWI Atlantic Salmon Lightly Smoked Portions – 2025: MOWI expanded its U.S. ready-to-cook portfolio with lightly smoked Atlantic salmon portions. The product was soft-launched in late 2024 and rolled out to additional regional markets in 2025, targeting consumers seeking convenient, high-protein meals.
- MOWI Signature Fresh Atlantic Salmon – 2025: MOWI launched its MOWI Signature program in the U.S. in May 2025, offering premium fresh Atlantic salmon from Norwegian and Scottish sources specifically for foodservice professionals.
- Wildtype Cultivated Salmon – 2025: Wildtype introduced its cultivated sushi-grade salmon commercially through selected U.S. restaurants. The product debuted at Kann in Portland in May 2025, followed by launches at restaurants in Texas, California, and Seattle.
- Latitude 45 Smoked Salmon Candy Bites – 2024: Multi X launched Latitude 45 Smoked Salmon Candy Bites in the U.S. at Seafood Expo North America in March 2024. The ready-to-eat hot-smoked product was designed around convenient snacking and at-home consumption.
- Latitude 45 Smoked Chipotle Salmon – 2024: Alongside Candy Bites, Multi X introduced Smoked Chipotle Salmon under the Latitude 45 brand. The product combines hot-smoked salmon with a spicy flavor profile aimed at consumers seeking differentiated ready-to-eat seafood.
- Scott & Jon’s Mediterranean Herb Salmon Bowl – 2024: Scott & Jon’s introduced a frozen Mediterranean Herb Salmon Bowl for U.S. retail in early 2024. The product was positioned as a convenient complete meal and launched through retailers including Target, Harris Teeter, Giant Eagle, and Southeastern Grocers.
- Scott & Jon’s Honey Sesame Salmon Bowl – 2024: The company also launched a Honey Sesame Salmon Bowl as part of its new frozen salmon meal range. The product targeted consumers seeking convenient seafood meals with familiar flavor combinations.
- King Oscar Atlantic Salmon in Extra Virgin Olive Oil – 2023: King Oscar USA introduced a premium canned Atlantic salmon range in 2023, featuring skinless and boneless salmon packed in extra virgin olive oil. The line included original, Mediterranean-style, and lemon varieties.
- Ocean Beauty Echo Falls Wild Alaska Salmon Nuggets – 2023: Ocean Beauty introduced honey-cured smoked wild Alaska sockeye salmon nuggets under its Echo Falls brand. The bite-sized format targeted snacking and entertaining occasions and subsequently won first place in the retail category at the Alaska Symphony of Seafood competition.
- Ocean Beauty Grill House Salmon Burger – 2023: Ocean Beauty launched its Grill House Burger, made with wild-caught Alaska salmon and non-GMO vegetable proteins. The product was developed as a high-protein alternative to conventional meat burgers and received the Best Foodservice Product award at the 2023 Alaska Symphony of Seafood.
Premium Freshness and Consumer Preference
North America fresh salmon fish market is supported by strong consumer preference for high-quality, minimally processed seafood. Fresh salmon is widely used in households, restaurants, hotels, supermarkets, specialty seafood stores, and foodservice operations because of its premium taste, texture, and nutritional profile. In the United States, fresh seafood accounted for approximately 43% of retail seafood sales revenue, while salmon represented a significant share of fresh seafood sales. Fresh salmon is particularly popular in premium meal preparation, sushi, salads, grilled dishes, and ready-to-cook products. Demand is also supported by salmon’s reputation as a source of protein and omega-3 fatty acids. In Canada, salmon remains a major aquaculture species, with 88,076 tonnes of salmon produced in 2024, valued at approximately CAD 883.4 million. Improved cold-chain logistics, refrigerated transportation, seafood counters, and online grocery delivery are helping retailers maintain product quality and expand access to fresh salmon across North America. Fresh salmon demand is increasing across restaurants and organized retail as consumers seek premium seafood and convenient protein-rich meals. Restaurants use fresh salmon for grilled fillets, sushi, poke bowls, sandwiches, salads, and specialty dishes, while supermarkets offer whole fish, fillets, steaks, portions, and marinated products. The U.S. market benefits from a large seafood-import infrastructure, enabling retailers to maintain year-round availability despite seasonal variations in domestic fisheries. Canada also plays an important supply role, with aquaculture production increasingly serving domestic and export markets. Canadian aquaculture exports were valued at approximately CAD 1.1 billion in 2024, with 94% destined for the United States, highlighting the importance of cross-border trade to North American salmon availability. The combination of premium positioning, restaurant demand, supermarket expansion, and improved refrigerated distribution is expected to strengthen the fresh salmon segment.
Longer Shelf Life and Year-Round Availability
North America frozen salmon fish market benefits from the product’s longer shelf life, convenient storage, and ability to provide year-round availability. Frozen salmon is particularly attractive to households, restaurants, institutional foodservice providers, and retailers that require consistent inventory without the shorter shelf-life constraints associated with fresh fish. Freezing also enables salmon producers and distributors to transport products over long distances while maintaining quality. NOAA Fisheries identifies frozen Chinook salmon as available year-round, compared with fresh Chinook, which is mainly available during summer and early fall. Frozen salmon is sold as fillets, portions, steaks, whole fish, and value-added products, making it suitable for baking, grilling, air frying, and meal preparation. Growth in household freezer usage, online grocery purchasing, and demand for convenient protein products is supporting frozen seafood consumption. Retailers increasingly use frozen formats to broaden product ranges and reduce supply interruptions caused by seasonal fishing and international logistics. Frozen salmon is an important product format for North American seafood distribution because it provides greater flexibility across production, transportation, warehousing, and retail. Canada produced 88,076 tonnes of salmon through aquaculture in 2024, providing a significant regional supply base, while the United States continues to rely heavily on international seafood supply. Frozen processing allows suppliers to build inventories and serve geographically distant markets without requiring immediate consumption. Supermarkets, warehouse clubs, foodservice distributors, and e-commerce grocery platforms increasingly offer frozen salmon portions because of their convenience and predictable storage requirements. Product standardization also supports portion-controlled meals and ready-to-cook offerings. Canadian farmed salmon exports are particularly important to the U.S. market, with 94% of Canada’s aquaculture exports destined for the United States in 2024. Consequently, frozen salmon is positioned as an important channel for maintaining availability and managing fluctuations in fresh seafood supply across North America.
Premium Positioning and Culinary Demand
North America Chinook salmon fish market is characterized by premium positioning because Chinook, also known as King salmon, is regarded as one of the most highly valued salmon species. NOAA Fisheries describes Chinook as having a rich, buttery taste and oily, meaty texture, characteristics that support premium pricing in restaurants and specialty seafood markets. The species is harvested primarily along the U.S. Pacific coast and in Alaska, while Canadian fisheries also contribute to market supply. In 2024, U.S. commercial Chinook salmon landings reached approximately 6.9 million pounds, with a value of about US$30 million. Chinook is sold fresh and frozen, with fresh availability concentrated mainly in summer and early fall and frozen products available throughout the year. The species is widely used for grilling, roasting, smoking, sushi, and premium restaurant dishes. Its distinctive flavor and high-end culinary reputation make it particularly attractive to consumers seeking premium seafood experiences. Chinook salmon market is closely connected to fisheries management, conservation programs, and cross-border resource management in North America. Wild Chinook populations are managed through catch limits, monitoring, habitat protection, and coordinated fisheries programs because some populations remain below desired abundance levels. The Pacific Salmon Treaty and Pacific Salmon Commission help coordinate management and research for shared salmon stocks between the United States and Canada. These measures are important for maintaining long-term availability while balancing commercial, recreational, and conservation requirements. Unlike farmed Atlantic salmon, Chinook sold in the U.S. is primarily associated with wild fisheries from Alaska to California. Its premium positioning also means that supply limitations can influence prices and availability. Consequently, sustainable harvesting, population monitoring, and responsible fisheries management remain important factors shaping the North American Chinook salmon market.
Supermarkets and Grocery Chains Drive Accessibility
North America salmon fish retail market is supported by supermarkets, hypermarkets, warehouse clubs, specialty seafood retailers, grocery stores, and online grocery platforms. Retailers offer salmon in fresh, frozen, smoked, canned, marinated, and ready-to-cook formats, allowing consumers to select products according to price, convenience, and preparation requirements. U.S. retail seafood data indicate that fresh seafood generated approximately 43% of retail seafood sales revenue, demonstrating the importance of fresh products within the retail environment. Salmon is one of the leading species within fresh seafood retail, benefiting from strong consumer recognition and premium positioning. Retailers increasingly emphasize packaged fillets, portion-controlled products, skin-on and skinless cuts, and prepared seafood meals to simplify home cooking. Canadian production also contributes to retail supply, with 88,076 tonnes of salmon produced through Canadian aquaculture in 2024. Expanding supermarket seafood counters and online grocery delivery are expected to further improve consumer access to salmon across North America. Convenience is becoming an important factor in the North America salmon retail market as consumers increasingly prefer products requiring limited preparation. Retailers are therefore expanding offerings such as seasoned fillets, pre-portioned cuts, smoked salmon, vacuum-packed portions, ready-to-cook meals, and frozen salmon products. These formats appeal to busy households while allowing retailers to capture higher-value opportunities beyond conventional whole-fish sales. Salmon also benefits from its premium nutritional image and association with protein-rich and omega-3-containing diets. Canada’s salmon production provides an important regional supply base, while the United States represents a major destination for Canadian aquaculture exports. In 2024, Canadian aquaculture exports totaled approximately CAD 1.1 billion, and 94% were destined for the United States. Retailers are also strengthening traceability, sustainability labeling, cold-chain management, and responsible sourcing programs to respond to consumer expectations. These developments are helping salmon move from traditional seafood counters toward convenient, packaged, premium retail formats.
Strong Consumer Demand for Healthy Seafood in USA
United States salmon fish market is supported by strong consumer interest in nutritious, protein-rich seafood and convenient meal options. Salmon is widely consumed in fresh, frozen, smoked, canned, and prepared formats across households, restaurants, hotels, and institutional foodservice. In 2023, U.S. per-capita seafood consumption reached approximately 19.1 pounds, highlighting the country’s substantial seafood demand. Salmon benefits from its reputation as a source of high-quality protein and omega-3 fatty acids, supporting consumption among health-conscious consumers. Retailers are expanding seafood selections through premium fillets, portioned cuts, ready-to-cook meals, and value-added products. Foodservice operators are also incorporating salmon into sushi, salads, grilled meals, bowls, and premium dishes. Product innovation is creating additional opportunities, particularly with alternative production technologies. In May 2025, the FDA completed its consultation for Wildtype’s cultivated salmon, representing an important development for cell-cultivated seafood in the U.S. market. Wildtype products subsequently appeared at Kann restaurant in Portland, Oregon, demonstrating early commercial adoption of alternative salmon products. U.S. salmon market benefits from a sophisticated seafood distribution network covering supermarkets, warehouse clubs, specialty seafood stores, restaurants, foodservice distributors, and e-commerce channels. The country remains highly dependent on imported seafood, creating significant opportunities for international salmon suppliers. Canadian farmed Atlantic salmon is particularly important to U.S. supply: 74,719 tonnes of Canadian farmed Atlantic salmon were exported in 2024, with the United States accounting for 93.5% of export volume. This strong cross-border trade relationship helps maintain year-round availability across American retail and foodservice channels. Salmon is increasingly marketed through premium positioning, sustainability claims, traceability programs, and convenient packaged formats. Retailers are also expanding fresh and frozen portions that simplify preparation for consumers. Meanwhile, restaurants continue to support demand through sushi, poke, grilled salmon, and premium seafood menus. The combination of established distribution infrastructure, international sourcing, health-oriented consumption, and product innovation is expected to maintain the United States as the dominant salmon market within North America.
Major Aquaculture and Export Industry in Canada
Canada plays a central role in the North America salmon fish market through its substantial aquaculture industry, extensive coastal resources, and established seafood-processing infrastructure. Salmon is Canada’s leading aquaculture species by both production and value. In 2024, Canadian salmon aquaculture production reached approximately 88,076 tonnes, generating around CAD 883.4 million in value. British Columbia remained the largest producing province, although Atlantic provinces have increasingly contributed to national farmed-finfish production. Canadian salmon products are supplied to domestic retailers, restaurants, processors, and international markets. The United States is particularly important to Canada’s salmon industry, accounting for approximately 93.5% of Canadian farmed Atlantic salmon exports by quantity in 2024. This strong export relationship supports production volumes and encourages investments in processing, cold-chain infrastructure, traceability, and product quality. Canadian producers are also focusing on responsible aquaculture practices and sustainability as consumers increasingly consider environmental performance and product origin when purchasing seafood. Canada’s salmon market is supported by established supermarket chains, seafood retailers, restaurants, hotels, and foodservice distributors. Consumers increasingly select salmon because of its nutritional profile, versatility, and premium positioning. Fresh salmon is commonly sold as fillets, steaks, portions, and whole fish, while frozen, smoked, canned, and prepared products provide additional convenience. Canadian aquaculture provides an important source of consistent domestic supply, helping retailers maintain availability throughout the year. The country’s salmon production increased in 2024, with national aquaculture salmon volume reaching approximately 88,076 tonnes. Total Canadian aquaculture production also recovered during 2024, increasing approximately 8% from 2023, demonstrating renewed industry activity. Retailers are increasingly emphasizing traceability, responsible sourcing, freshness, and convenient packaging to differentiate salmon products. Meanwhile, restaurants use salmon across sushi, grilled dishes, salads, sandwiches, and premium menu offerings. These developments, combined with Canada’s strong production base and close integration with the U.S. seafood market, are expected to support continued development of the Canadian salmon fish market.
Rising Imports and Premium Seafood Demand in Mexico
Mexico represents a developing market for salmon within North America, supported by urbanization, changing dietary preferences, tourism, and increasing exposure to international cuisine. Salmon is increasingly consumed in restaurants, hotels, supermarkets, specialty seafood stores, and premium food outlets, particularly in major urban and tourism centers. Mexico relies considerably on imports to satisfy demand for salmon products. In 2024, Mexico imported approximately US$19.6 million of fresh or chilled salmon, with Chile accounting for approximately US$15.4 million of those purchases. Fresh salmon fillets generated another US$22.2 million in international purchases during 2024, with Chile supplying approximately US$15.3 million. These trade figures demonstrate the importance of international suppliers in meeting Mexican demand. Salmon is increasingly associated with premium dining, sushi, healthy meals, and protein-rich diets. As consumers become more familiar with international seafood products and retailers broaden premium seafood assortments, salmon is gaining greater visibility. The expansion of modern retail, restaurants, food delivery, and hospitality services is expected to provide additional opportunities for market development. Mexican salmon market is also supported by growing availability of frozen and processed products, which improve accessibility and extend shelf life. Frozen salmon fillets are particularly important because they can be transported and stored efficiently across Mexico’s extensive retail and foodservice network. In 2024, Mexico imported approximately US$146 million of frozen salmon fillets, with Chile supplying about US$128 million, demonstrating the significant role of Chilean producers in Mexico’s frozen salmon supply. Mexico City represented the largest importing market for these products at approximately US$80.4 million, followed by the State of Mexico at US$23.8 million and Jalisco at US$15.1 million. Smoked salmon also contributes to premium seafood consumption, with Mexico importing approximately 79,540 kg of smoked salmon worth about US$1.44 million in 2024. These figures indicate that demand extends beyond fresh products into frozen and value-added categories. Continued expansion of supermarkets, restaurants, hotels, and premium foodservice channels should create further opportunities for salmon suppliers.
Recent Developments in North America Salmon Fish Market
- To safeguard wild salmon and advance sustainable aquaculture, the Canadian government declared in October 2025 that open-net pen salmon farming will be prohibited by 2029. With regard to diseases and sea lice outbreaks among farmed fish, which may have an impact on wild salmon populations, this ruling seeks to address environmental concerns. Conservation organizations have applauded the restriction, but the salmon farming sector has attacked it, claiming that switching to closed containment systems is difficult both financially and logistically.
- The Canadian government published its first plan to repair and restore Atlantic salmon populations and their habitats in March 2026. Four funding programs have contributed $6.1 million to this campaign in order to support conservation initiatives. A call for proposals will be issued in the upcoming months, and an extra $1 million has been set aside for the 2026–2027 fiscal year to support new initiatives aimed at Atlantic salmon conservation.
- The Conservation Law Foundation (CLF) issued a notice of intent to sue Cooke Aquaculture in November 2025, claiming that the company's salmon farming operations off the coast of Maine violated the Clean Water Act. According to the CLF, the company's activities are contaminating maritime areas with garbage, endangering wild salmon populations and local ecosystems. Cooke Aquaculture claims to be in conformity with environmental rules and refutes these accusations.
North America Salmon Fish Market Segments
Form
- Fresh
- Frozen
- Smoked
- Canned
- Others
Species
- Chinook Salmon
- Coho Salmon
- Pink Salmon
- Red Salmon
- Silverbrite Salmon
- Salmon Salar
Distribution Channel
- Retail
- HoReCa & Wholesale
- Processed Food Indistry
- Other Institutional Customers
Countries
- United States
- Canada
- Mexico
- Rest of North America
Companies have been covered from 5 viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Camanchaca Inc.
- Atlantic Capes Fisheries, Inc.
- Leroy Seafood Group ASA
- Marine Harvest ASA
- Multiexport Foods S.A.
- Marine Harvest ASA
- Sea trade
- Atalanta Corporation
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Form, Species, Distribution Channel and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.