Medical Gas Market Report by Product, Application, End Use, Countries and Companies Analysis 2026-2034
Buy NowMedical Gas Market Size and Forecast
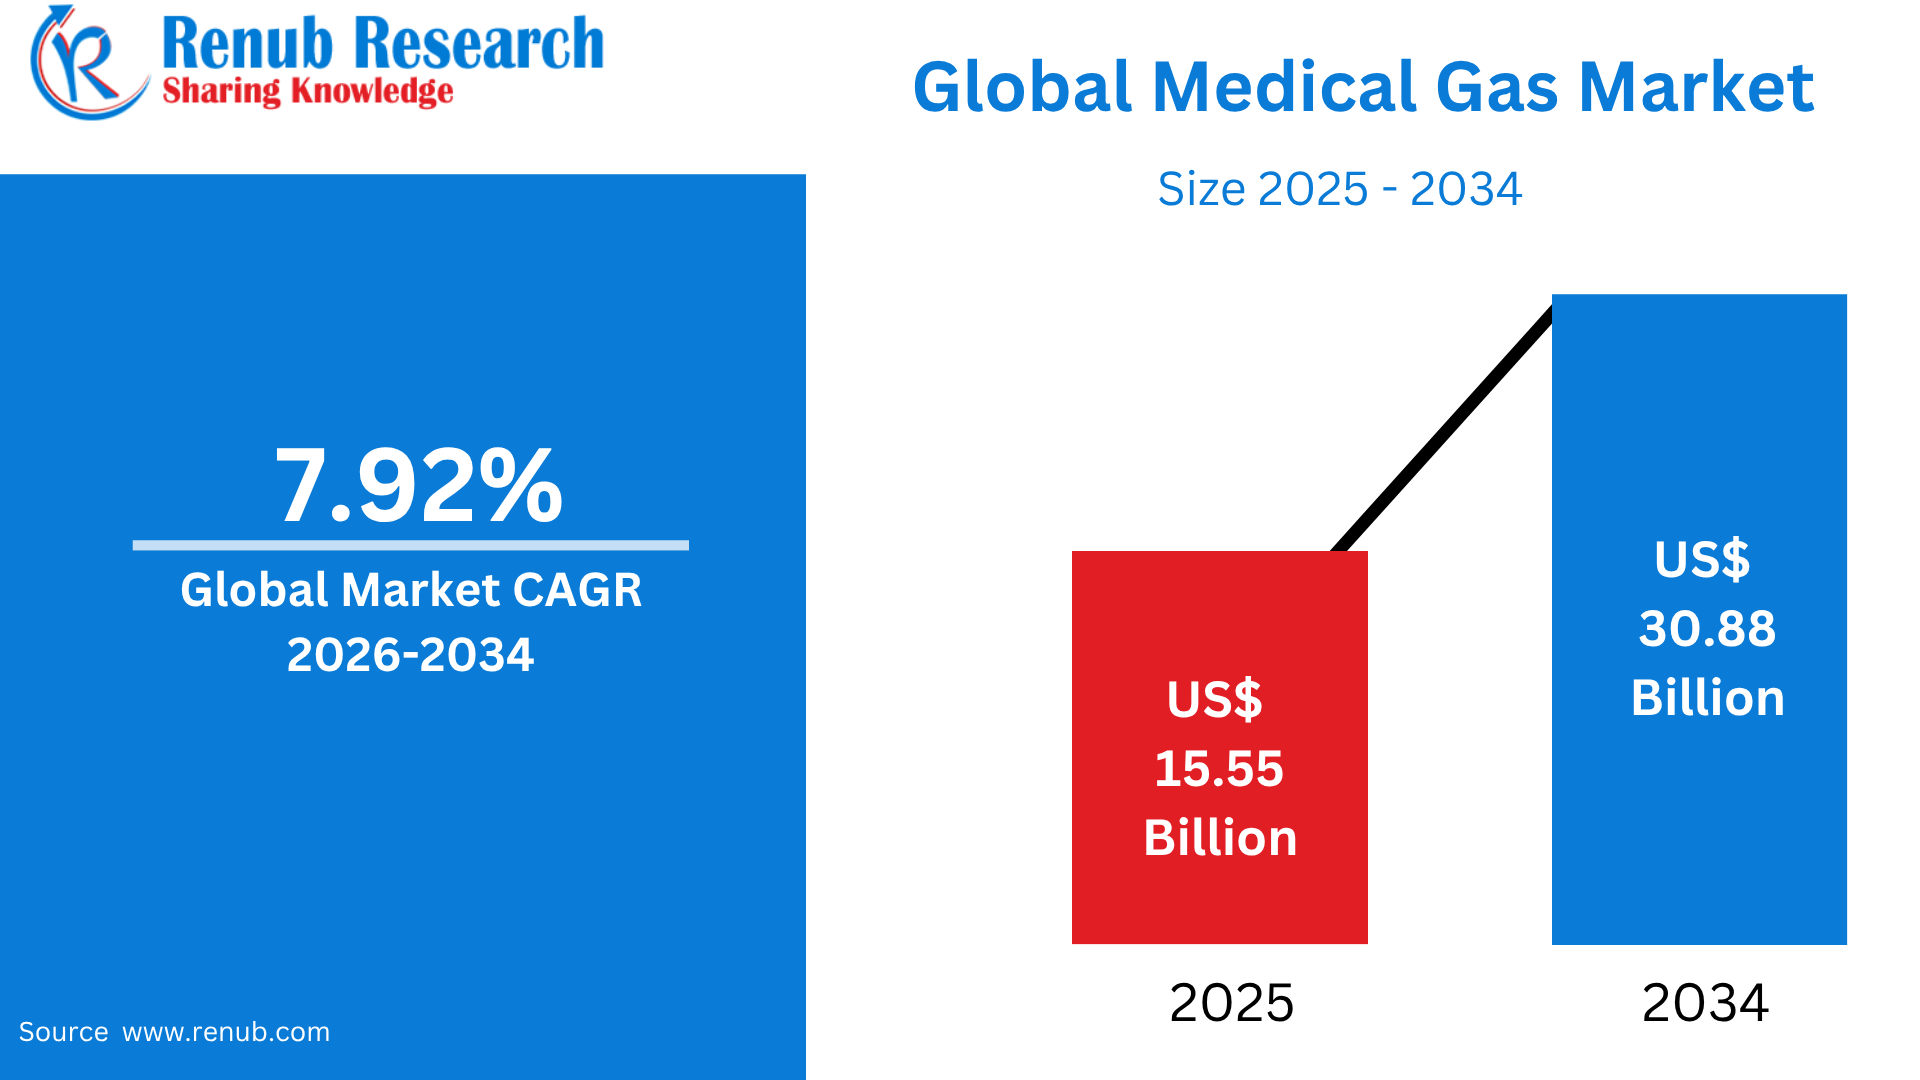
The Medical Gas Market is projected to grow from US$ 15.55 billion in 2025 to US$ 30.88 billion by 2034, expanding at a CAGR of 7.92% during 2026–2034. The market is anticipated to witness robust growth throughout the forecast period, driven by the expansion of healthcare infrastructure, increasing surgical and diagnostic procedures, the rising prevalence of respiratory and chronic diseases, and growing demand for reliable medical gas systems across hospitals and healthcare facilities. In addition, advancements in healthcare delivery and the increasing adoption of specialized patient-care services are expected to further support market expansion.
What is Medical Gas and its Uses & Popularity Worldwide
Medical gas refers to high-purity gases manufactured, stored, distributed, and administered for healthcare applications. Major medical gases include oxygen, nitrous oxide, medical air, carbon dioxide, nitrogen, and specialty gas mixtures. Among these, medical oxygen is the most critical because the World Health Organization (WHO) classifies it as an essential medicine with no substitute. It is widely used for respiratory therapy, anesthesia, emergency care, intensive care, surgery, trauma treatment, neonatal care, and chronic respiratory disease management. Medical gases are delivered through cylinders, centralized pipeline systems, oxygen concentrators, and on-site generation plants.
Medical gases are increasingly important worldwide because healthcare systems are expanding hospital capacity, critical-care infrastructure, emergency services, and surgical facilities. WHO reports that chronic respiratory diseases affect more than 500 million people globally, creating substantial demand for respiratory support. In addition, oxygen is required across virtually every level of healthcare, including primary-care facilities, general wards, operating rooms, emergency transportation, delivery rooms, and ICUs. However, access remains uneven, particularly in developing countries, where fewer than half of health facilities in many low- and middle-income countries have uninterrupted oxygen access.
Growth Drivers of the Medical Gas Market
Rising Burden of Respiratory and Chronic Diseases
The increasing prevalence of respiratory and chronic diseases is a major driver of worldwide medical gas demand, particularly for medical oxygen. Oxygen therapy is routinely required for patients experiencing hypoxemia associated with pneumonia, COPD, asthma, severe infections, and other respiratory conditions. WHO reports that chronic respiratory diseases, including COPD and asthma, affect more than half a billion people globally and remain a leading cause of disability and premature death. COPD alone caused approximately 3.4 million deaths worldwide in 2023, representing around 6% of global deaths. These disease trends increase requirements for oxygen cylinders, concentrators, oxygen-generation systems, pipeline infrastructure, and related delivery equipment. Demand is particularly important in hospitals, emergency departments, ICUs, and home-care settings. As populations age and exposure to tobacco smoke and air pollution continues to contribute to respiratory illness, healthcare providers are expected to expand oxygen-treatment capacity. Consequently, the growing global respiratory disease burden is supporting sustained consumption of medical gases.
Expansion of Surgical, Emergency, and Critical-Care Services
Growing surgical activity and investment in emergency and critical-care infrastructure are strengthening demand for medical gases worldwide. Oxygen is essential during surgery, trauma treatment, anesthesia, intensive care, and emergency transportation, while nitrous oxide and other gases are used in specific anesthesia and clinical applications. WHO estimates that around 5 billion people globally still lack access to safe, affordable surgical and anesthesia care, demonstrating a substantial unmet healthcare infrastructure requirement. Expanding hospitals and healthcare facilities in emerging economies are therefore investing in centralized medical-gas pipelines, storage systems, oxygen-generation plants, cylinders, and gas-management equipment. Medical oxygen is required across operating theaters, ICUs, emergency departments, maternity units, general wards, and specialized hospitals. As governments and healthcare organizations work to improve surgical capacity and emergency preparedness, medical-gas infrastructure is becoming an increasingly important component of hospital construction and modernization. This expansion is expected to generate recurring demand for gases, distribution systems, monitoring equipment, and maintenance services.
Increasing Focus on Reliable Oxygen Infrastructure and Healthcare Access
The global focus on reliable medical oxygen infrastructure is another important growth driver. The COVID-19 pandemic highlighted the consequences of inadequate oxygen production, storage, distribution, and delivery systems, encouraging governments and healthcare organizations to strengthen medical-gas infrastructure. WHO estimates that fewer than half of health facilities in low- and middle-income countries have uninterrupted access to medical oxygen. This gap is encouraging investments in oxygen concentrators, pressure swing adsorption (PSA) plants, liquid oxygen systems, cylinders, centralized pipelines, monitoring equipment, and maintenance programs. WHO notes that oxygen systems require coordinated production, storage, distribution, regulation, delivery, quality assurance, and patient monitoring. In addition, governments are increasingly incorporating oxygen into essential healthcare planning and strengthening local production capabilities to reduce supply disruptions. Rising healthcare expenditure and expansion of hospitals in developing economies are further supporting these investments. As healthcare systems prioritize resilience and continuous availability of essential medicines, demand for dependable medical-gas infrastructure is expected to remain strong.
Challenges of the Medical Gas Market
High Infrastructure, Installation, and Maintenance Costs
High capital and operating costs can constrain the expansion of medical-gas infrastructure, particularly in developing and resource-constrained healthcare systems. Medical gases require specialized production, storage, transportation, pipeline distribution, pressure regulation, monitoring, and safety equipment. Oxygen systems can involve concentrators, PSA plants, liquid oxygen tanks, cylinders, compressors, pipelines, alarms, and backup systems, increasing initial investment requirements. WHO identifies limited production, unreliable power supplies, inadequate equipment, poor storage facilities, insufficient funding, and limited technical expertise as barriers to reliable medical oxygen access. Healthcare facilities must also allocate funds for preventive maintenance, equipment replacement, leak detection, quality testing, and personnel training. Smaller hospitals and facilities in rural or remote areas may find these requirements particularly difficult to finance. Furthermore, continuous electricity is essential for many oxygen-generation systems, creating additional operating costs in regions with unreliable power infrastructure. These financial and infrastructure constraints can slow the adoption of advanced medical-gas systems and create disparities in access between well-funded urban hospitals and underserved healthcare facilities.
Stringent Safety, Quality, and Supply-Chain Requirements
Medical gases require stringent quality-control and safety procedures because incorrect gas composition, contamination, improper storage, or distribution failures can directly endanger patients. Medical oxygen is not interchangeable with industrial oxygen; WHO emphasizes that medicinal oxygen must meet authorized specifications for identity, purity, and content and must be produced, stored, and distributed under appropriate quality practices. Healthcare providers therefore need reliable gas identification, pressure control, pipeline integrity, cylinder handling, monitoring, and quality assurance. Supply-chain disruptions can also affect availability, particularly where healthcare facilities depend on external suppliers or long-distance transportation. WHO identifies availability, quality, affordability, management, supply, workforce capacity, and safety as major challenges affecting oxygen access. These requirements increase operational complexity for hospitals and medical-gas suppliers. Staff must also be adequately trained to operate and maintain equipment safely. Consequently, regulatory compliance, quality assurance, transportation requirements, and the need for uninterrupted supply can increase costs and create operational challenges across the global medical gas market.
Medical Gas Hospital Launches / Projects Worldwide
- Midland Metropolitan University Hospital (UK) – 2024: Opened to patients on 6 October 2024 with a large medical gas pipeline system serving 736 beds, 13 theatres, endoscopy and catheter-lab areas. The system included medical and surgical air, vacuum, oxygen backup, nitrous oxide, Entonox and CO₂ systems.
- New Wing of Durdans Hospital, Colombo (Sri Lanka) – 2024: A new hospital wing received a complete piped medical gas system, together with critical theatre and ICU equipment.
- Aga Khan Hospital, Kisumu (Kenya) – 2024: A new building received a complete medical gas system, including medical gas piping, plants, manifolds, bedheads and theatre pendants, completed in April 2024.
- Aga Khan Hospital Cancer Center, Dar es Salaam (Tanzania) – 2024: The new cancer center received a complete medical gas installation, including medical gas piping, AVSUs and bedheads, completed in July 2024.
- University of Jaffna Faculty of Medicine (Sri Lanka) – 2025: A new medical gas pipeline system was installed for the Faculty of Medicine, supporting four fully equipped operating theatres.
- Lady Ridgeway Hospital for Children, Colombo (Sri Lanka) – 2025: The Little Hearts Project included installation of a comprehensive medical gas pipeline system for a new Cardiac and Critical Care Complex, featuring theatre and ICU facilities.
- Vikram Hospital, Madurai (India) – 2025: A medical gas pipeline installation project was completed, with work commencing on 27 March 2025.
- Pandian Hospital, Madurai (India) – 2025: A medical gas pipeline installation project was completed after commencing on 21 July 2025, supporting the hospital’s medical-gas infrastructure.
- Sugapriya Hospital, Madurai (India) – 2025: A medical gas pipeline installation project was completed following commencement on 5 May 2025, strengthening centralized medical-gas delivery capabilities.
- District Hospital Chengannur, Kerala (India) – 2025: WAPCOS issued a tender for the supply, installation, testing and commissioning of a centralized medical gas pipeline system, with an estimated project value of ₹2.24 crore.
Dominance of Pure Gases in Medical Gas Consumption
The pure medical gas segment represents a major component of the medical gas industry and includes oxygen, nitrogen, nitrous oxide, carbon dioxide, helium, and medical air. Among these, oxygen remains the most important gas because it is widely required for respiratory therapy, anesthesia, emergency care, intensive care, surgery, neonatal care, and trauma treatment. Industry estimates indicate that pure gases account for approximately 68% of the global medical gases market, highlighting their broad utilization across healthcare facilities. Oxygen can be supplied through cylinders, bulk liquid oxygen systems, pressure swing adsorption (PSA) plants, and oxygen concentrators. Medical oxygen produced through air-liquefaction processes generally requires oxygen purity of at least 99.5%, while PSA systems commonly produce approximately 93% ±3% oxygen. Demand is further supported by the increasing number of hospitals, surgical centers, intensive care units, and homecare patients requiring oxygen therapy. The widespread application of pure gases across different levels of healthcare makes this segment a fundamental revenue contributor to the global medical gas market. The growing prevalence of respiratory disorders is strengthening demand for pure medical gases, particularly oxygen. Chronic respiratory diseases affect more than 500 million people globally, creating substantial long-term requirements for respiratory treatment and oxygen-support equipment. COPD alone caused approximately 3.4 million deaths worldwide in 2023, representing about 6% of all global deaths. Pure medical oxygen is also essential for patients experiencing hypoxemia associated with pneumonia, severe respiratory infections, trauma, and other acute conditions. In hospitals, oxygen is routinely supplied to emergency departments, operating theaters, intensive care units, general wards, delivery rooms, and specialized treatment units. Increasing adoption of non-invasive ventilation, mechanical ventilation, oxygen concentrators, and portable oxygen systems is expanding the use of pure gases beyond traditional hospitals. Consequently, investments in centralized medical gas pipeline systems, on-site oxygen generation plants, bulk storage facilities, and cylinder distribution networks are supporting sustained growth in the pure medical gas segment.
Growing Use of Specialized Gas Mixtures in Healthcare
Medical gas mixtures are specially formulated combinations of two or more gases used for therapeutic, diagnostic, anesthesia, respiratory, and laboratory applications. Important categories include medical drug gas mixtures, lung-diffusion mixtures, blood-gas mixtures, aerobic and anaerobic mixtures, and medical laser mixtures. Gas mixtures represent approximately 32% of the global medical gases market, demonstrating their growing importance within specialized healthcare applications. Unlike conventional pure gases, mixtures can be manufactured at precisely controlled concentrations to support specific clinical or diagnostic requirements. For example, oxygen-nitrogen mixtures can be used in pulmonary testing, while other combinations support blood-gas calibration and respiratory diagnostics. Demand is increasing as hospitals and diagnostic laboratories adopt sophisticated pulmonary-function testing, respiratory monitoring, anesthesia systems, and laboratory analyzers. The segment is also benefiting from the expansion of specialized healthcare services and technological improvements in gas blending, cylinder filling, quality control, and automated monitoring systems. The increasing adoption of advanced diagnostic procedures is creating new opportunities for medical gas mixtures. Lung-diffusion mixtures are used in pulmonary function testing to evaluate how effectively gases move from the lungs into the bloodstream, while specialized blood-gas mixtures support calibration and quality control of blood-gas analyzers. Medical gas mixtures are also utilized in anesthesia, respiratory therapy, neonatal care, and controlled clinical environments. Industry market estimates indicate that gas mixtures are among the faster-growing product categories within the medical gas industry, supported by rising demand for specialized diagnostics and respiratory treatment. Growing healthcare expenditure, modernization of laboratories, and increasing adoption of automated diagnostic equipment are encouraging hospitals to establish reliable supplies of certified gas mixtures. At the same time, manufacturers are focusing on precise gas composition, improved cylinder technology, traceability, and quality assurance. These developments are strengthening demand for customized medical gas mixtures across hospitals, diagnostic laboratories, research facilities, and specialized healthcare centers.
Rapid Growth of Diagnostic Medical Gas Applications
Medical gas diagnostics refers to the use of specialized medical gases and gas mixtures in diagnostic procedures, laboratory testing, pulmonary-function assessment, blood-gas analysis, and calibration of medical diagnostic instruments. The global diagnostics application segment of the medical gas market was valued at approximately US$5.81 billion in 2024 and is projected to reach around US$9.67 billion by 2030, representing a CAGR of approximately 9% during the forecast period. Diagnostic applications require highly controlled gas compositions to ensure reliable and reproducible test results. Lung-diffusion gas mixtures, blood-gas mixtures, aerobic mixtures, anaerobic mixtures, and specialized calibration gases are increasingly used in hospitals and diagnostic laboratories. Rising demand for pulmonary diagnostics is particularly important because respiratory disorders continue to affect a large global patient population. Increasing healthcare screening, laboratory automation, and adoption of advanced analyzers are also creating demand for high-purity diagnostic gases. As diagnostic infrastructure expands, medical gas suppliers are increasingly developing standardized and application-specific gas mixtures. The expansion of respiratory diagnostics and laboratory testing is a major contributor to the medical gas diagnostics segment. Diagnostic gas mixtures are essential for calibrating analyzers and conducting controlled tests where precise concentrations of oxygen, carbon dioxide, nitrogen, helium, or other gases are required. The growing burden of COPD, asthma, pneumonia, and other respiratory conditions is increasing the need for pulmonary-function testing and lung-diffusion assessments. North America represented the largest regional market for diagnostic medical gases in 2024, while China is expected to record one of the strongest growth rates through 2030. Hospitals, independent diagnostic laboratories, research institutions, and specialized pulmonary centers are increasing investments in automated analyzers and testing equipment, creating recurring demand for calibration gases and certified mixtures. Furthermore, tighter laboratory quality-control requirements are encouraging healthcare providers to use accurately prepared and traceable gas mixtures, supporting long-term demand for specialized diagnostic medical gases.
Hospitals Remain the Primary End User of Medical Gases
Hospitals represent the largest and most important end-use environment for medical gases because multiple departments require continuous and reliable gas supplies. Industry estimates indicate that hospitals account for approximately 46% of the global medical gases market, reflecting their extensive consumption of oxygen, nitrous oxide, medical air, carbon dioxide, nitrogen, and vacuum systems. Medical gases are essential in operating rooms, intensive care units, emergency departments, neonatal units, respiratory wards, recovery areas, and diagnostic departments. Oxygen is particularly important because it is required for respiratory therapy, anesthesia, surgery, trauma management, and critical care. Modern hospitals increasingly use medical gas pipeline systems to distribute gases from centralized sources directly to patient-care areas. These systems generally incorporate gas sources, storage, pressure regulation, valves, alarms, pipelines, and bedside outlets. The increasing number of hospital procedures, expansion of critical-care capacity, and modernization of healthcare infrastructure are therefore supporting continued demand for medical gas systems and associated equipment. The expansion and modernization of hospitals is creating sustained opportunities for medical gas suppliers, pipeline-system manufacturers, equipment providers, and gas producers. Medical gas infrastructure is increasingly incorporated into new hospital construction and renovation projects to provide uninterrupted gas availability across patient-care areas. In India, national medical oxygen guidelines recommend medical gas pipeline systems for hospitals with more than 50 beds, demonstrating the importance of centralized gas infrastructure in larger healthcare facilities. Globally, hospitals are also investing in oxygen-generation plants, bulk liquid oxygen storage, cylinder backup systems, automated alarm systems, and digital monitoring technologies. The need for reliable oxygen has become particularly significant because WHO estimates that fewer than half of healthcare facilities in low- and middle-income countries have uninterrupted access to medical oxygen. Growing healthcare expenditure, increasing surgical volumes, expansion of intensive-care capacity, and the development of specialty hospitals are therefore expected to maintain hospitals as the dominant end-use segment of the medical gas market.
Advanced Healthcare Infrastructure and High Demand for Medical Gases in USA
United States medical gas market is among the most developed worldwide, supported by extensive hospital infrastructure, high healthcare expenditure, and advanced clinical technologies. Medical oxygen, nitrogen, nitrous oxide, carbon dioxide, and medical air are widely used across hospitals, ambulatory surgical centers, specialty clinics, emergency departments, and home healthcare. According to the American Hospital Association, U.S. hospitals recorded approximately 33.9 million inpatient admissions in 2022, supporting substantial requirements for oxygen, anesthesia gases, and respiratory-care systems. The country’s aging population and high prevalence of chronic respiratory conditions further sustain demand for oxygen therapy and respiratory-support equipment. In addition, the expansion of home healthcare is increasing the use of portable oxygen concentrators and cylinders outside traditional hospital settings. Large suppliers, including Air Products and Linde, continue investing in gas-production capacity, distribution networks, monitoring technologies, and sustainability initiatives. Strong regulatory requirements for gas purity, pipeline safety, storage, and delivery also encourage healthcare providers to upgrade medical-gas infrastructure.
Aging Population and Modern Hospital Infrastructure Supporting Germany Demand
Germany’s medical gas market benefits from its highly developed healthcare system, extensive hospital network, and strong emphasis on patient safety and medical technology. Medical gases are essential across operating rooms, intensive-care units, emergency departments, respiratory-care facilities, and diagnostic environments. Germany has one of Europe’s oldest populations, with people aged 65 years and over accounting for roughly one-fifth of the population, increasing the need for healthcare services associated with chronic and age-related diseases. Respiratory conditions, surgical procedures, and critical-care treatments consequently support consistent consumption of medical oxygen and other clinical gases. The country also maintains rigorous requirements concerning the production, handling, storage, distribution, and quality of medicinal gases. Hospitals increasingly invest in centralized pipeline systems, automatic pressure monitoring, alarm systems, and efficient gas-management technologies to improve reliability and patient safety. Germany’s advanced manufacturing capabilities and established healthcare infrastructure also provide opportunities for domestic and international medical-gas companies. Growing hospital modernization and demand for specialized treatments are expected to sustain the country’s medical gas market.
Healthcare Expansion and Increasing Hospital Capacity Accelerating China Market Growth
China represents a major growth opportunity for the medical gas industry because of its rapidly expanding healthcare infrastructure, increasing healthcare expenditure, and growing demand for advanced clinical services. China’s healthcare system has expanded substantially, with the country having more than 1.1 million medical and health institutions in 2023, including hospitals and primary healthcare facilities. Medical gases are increasingly required in operating theaters, intensive-care units, emergency departments, respiratory-treatment centers, and diagnostic facilities. The country’s large population and increasing prevalence of chronic diseases are creating additional demand for respiratory-support solutions and oxygen therapy. Government investment in healthcare modernization, hospital construction, and improved access to medical services is encouraging facilities to install centralized medical-gas pipeline networks and modern oxygen-generation systems. In addition, domestic manufacturers and international suppliers are expanding production, distribution, and technical-service capabilities to serve regional healthcare markets. As hospitals increasingly adopt advanced medical technologies and strengthen critical-care capacity, demand for medical oxygen, medical air, nitrous oxide, nitrogen, and associated gas-delivery equipment is expected to increase.
Healthcare Modernization and Medical Tourism Strengthening United Arab Emirates Market Demand
The United Arab Emirates medical gas market is supported by substantial investment in healthcare infrastructure, advanced hospitals, specialized treatment centers, and medical tourism. Medical gases are extensively used for anesthesia, respiratory therapy, intensive care, emergency treatment, surgery, and other clinical applications. The UAE has a population of more than 11 million, creating a growing healthcare-services base, while the country’s strategy of developing world-class healthcare facilities has encouraged investment in technologically advanced hospitals and specialty centers. Dubai and Abu Dhabi are particularly important healthcare hubs, with hospitals increasingly adopting centralized medical-gas pipeline systems, automated monitoring, pressure-control technologies, and high-quality gas-storage infrastructure. Medical tourism also contributes to demand as the country expands specialized services in areas such as oncology, cardiology, surgery, and rehabilitation. Government initiatives emphasizing healthcare quality, patient safety, and digital transformation further encourage modernization of medical-gas systems. As healthcare capacity expands and the UAE continues positioning itself as a regional medical hub, demand for dependable medical oxygen, medical air, nitrous oxide, and related gas-management equipment is expected to grow steadily.
Recent Developments in Medical Gas Market
- In The British business Medi-teknique Ltd. ("Medi-teknique"), which specializes in medical gas maintenance and services, was acquired by Atlas Copco Group in January 2025. The business increased its presence in the UK with this acquisition.
- In order to help hospitals and clinics in six European nations—Germany, Belgium, France, Italy, the Netherlands, and Spain—reduce their carbon footprint, Air Liquide announced in January 2025.
Market Segmentations
Product
- Pure Gases
- Gas Mixtures
Application
- Therapeutics
- Diagnostics
- Others
End Use
- Hospitals
- Pharmaceutical & Biotechnology Companies
- Ambulatory Surgical Centers
- Diagnostic & Research Laboratories
- Academic & Research Institutes
- Home Healthcare
Countries
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Thailand
- Malaysia
- Indonesia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
All the Key players have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Air Liquide
- Linde PLC
- Atlas Copco Group
- INOX-Air Products Inc.
- TAIYO NIPPON SANSO CORPORATION
- MATHESON TRI-GAS, INC.
- HORIBA Group
- SOL India Private Limited
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Product, Application, End Use and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.