Intraoperative Imaging Market Report by Product, Application, End Use, Countries and Companies Analysis 2026-2034
Buy NowIntraoperative Imaging Market Size and Forecast
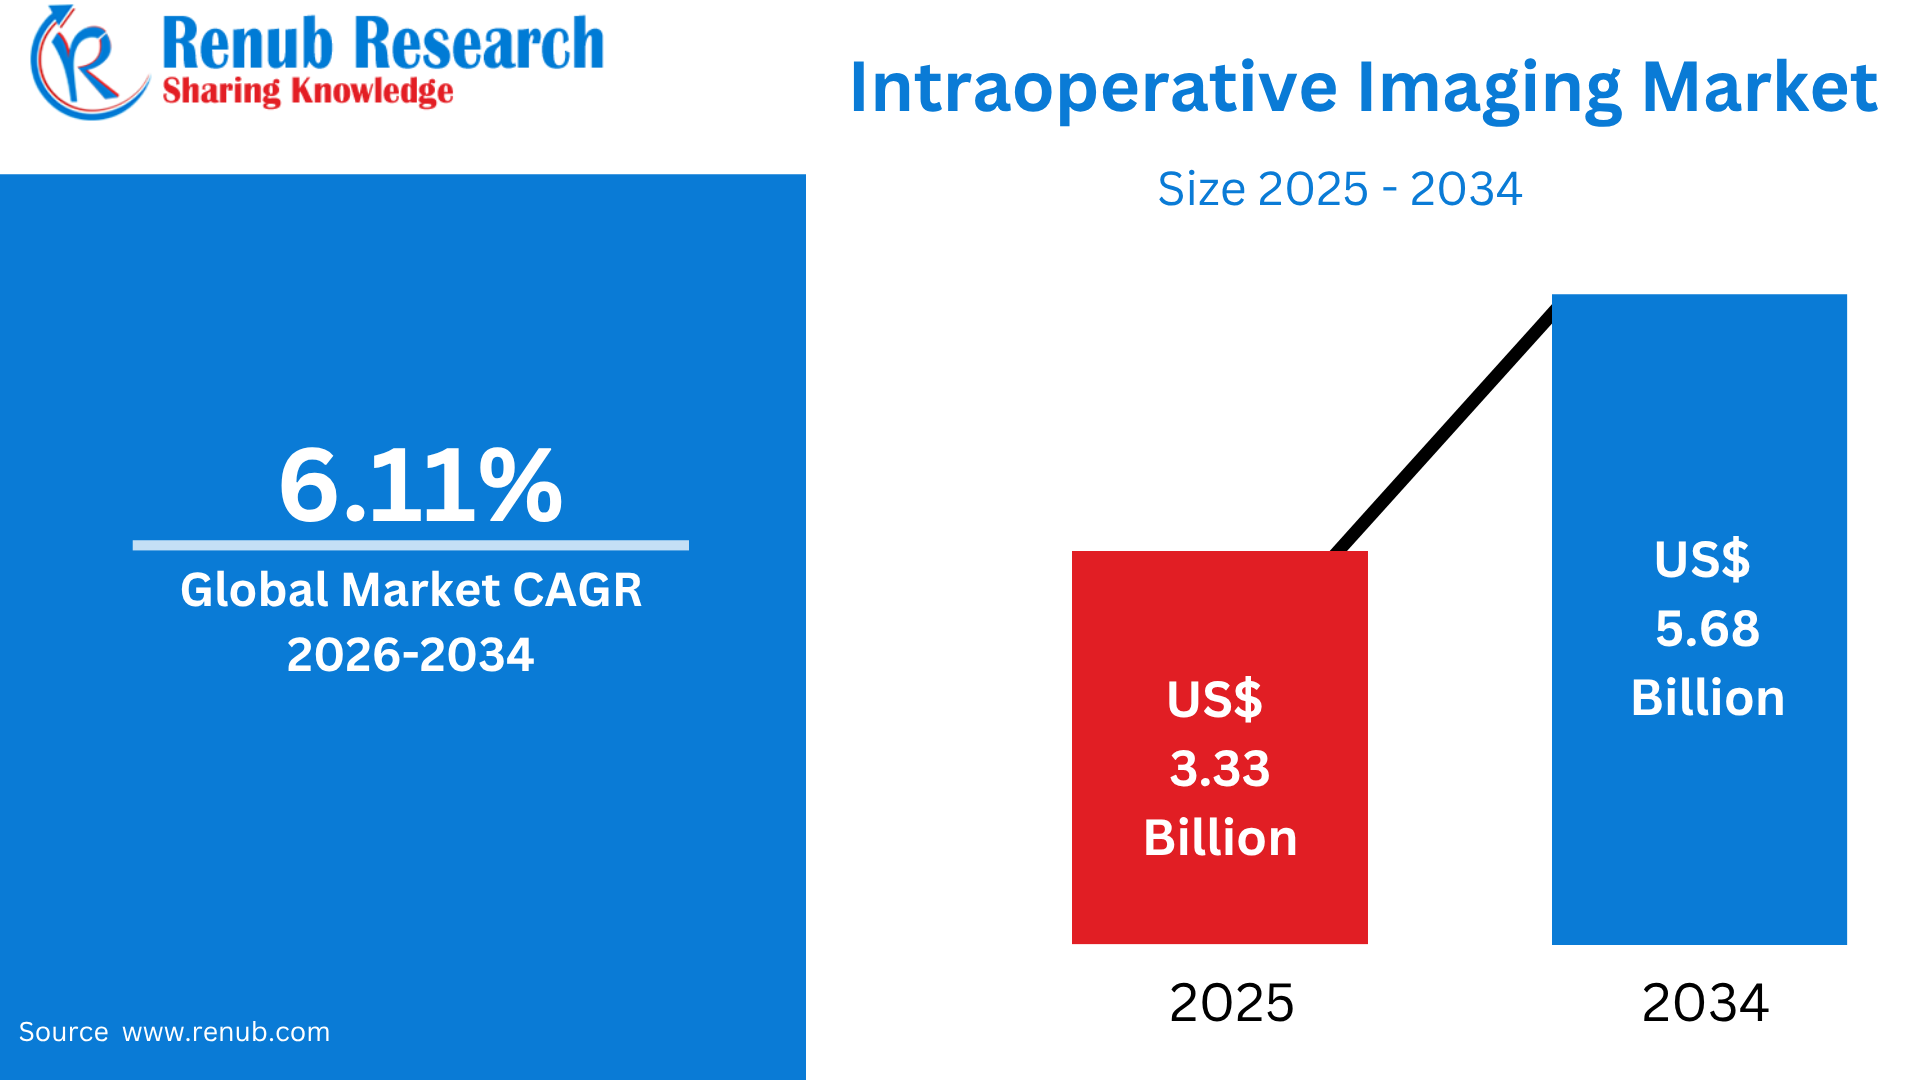
The Intraoperative Imaging Market is projected to grow from US$ 3.33 billion in 2025 to US$ 5.68 billion by 2034, registering a CAGR of 6.11% during 2026–2034. The market is expected to witness steady expansion as healthcare providers increasingly prioritize surgical precision, real-time visualization, and improved procedural outcomes. Growing adoption of image-guided surgical techniques, technological advancements in intraoperative imaging systems, and the increasing preference for minimally invasive procedures are key factors supporting market growth.
What is Intraoperative Imaging and its Uses & Popularity Worldwide
Intraoperative imaging refers to medical imaging technologies used during surgical procedures to provide surgeons with real-time or near-real-time visualization of anatomical structures, surgical sites, and treatment progress. These systems include intraoperative MRI, CT, ultrasound, fluoroscopy, mobile C-arms, optical imaging, and other advanced image-guided technologies.
Intraoperative imaging is used extensively in neurosurgery, orthopedics, cardiovascular surgery, oncology, spine surgery, ENT procedures, and minimally invasive interventions. It enables surgeons to identify anatomical structures more accurately, assess tumor margins, verify implant positioning, monitor surgical progress, and reduce the need for repeat procedures. Its popularity is increasing as healthcare providers focus on surgical precision, patient safety, shorter hospital stays, and minimally invasive treatment approaches.
Globally, the demand for surgical care remains substantial, with the WHO estimating that approximately 143 million additional surgical procedures are needed annually to save lives and prevent disability. The growing integration of advanced imaging with surgical navigation, robotics, artificial intelligence, and digital operating-room systems is further expanding the role of intraoperative imaging worldwide.
Growth Driver in the Market
Growing Demand for Image-Guided and Minimally Invasive Surgery
The increasing adoption of image-guided and minimally invasive surgical procedures is a major growth driver for the Intraoperative Imaging Market. Surgeons increasingly require real-time visualization to navigate complex anatomical structures while minimizing tissue damage and improving procedural accuracy. Intraoperative imaging systems can provide immediate information during surgery, supporting procedures in neurosurgery, orthopedics, oncology, cardiovascular surgery, and spinal interventions. The global need for surgical care also provides a substantial underlying opportunity. The WHO estimates that approximately 313 million surgical procedures are performed globally each year, while another 143 million procedures are required annually in low- and middle-income countries to save lives and prevent disability. As surgical volumes increase and healthcare systems prioritize improved outcomes, hospitals are investing in advanced visualization and navigation technologies. The shift toward minimally invasive procedures further strengthens demand because these techniques often depend on accurate anatomical guidance. Consequently, intraoperative MRI, CT, ultrasound, fluoroscopy, and other imaging platforms are becoming increasingly integrated into modern operating rooms.
Technological Advancements and Integration with Surgical Navigation
Rapid technological advancements are significantly supporting the expansion of the Intraoperative Imaging Market. Modern systems increasingly combine high-resolution imaging, surgical navigation, artificial intelligence, robotics, three-dimensional visualization, and real-time data analysis to provide surgeons with more detailed information during procedures. Advanced intraoperative MRI and CT systems can help surgeons assess treatment progress and identify residual disease, while intraoperative ultrasound and fluoroscopy provide immediate visualization in procedures where continuous guidance is required. Integration with navigation platforms enables imaging data to be mapped to the patient’s anatomy, supporting more accurate instrument positioning and treatment planning. The development of compact, mobile, and hybrid imaging systems is also making advanced imaging more adaptable to different operating-room environments. At the same time, AI-assisted image interpretation can help identify anatomical structures and abnormalities more efficiently. These technological improvements are increasing the clinical utility of intraoperative imaging beyond conventional visualization. As hospitals modernize operating rooms and adopt digitally connected surgical environments, demand for integrated imaging platforms is expected to increase across major surgical specialties.
Rising Focus on Surgical Safety and Improved Patient Outcomes
Increasing emphasis on surgical safety, precision, and patient outcomes is another important factor driving adoption of intraoperative imaging technologies. Real-time imaging allows surgical teams to evaluate anatomical structures and procedural results while an operation is still underway, potentially helping surgeons make timely adjustments. This is particularly valuable in complex procedures involving the brain, spine, tumors, blood vessels, and orthopedic implants. Improved visualization can support more accurate removal of targeted tissue, verification of implant placement, and identification of complications or residual abnormalities. The importance of strengthening surgical systems is highlighted by the WHO, which estimates that 5 billion people worldwide lack access to safe, affordable surgical and anesthesia care and that 143 million additional surgeries are needed annually. Although access challenges remain, healthcare systems that have advanced surgical infrastructure are increasingly focusing on technologies capable of improving procedural quality and efficiency. Intraoperative imaging can also reduce uncertainty during complex interventions and potentially decrease the need for additional procedures. Consequently, hospitals and surgical centers are increasingly evaluating advanced imaging as part of broader investments in safer, technology-enabled operating rooms.
Challenges in the Market
High Capital and Infrastructure Requirements
High initial investment and infrastructure requirements represent a significant challenge for the Intraoperative Imaging Market, particularly for smaller hospitals and healthcare facilities in emerging economies. Advanced intraoperative MRI, CT, and hybrid imaging systems require substantial expenditure on equipment, operating-room modification, installation, maintenance, software, and specialized accessories. Hospitals may also need dedicated space, appropriate shielding, upgraded electrical infrastructure, specialized cooling systems, and integration with surgical navigation platforms. In addition to the equipment cost, healthcare providers must invest in training surgeons, radiologists, technologists, and operating-room personnel to use these systems effectively. These financial requirements can limit adoption where healthcare budgets are constrained. The challenge is particularly relevant because global access to surgical infrastructure remains uneven. The WHO reports that approximately 5 billion people lack access to safe and affordable surgical and anesthesia care, highlighting major infrastructure and resource disparities worldwide. Consequently, advanced intraoperative imaging is more readily adopted by well-funded tertiary hospitals and specialized surgical centers, while smaller institutions may continue relying on conventional or mobile imaging technologies.
Limited Skilled Workforce and Complex System Integration
The shortage of specialized professionals and complexity of integrating imaging technologies into surgical workflows can restrict market adoption. Intraoperative imaging requires coordinated expertise from surgeons, radiologists, imaging technologists, biomedical engineers, IT teams, and other operating-room personnel. Advanced systems also need appropriate training to ensure that imaging data are acquired, interpreted, and integrated correctly during time-sensitive procedures. Integrating imaging platforms with electronic medical records, surgical navigation systems, robotic equipment, hospital networks, and operating-room infrastructure can further increase technical complexity. Inadequate training may reduce utilization and limit the return on expensive equipment investments. The broader healthcare workforce challenge adds pressure to this issue. WHO projections indicate a potential shortfall of 11.1 million health workers globally by 2030, although this figure covers the overall health workforce rather than intraoperative imaging specialists specifically. Healthcare providers therefore need to invest not only in imaging hardware but also in workforce training, technical support, cybersecurity, interoperability, and maintenance capabilities. These requirements can slow adoption, particularly in hospitals with limited specialized personnel and technical infrastructure.
Intraoperative Imaging Launches Worldwide
Siemens Healthineers – CIARTIC Move
March 2024 | United States/Worldwide
Siemens Healthineers introduced CIARTIC Move, an automated, self-driving mobile C-arm designed for intraoperative imaging. The system uses a fully motorized chassis and omnidirectional wheels for precise positioning in operating rooms. It supports both 2D fluoroscopy and 3D cone-beam CT and can automatically return to previously stored positions. Siemens reported that automated positioning can enable up to 50% faster intraoperative imaging in procedures such as spine, pelvic, and distal-radius surgery.
Philips – Zenition 90 Motorized
February 2024 | Europe/Worldwide
Philips launched the Zenition 90 Motorized mobile C-arm at ECR 2024. The system delivers 25 kW of power and is designed for complex vascular procedures as well as cardiac interventions, pain management, and urology. Its motorized operation and table-side controls allow surgical teams to control C-arm movement more efficiently. Philips also incorporated automated workflow features intended to improve procedural productivity and visualization while supporting high-quality imaging.
IMRIS – InVision 1.5 Surgical Theatre
February 2024 | United States
IMRIS received FDA 510(k) clearance for the InVision 1.5 Surgical Theatre, a ceiling-mounted 1.5T intraoperative MRI system. The system is designed for multi-room operating suites and provides high-quality imaging during surgical procedures, particularly neurosurgery. Its ceiling-mounted configuration enables MRI access during surgery while supporting integration within a broader surgical environment. The launch strengthens the availability of intraoperative MRI for hospitals seeking advanced real-time imaging capabilities for neurological procedures.
Medtronic – O-arm 4.3 Software
September 2024 | Worldwide
Medtronic introduced O-arm 4.3 software as part of its AiBLE spine-surgery ecosystem. The update added advanced navigation volumes, dose-reduction capabilities, and enhanced image confirmation. Medtronic stated that the system provides a 3D scan length of up to 43.8 cm, enabling additional levels of spinal anatomy to be captured in a single scan. The software also includes Spine Smart Dose, an AI-based algorithm designed to use approximately 70% less radiation than the standard protocol while maintaining image quality.
GE HealthCare – OEC 3D and Advanced Surgical Imaging Portfolio
December 2024 | Worldwide
GE HealthCare showcased its expanded surgical-imaging portfolio at RSNA 2024, highlighting the OEC 3D, OEC Elite CFD, OEC MiniView MAX, and OEC One CFD C-arm systems. The OEC 3D provides mobile cone-beam CT capabilities for intraoperative imaging, while the wider portfolio targets applications requiring real-time visualization during surgery. GE HealthCare also introduced its Advanced Visualization Solutions, combining ultrasound and image-guided therapies with digital and AI technologies to support diagnosis, treatment, intervention, and monitoring.
CMR Surgical – vLimeLite Imaging Technology
February 2024 | United Kingdom/Europe
CMR Surgical launched vLimeLite, an integrated fluorescence imaging technology for its Versius surgical robotics platform. The system uses indocyanine green (ICG) fluorescence to enhance visualization of anatomical structures and tissue perfusion during surgery. Versius Plus became the first CE-marked surgical robot to offer an integrated ICG system with multiple viewing modes and color displays. Gloucestershire Hospitals NHS Foundation Trust became the first facility to install the technology. The launch demonstrates the increasing convergence of intraoperative imaging, fluorescence visualization, and robotic surgery.
Stryker – 1788 Advanced Imaging Platform
September 2024 | India
Stryker launched its 1788 Advanced Imaging Platform in India, providing surgeons with high-resolution 4K visualization and advanced fluorescence imaging capabilities. The platform is designed to support multiple surgical specialties and improve visualization of anatomical structures during procedures. Its fluorescence functionality is intended to provide enhanced perfusion imaging and visualization of complex anatomy. The introduction illustrates the growing adoption of advanced surgical visualization platforms in emerging healthcare markets and the broader integration of high-definition imaging technologies into modern operating rooms.
Medtronic – O-arm Surgical Imaging System Expansion
2024 | Worldwide
Medtronic continued expanding the use of its O-arm Surgical Imaging System, a mobile intraoperative imaging platform capable of providing 2D and 3D imaging during spine, orthopedic trauma, and neurological procedures. The system can generate 360-degree imaging around the patient without requiring the patient to be moved. The technology is designed to support surgical navigation and provide real-time anatomical information during complex procedures. In 2024, healthcare institutions continued adopting O-arm systems to strengthen image-guided spine and cranial surgery capabilities.
BK Medical – bKActiv Intraoperative Ultrasound
June 2024 | India
Tata Memorial Centre in Mumbai acquired the bKActiv intraoperative ultrasound system, representing the first installation of this advanced system in India. The technology was acquired for complex brain-tumor surgeries, where intraoperative ultrasound can provide surgeons with real-time information during tumor removal. Intraoperative ultrasound is particularly valuable because it can provide immediate soft-tissue visualization without ionizing radiation. The installation demonstrates increasing adoption of advanced ultrasound-based intraoperative imaging in neurosurgery and highlights the growing role of cost-efficient real-time imaging technologies in specialized surgical centers.
Siemens Healthineers – CIARTIC Move First U.S. Installation
September 2024 | United States
Siemens Healthineers announced the first U.S. installation of CIARTIC Move at Tahoe Forest Health System in California. The fully motorized mobile C-arm was introduced to automate repositioning during surgery and reduce the manual workload associated with conventional C-arm operation. The system supports 2D fluoroscopy and 3D cone-beam CT, with applications spanning orthopedic, trauma, and spine surgery as well as thoracic, vascular, cardiovascular, general surgery, urology, and interventional pulmonology. The installation demonstrates the transition toward automated intraoperative imaging workflows designed to improve consistency and operating-room efficiency.
Dominant Modality for Real-Time Surgical Guidance
C-Arms Intraoperative Imaging Market represents a major segment of intraoperative imaging because of the technology’s flexibility, portability, and ability to provide real-time X-ray and fluoroscopic visualization during surgical procedures. C-arms are widely used in orthopedic, cardiovascular, spinal, trauma, pain-management, and vascular interventions. The C-arm segment accounted for approximately 31.1% of the global intraoperative imaging market revenue in 2024, making it the leading product category. Other market estimates indicate that mobile C-arms accounted for more than 42% of intraoperative imaging revenue in 2025, reflecting their broad procedural applications. C-arms enable surgeons to capture images from multiple angles without repositioning the patient, supporting implant placement, fracture fixation, catheter guidance, and other image-guided procedures. Technological developments such as digital flat-panel detectors, 3D imaging, improved image quality, radiation-dose reduction, and AI-assisted visualization are strengthening their clinical utility. Their comparatively lower infrastructure requirements than intraoperative MRI or CT also support adoption across hospitals, surgical centers, and specialty facilities.
Real-Time and Radiation-Free Visualization
Intraoperative Ultrasound Imaging Market is gaining importance as surgeons increasingly seek real-time visualization without ionizing radiation during complex procedures. Intraoperative ultrasound is particularly valuable in neurosurgery, oncology, abdominal surgery, cardiovascular procedures, and vascular interventions, where immediate visualization of soft tissues and blood flow can support surgical decision-making. The intraoperative ultrasound segment represented approximately 16% of global intraoperative imaging revenue in 2025, according to industry estimates, while another market assessment identifies it as one of the faster-growing imaging modalities through 2034. Advances in high-frequency probes, three-dimensional ultrasound, Doppler imaging, miniaturized systems, and AI-assisted image interpretation are expanding its applications. In neurosurgery, ultrasound can help surgeons visualize tumors and anatomical structures during procedures, while in vascular and cardiovascular surgery it can provide real-time assessment of blood flow. The portability and comparatively lower infrastructure requirements of ultrasound systems also make them attractive for hospitals and surgical centers. Increasing adoption of minimally invasive procedures and demand for rapid intraoperative feedback are expected to support continued market expansion.
Increasing Need for Precise Brain and Spine Procedures
Neurosurgery Intraoperative Imaging Market is a leading application segment of intraoperative imaging, driven by the complexity of brain and spinal procedures and the need for highly accurate anatomical visualization. Intraoperative imaging technologies such as iMRI, intraoperative CT, ultrasound, C-arms, and image-guided navigation systems enable surgeons to assess anatomical structures, monitor surgical progress, and verify treatment results during procedures. Neurosurgery accounted for approximately 30.8% of global intraoperative imaging market revenue in 2024, making it the largest application segment in several industry analyses. The technology is particularly valuable during tumor resection, epilepsy surgery, deep brain stimulation, spinal procedures, and other interventions where anatomical precision is critical. Intraoperative MRI provides high soft-tissue contrast and can help identify residual tumor tissue, while intraoperative CT supports bone and implant visualization. Integration with surgical navigation, robotics, artificial intelligence, and three-dimensional imaging is further enhancing surgical workflows. Growing neurological disease prevalence, increasing surgical volumes, and greater emphasis on precision and minimally invasive techniques are expected to sustain demand for intraoperative imaging in neurosurgery.
Hospitals Remain the Primary End-User Segment
Intraoperative Imaging Hospitals Market represents the largest end-user category because hospitals perform a high volume of complex surgical procedures requiring advanced real-time imaging capabilities. Hospitals deploy C-arms, intraoperative CT, intraoperative MRI, ultrasound, and other imaging systems across neurosurgery, orthopedics, cardiovascular surgery, oncology, trauma, and spine procedures. Industry estimates indicate that hospitals and clinics accounted for approximately 67.5% of global intraoperative imaging revenue in 2025, demonstrating their dominant position in equipment procurement and utilization. Another market assessment placed hospitals as the largest end-user segment, reflecting their ability to support capital-intensive imaging infrastructure and multidisciplinary surgical teams. Major hospitals are increasingly developing hybrid operating rooms that combine advanced imaging, surgical navigation, robotics, and digital patient-monitoring systems. Investments in hospital modernization and expansion of tertiary and specialty care facilities are further supporting adoption. Hospitals also benefit from centralized imaging services, trained clinical personnel, and established maintenance infrastructure. As surgical procedures become increasingly image-guided and minimally invasive, hospitals are expected to remain the principal users of intraoperative imaging technologies worldwide.
Advanced Surgical Infrastructure and High Procedure Volumes in USA
United States Intraoperative Imaging Market is supported by advanced healthcare infrastructure, high surgical volumes, and strong adoption of precision-based medical technologies. The country’s aging population is an important demand factor, with the proportion of Americans aged 65 years and older projected to reach approximately 22% by 2050. Age-related conditions increase the need for orthopedic, neurological, cardiovascular, and other complex surgical procedures that can benefit from real-time imaging. In 2022, the United States recorded more than 600,000 knee replacement procedures, while the number of people living with Alzheimer’s disease exceeded 6.2 million. Cardiovascular conditions also create substantial demand for advanced surgical interventions. According to the American Heart Association, cardiovascular disease caused approximately 928,741 deaths in the United States in 2020, with coronary heart disease accounting for 41.2%, stroke 17.3%, and heart failure 9.2% of CVD-related deaths. Increasing adoption of minimally invasive surgery, robotic-assisted procedures, surgical navigation, and advanced imaging-guided interventions is therefore supporting demand for intraoperative MRI, CT, ultrasound, and C-arm systems.
Germany Precision Surgery and Advanced Healthcare Infrastructure
Germany Intraoperative Imaging Market is supported by a highly developed healthcare system, advanced medical technology infrastructure, and strong demand for precision-based surgical procedures. Germany has one of Europe’s most mature hospital systems and is a major center for medical-device research and development. The country’s aging demographic is an important factor supporting demand for surgical technologies, particularly in orthopedics, neurosurgery, cardiovascular care, and oncology. Approximately 23% of Germany’s population is aged 65 years or older, creating a substantial patient base for procedures associated with age-related diseases. Intraoperative imaging systems are increasingly incorporated into specialized operating rooms to provide real-time visualization and improve surgical accuracy. C-arms are widely used in orthopedic and trauma procedures, while intraoperative CT, MRI, and ultrasound support complex neurological, spinal, and oncological interventions. Germany’s strong medical-device manufacturing sector also contributes to technological development and clinical adoption. Growing use of minimally invasive procedures, image-guided surgery, surgical navigation, and hybrid operating rooms is expected to create continued opportunities for intraoperative imaging technologies across German hospitals and specialized surgical centers.
China Expanding Healthcare Capacity and Surgical Technology Adoption
China Intraoperative Imaging Market is expanding as the country increases healthcare infrastructure, modernizes hospitals, and adopts advanced surgical technologies. China has a population exceeding 1.4 billion, creating a large potential patient base for surgical and medical services. The country is also experiencing significant demographic aging, with people aged 65 years and above accounting for approximately 15.6% of the population in 2024. The growing prevalence of neurological, cardiovascular, orthopedic, and cancer-related conditions is increasing demand for complex surgical interventions. Healthcare institutions are progressively investing in advanced operating rooms equipped with C-arms, intraoperative CT, MRI, ultrasound, and surgical navigation systems. Government healthcare modernization initiatives and improvements in tertiary-care infrastructure are supporting this transition. Domestic medical-device manufacturers are also expanding their capabilities, while international companies continue to introduce advanced imaging technologies through partnerships and local market strategies. Increasing adoption of minimally invasive surgery, robotic-assisted procedures, and image-guided interventions is further strengthening demand. As hospitals focus on improving surgical precision, reducing complications, and expanding specialized treatment capacity, intraoperative imaging is expected to become increasingly integrated into China’s modern surgical ecosystem.
Saudi Arabia Healthcare Transformation Driving Advanced Surgical Imaging
Saudi Arabia Intraoperative Imaging Market is benefiting from significant healthcare modernization, hospital infrastructure investment, and the adoption of advanced medical technologies. Healthcare transformation under Saudi Vision 2030 is encouraging the development of modern hospitals, specialized medical centers, and technology-enabled clinical services. Saudi Arabia has a population of more than 35 million, while people aged 65 years and above represent a growing demographic segment, increasing the long-term requirement for orthopedic, cardiovascular, neurological, and oncology services. Intraoperative imaging systems such as C-arms, ultrasound, CT, and advanced surgical navigation technologies are increasingly relevant to hospitals performing complex and minimally invasive procedures. The country’s healthcare transformation is also encouraging greater use of digital health, artificial intelligence, robotics, and advanced operating-room technologies. Major hospitals and specialized centers are investing in equipment capable of providing real-time anatomical visualization and supporting image-guided surgery. Rising healthcare expenditure, increasing availability of specialized medical services, and efforts to improve clinical outcomes are creating favorable conditions for market development. Continued hospital modernization and technology-focused healthcare investments are expected to support intraoperative imaging adoption across Saudi Arabia.
Recent Developments in Intraoperative Imaging Market
- Real-time ultrasound imaging can be immediately integrated into surgical navigation processes during cranial surgeries because to a digital connection between GE HealthCare's bkActiv intraoperative ultrasound system and the Medtronic Stealth AXiS surgical navigation system, which was revealed in April 2026.
- The U.S. FDA has approved the Stealth AXiS surgical system for use in cranial and ear, nose, and throat (ENT) procedures, Medtronic announced in March 2026. This expands the system's indication beyond spine surgery and integrates robotics, surgical planning, and navigation for increased accuracy and real-time insights.
Intraoperative Imaging Market Types
Product
- C-Arms
- Ict
- Intraoperative Ultrasound
- iMRI
Application
- Neurosurgery
- Orthopedic Surgery
- ENT Surgery
End Use
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Others
Countries
North America
- United States
- Canada
Europe
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Turkey
Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Thailand
- Malaysia
- Indonesia
- New Zealand
Latin America
- Brazil
- Mexico
- Argentina
Middle East & Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
All the Key players have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- GE HealthCare
- Siemens Healthcare GmbH
- Medtronic plc
- Koninklijke Philips N.V.
- Canon Medical Systems Corporation
- Brainlab AG
- Ziehm Imaging GmbH
- NeuroLogica Corp.
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Product, Application, End Use and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.