Industrial Robotics Market Report by Segment Market, Segment Volume, Countries and Company Analysis 2026-2034
Buy NowIndustrial Robotics Market Size and Forecast
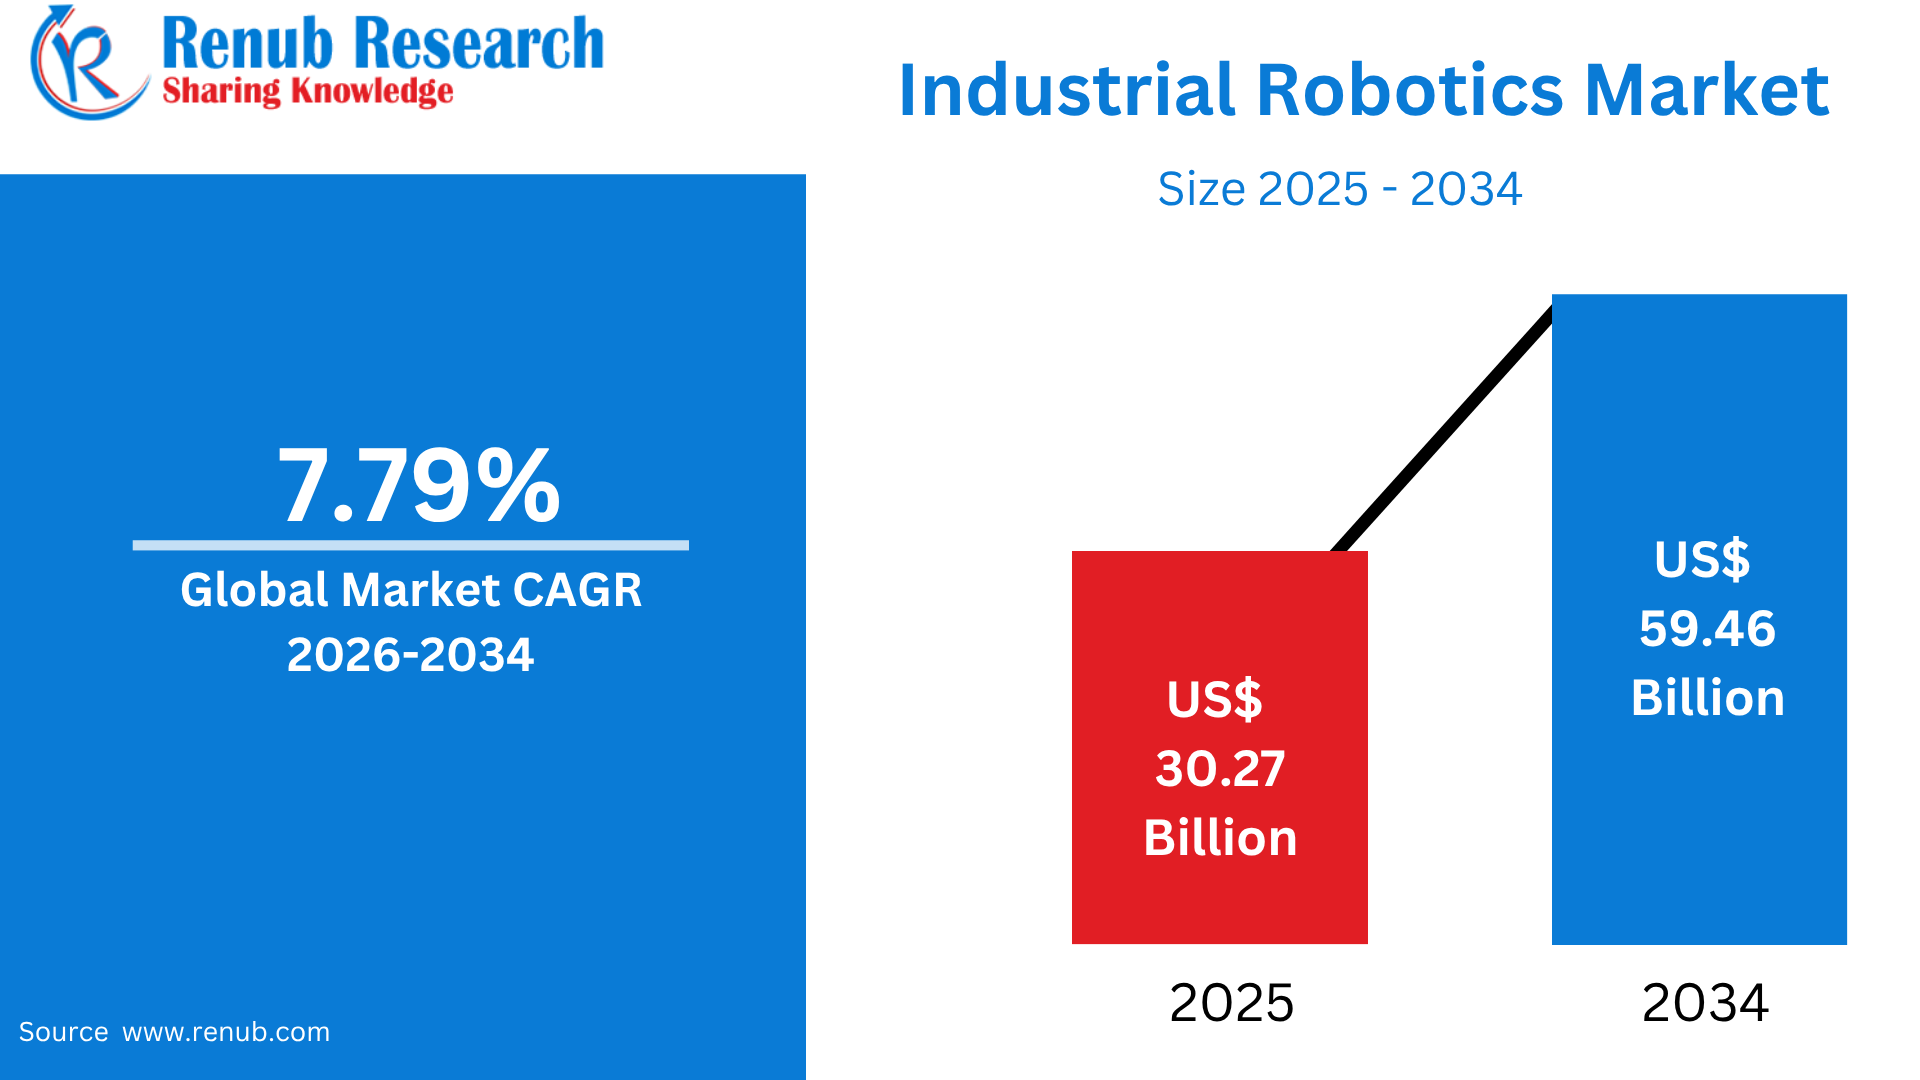
Industrial Robotics Market is projected to expand from US$ 30.27 billion in 2025 to US$ 59.46 billion by 2034, registering a CAGR of 7.79% during 2026–2034. Market growth is expected to be supported by the increasing demand for industrial automation, rapid advancements in robotics technologies, and the growing integration of robots across manufacturing and industrial applications. Manufacturers are increasingly adopting robotic solutions to improve operational efficiency, production accuracy, workplace safety, and overall productivity while addressing labor-related challenges.
What is Industrial Robotics and its Uses & Popularity Worldwide
Industrial robotics refers to the use of programmable robotic machines designed to perform manufacturing and industrial tasks with high levels of speed, precision, consistency, and repeatability. These systems include articulated robots, SCARA robots, delta robots, Cartesian robots, and collaborative robots, which can be integrated with machine vision, artificial intelligence, sensors, and automated production equipment.
Industrial robots are widely used for material handling, welding, assembly, painting, packaging, palletizing, machine tending, inspection, and quality control across automotive, electronics, metals, chemicals, food and beverage, pharmaceuticals, and other manufacturing industries. Their popularity is increasing as manufacturers seek to improve productivity, reduce production errors, address labor shortages, and create safer working environments. According to the International Federation of Robotics (IFR), 542,000 industrial robots were installed worldwide in 2024, more than twice the level recorded a decade earlier. The global operational stock reached approximately 4.66 million industrial robots, representing a 9% increase from the previous year. Asia accounted for 74% of new installations, demonstrating the growing global adoption of industrial automation.
China Emerges as the World’s Second-Largest Industrial Robot Exporter
China’s industrial robot exports reached US$8.03 billion in 2025, representing approximately 11% of global industrial robot exports. This enabled China to surpass Germany and become the world’s second-largest exporter of industrial robots, behind Japan. The development reflects China’s rapid expansion in manufacturing automation and its growing capabilities in robot production.
China’s domestic industrial automation market provides a major foundation for its global robotics expansion. Since 2021, China’s annual industrial robot installations have exceeded the combined installations of the rest of the world. By the end of 2024, China’s operational robot stock had exceeded 2 million units, approximately double the level recorded at the end of 2021.
Chinese industrial robot exports are increasingly moving toward Southeast Asian manufacturing markets. In 2025, approximately one-third of China’s robot exports by volume went to ASEAN countries, compared with 21% in 2024. The growth is associated with expanding manufacturing investment and the development of production facilities across Southeast Asia.
India represented approximately 15.7% of China’s industrial robot exports by volume in 2025, making it the largest individual destination. South Korea, Saudi Arabia, and Russia each accounted for around 5%, while Hungary represented approximately 3.7%. The distribution highlights the increasing importance of emerging and industrializing manufacturing markets for Chinese robotics suppliers.
The overseas expansion of Chinese electric vehicle, lithium battery, electronics, and photovoltaic manufacturers is creating additional demand for industrial robots. When Chinese manufacturers establish overseas production facilities, they often require automation equipment for welding, assembly, material handling, inspection, and other production processes. This creates a connection between China’s industrial-chain expansion and the international growth of its robotics exports.
China’s industrial robot market continued to expand in 2025, with domestic sales reaching approximately 334,000 units. The share of domestic proprietary robot brands increased to 54.2%, demonstrating the growing presence of Chinese manufacturers within their home market. Electronics represented the largest application industry, purchasing more than 70,000 robots during the year, followed by automotive components, metal products, batteries, complete vehicles, and food and beverage manufacturing.
Chinese industrial robots are increasingly being deployed across a broader range of manufacturing processes. Earlier adoption was concentrated in applications such as automotive welding and painting, while newer deployments include electronics assembly, battery manufacturing, logistics sorting, packaging, and other automated processes. This broader application base gives Chinese robotics manufacturers experience across multiple industries and creates more opportunities to replicate solutions in overseas markets.
China has developed a relatively comprehensive domestic supply chain for important industrial robot components, including harmonic reducers, servo motors, and controllers. These components were historically areas of significant dependence on foreign suppliers. Increasing domestic production and technological development have enabled Chinese robot manufacturers to improve their supply-chain resilience while moving toward more complex and higher-value applications.
The expansion of Chinese robotics is introducing another major supply source into the global industrial automation market. Chinese manufacturers combine a large domestic application base, rapid product iteration, extensive manufacturing capabilities, and competitive pricing. For emerging manufacturing centers in Southeast Asia, the Middle East, and India, Chinese robots can provide additional automation options as factories modernize their production systems.
China’s robotics industry is increasingly moving beyond the export of individual robotic machines toward broader automation solutions and services. Chinese manufacturers are developing overseas after-sales networks, engineering teams, and digital service capabilities to support international customers. The article identifies long-term challenges including core-component reliability, global service-network coverage, and geopolitical market fragmentation, which may influence the pace of international expansion.
Growth Driver in the Market
Rising Demand for Factory Automation and Productivity
The growing requirement for higher productivity, consistent product quality, and efficient manufacturing is a major driver of the industrial robotics market. Manufacturers are increasingly deploying robots to automate repetitive, hazardous, and precision-intensive operations while maintaining consistent production cycles. Industrial robots can operate continuously with high repeatability, making them particularly valuable for high-volume manufacturing environments such as automotive, electronics, metalworking, and consumer goods. The scale of adoption is reflected in global installation figures. According to IFR, 542,000 industrial robots were installed worldwide in 2024, marking the fourth consecutive year in which annual installations exceeded 500,000 units. The global operational stock also reached approximately 4.66 million units in 2024, up 9% year over year. Asia accounted for 74% of global new deployments, highlighting the importance of automation in rapidly industrializing manufacturing economies. As manufacturers modernize production lines and develop smart factories, demand for robotic welding, assembly, handling, inspection, and packaging solutions is expected to increase.
Labor Shortages and Demand for Automated Manufacturing
Labor shortages, rising workforce costs, and the need to maintain production capacity are encouraging manufacturers to adopt industrial robots. Robots can perform repetitive or physically demanding operations and help companies maintain production consistency when suitable workers are difficult to recruit or retain. This trend is particularly relevant in developed manufacturing economies facing demographic changes, as well as in emerging markets where manufacturers are seeking to expand production without proportionally increasing labor requirements. IFR reported that 4.66 million industrial robots were operating in factories worldwide in 2024, demonstrating the growing role of automation in industrial production. China alone accounted for 295,000 new industrial robot installations in 2024, representing 54% of global deployments, while Japan installed approximately 44,500 units. Robotics adoption is also expanding beyond traditional automotive applications into electronics, logistics-related manufacturing, food processing, pharmaceuticals, and other industries. Increasing pressure to maintain output while controlling labor-related costs is therefore expected to support continued investment in industrial automation.
Advancements in AI, Machine Vision, and Collaborative Robotics
Rapid technological development is expanding the capabilities and applications of industrial robots. Modern systems increasingly combine artificial intelligence, machine vision, advanced sensors, digital twins, cloud connectivity, and sophisticated motion-control technologies, enabling robots to perform more complex tasks with greater autonomy. Collaborative robots, or cobots, are also allowing automation to be introduced into environments where robots and human workers operate in closer proximity, subject to appropriate safety requirements. Machine vision enables robots to identify objects, inspect products, detect defects, and adapt to variations in production. AI-based systems can further improve decision-making, predictive maintenance, and process optimization. IFR’s 2025 data show that 542,000 industrial robots were installed globally in 2024, with annual installations remaining above 500,000 for the fourth consecutive year. The continuing integration of robotics with digital manufacturing technologies is expanding automation beyond conventional fixed production tasks. As manufacturers invest in smart factories and flexible production systems, technological innovation is expected to create new applications and support long-term industrial robotics market growth.
Challenges in the Market
High Initial Investment and Integration Costs
The substantial upfront investment required for industrial robotic systems remains a key challenge, particularly for small and medium-sized manufacturers. The total cost extends beyond the robot itself and can include end-of-arm tooling, machine vision, safety systems, controllers, software, integration, production-line modifications, employee training, and ongoing maintenance. Highly customized robotic cells can require significantly greater investment than standardized systems. For smaller companies operating with limited capital budgets, these costs can delay automation projects even when robotics could improve productivity over the longer term. The complexity of integration can also increase project timelines because robots must be synchronized with existing machinery, manufacturing execution systems, sensors, and safety infrastructure. Despite these barriers, global adoption remains substantial, with 542,000 industrial robots installed in 2024 and approximately 4.66 million robots in operation worldwide. Manufacturers therefore increasingly consider modular robotics, robotics-as-a-service, standardized platforms, and scalable automation solutions to reduce initial financial barriers. Nevertheless, capital expenditure and integration costs remain important considerations when companies evaluate automation investments.
Technical Complexity, Skills Gaps, and Safety Requirements
The increasing sophistication of industrial robots creates challenges related to technical skills, system integration, maintenance, cybersecurity, and workplace safety. Modern robotic installations can incorporate AI, machine vision, sensors, networking, cloud platforms, and advanced control software, requiring personnel with expertise in robotics engineering, programming, electrical systems, data management, and maintenance. A shortage of appropriately trained workers can make implementation and ongoing operation more difficult, particularly for smaller manufacturers. Safety is another important consideration because industrial robots can operate at high speeds and handle heavy components. Manufacturers must implement appropriate guarding, sensors, emergency systems, risk assessments, and safety procedures. The rapid growth of robotics makes these requirements increasingly significant: global operational industrial robot stock reached approximately 4.66 million units in 2024, up 9% year over year. Furthermore, interconnected robotic systems introduce cybersecurity and data-protection considerations. Addressing skills shortages, ensuring appropriate safety practices, and developing reliable integration capabilities will therefore remain essential for sustainable industrial robotics adoption.
Industrial Robotics Product Launches Worldwide
- Universal Robots UR15 Cobot – May 2025
Universal Robots introduced the UR15 collaborative robot at Automate 2025 in the United States. The robot offers a maximum tool-center-point speed of 5 meters per second and can deliver up to 30% faster pick-and-place cycle times compared with other Universal Robots models. It is designed for material handling, assembly, machine tending, and other high-speed industrial applications. - Universal Robots UR8 Long – September 2025
Universal Robots launched the UR8 Long collaborative robot with a reach of 1,750 mm and an 8 kg payload capacity. The robot is designed for complex welding, bin picking, and applications requiring extended reach. Its compact structure enables manufacturers to automate operations in restricted production spaces while maintaining flexibility and precision. - ABB IRB 6730S, IRB 6750S, and IRB 6760 – June 2025
ABB expanded its large industrial robot portfolio with three new models powered by the OmniCore controller platform. The IRB 6730S is designed for die-casting applications, while the IRB 6750S supports high-payload operations such as Giga Press manufacturing. The IRB 6750S offers payload capacity of up to 350 kg, supporting automotive and heavy industrial production. - Comau MyCo Collaborative Robot Family – June 2025
Comau launched the MyCo family of six collaborative robots at Automatica 2025 in Germany. The product range includes lightweight models with payload capacities from 3 kg to 15 kg. MyCo robots are designed for quick installation, simple programming, rapid redeployment, and operation in close proximity to workers. Target applications include assembly, packaging, machine tending, and material handling. - Kawasaki Robotics CL Series Cobots – September 2024
Kawasaki Robotics introduced its CL Series of intelligent collaborative robots at IMTS 2024 in the United States. The new cobots were developed for applications such as welding, machine tending, material removal, and general manufacturing. The series is intended to provide manufacturers with flexible automation solutions that combine industrial precision with collaborative operating capabilities. - ABB IRB 1200 Next-Generation Robot – 2025
ABB introduced a redesigned version of the IRB 1200 industrial robot for high-speed and high-precision applications. The new model is approximately 20% lighter and more compact than its predecessor. It is designed for assembly, polishing, dispensing, and electronics manufacturing, where space-efficient robotic cells and accurate repetitive movements are essential. - ABB PoWa Collaborative Robot Family – 2025–2026
ABB launched the PoWa collaborative robot family to address industrial applications requiring higher speed and payload capacity. The product family covers payloads ranging from 7 kg to 30 kg and offers speeds of up to 5.8 meters per second. PoWa robots are intended for pick-and-place, palletizing, machine tending, and other tasks in small and medium-sized factories as well as large manufacturing facilities. - DOBOT Atom Humanoid Robot – March 2025
DOBOT launched Atom, an embodied-intelligence humanoid robot designed to combine dexterous manipulation with autonomous movement. The robot features straight-knee walking and is intended to support the development of advanced industrial and commercial automation applications. Its introduction reflects the growing convergence of humanoid robotics, artificial intelligence, and flexible manufacturing technologies. - Hyundai MobED Autonomous Mobility Robot – December 2025
Hyundai Motor Group unveiled its production-ready MobED autonomous mobility robot platform at iREX 2025 in Japan. MobED uses AI-based autonomous navigation, LiDAR-camera sensor fusion, and an eccentric posture-control mechanism to move across uneven surfaces. The modular platform is designed for potential applications in logistics, delivery, research, video production, and industrial mobility. - MiR1200 Pallet Jack with AI-Powered Pallet Detection – 2024
Mobile Industrial Robots introduced the MiR1200 Pallet Jack, an autonomous mobile robot designed for pallet transportation and warehouse automation. Its AI-powered pallet-detection capability supports automated identification and handling of pallets in logistics environments. The product expands the use of mobile robotics in material movement, distribution centers, manufacturing plants, and automated warehousing operations.
Automotive Industrial Robotics Market
Automotive Industrial Robotics Market represents one of the largest application areas for industrial robots, driven by the need for high production speed, precision, consistency, and workplace safety. Automotive manufacturers use robots extensively for welding, painting, assembly, material handling, machine tending, inspection, and battery manufacturing. In 2024, the automotive industry accounted for approximately 23% of global industrial robot installations, with around 126,088 robots installed worldwide. Although installations declined from approximately 135,461 units in 2023, automotive remained the second-largest customer industry for industrial robotics globally. Robot adoption is particularly strong in vehicle body shops, powertrain manufacturing, component production, and increasingly in electric vehicle and battery plants. The transition toward electric and hybrid vehicles is creating additional automation requirements for battery-cell handling, module assembly, welding, and inspection. Automotive manufacturers are also integrating machine vision, artificial intelligence, digital twins, and collaborative robotics to improve production flexibility. In major automotive manufacturing economies, automation remains important for managing large production volumes, reducing process variability, and supporting increasingly complex vehicle architectures.
Electrical and Electronics Industrial Robotics Market
Electrical and Electronics Industrial Robotics Market is becoming a major contributor to global industrial automation as manufacturers seek greater precision, speed, miniaturization, and production flexibility. Robots are widely used for electronic component assembly, semiconductor handling, printed circuit board production, testing, inspection, packaging, and material movement. In 2024, the electrical and electronics industry accounted for about 24% of global industrial robot installations, making it the largest customer industry and representing approximately 128,899 newly installed robots. This was an increase from about 125,804 units in 2023. Demand is supported by the rapid expansion of consumer electronics, semiconductors, batteries, electrical equipment, and smart devices. Modern electronics manufacturing requires highly precise movements and repeatable processes, making robotic systems suitable for operations where human handling can create quality or contamination risks. The industry is also adopting machine vision, artificial intelligence, automated inspection, and high-speed pick-and-place systems. As manufacturers expand smart factories and automated production lines, robotics is expected to remain important for improving throughput, product quality, manufacturing consistency, and production scalability.
Metal and Machinery Industrial Robotics Market
Metal and Machinery Industrial Robotics Market covers robotic applications across metal processing, machinery manufacturing, fabrication, welding, machining, casting, material handling, and component production. The sector has become an increasingly important customer for industrial robots because manufacturers require greater productivity, precision, and consistency while managing physically demanding production processes. In 2024, the metal and machinery industry accounted for approximately 16% of global industrial robot installations, with around 88,777 robots installed, compared with 76,831 units in 2023. This represented a 16% year-over-year increase and established a new peak for installations in the sector. Between 2019 and 2024, robot installations in metal and machinery increased at an average annual rate of approximately 12%, demonstrating the sector’s growing adoption of automation. Robots are increasingly deployed for arc welding, spot welding, cutting, grinding, polishing, loading and unloading machines, and quality inspection. Small and medium-sized manufacturers are also adopting flexible robotic systems and collaborative robots to automate repetitive operations. Rising demand for precision components, industrial equipment, machinery, and fabricated metal products is expected to support continued robotics investment.
Food Industrial Robotics Market
Food Industrial Robotics Market is expanding as food manufacturers increasingly automate production, packaging, sorting, palletizing, inspection, and material-handling activities. Robots provide high-speed and consistent performance in environments where hygiene, product quality, labor availability, and operational efficiency are important considerations. In 2024, the food and beverage industry accounted for approximately 4% of global industrial robot installations, with about 20,792 robots installed worldwide, compared with 14,685 units in 2023. This represents an increase of roughly 42% year over year, indicating stronger adoption of automation within food-related manufacturing operations. Robotic systems are increasingly used for picking and placing products, primary and secondary packaging, case packing, palletizing, depalletizing, sorting, and quality inspection. Machine vision and advanced sensing technologies allow robots to handle products with different shapes, sizes, and packaging formats. The growth of processed foods, ready-to-eat products, packaged beverages, frozen foods, and e-commerce-oriented packaging is creating additional automation requirements. Furthermore, labor shortages and the need for consistent hygiene standards are encouraging food manufacturers to integrate robotics into high-volume production and packaging lines.
Strong Automation Adoption Across Manufacturing in United States
United States Industrial Robotics Market is supported by widespread automation across automotive, electrical and electronics, metal and machinery, food, logistics, and other manufacturing industries. The United States remains one of the world’s largest industrial robotics markets, accounting for approximately 6% of global robot installations in 2024. According to industry data, 34,200 industrial robots were installed in the United States in 2024, representing a 9% decline from the previous year but approximately 30% above the level recorded a decade earlier. The country also had approximately 393,700 industrial robots in operational use in 2024, an increase of 3% year over year. Automotive manufacturing remains a major source of demand, with around 13,700 robots installed in the U.S. automotive industry in 2024, an increase of 10.7%. Demand is also expanding in food processing, electronics, metalworking, and general manufacturing as companies seek higher productivity, improved precision, labor efficiency, and greater production flexibility. Furthermore, the United States has numerous domestic robotics system integrators supporting manufacturers, while a substantial proportion of industrial robots are supplied by international manufacturers.
Germany Advanced Manufacturing and High Robot Density
Germany Industrial Robotics Market is characterized by advanced manufacturing capabilities, strong automotive production, and extensive adoption of factory automation. Germany is the largest industrial robotics market in Europe and the fifth-largest worldwide. In 2024, approximately 26,982 industrial robots were installed in Germany, representing a 5% decline from 2023 but still the country’s second-highest annual installation level. Germany accounted for approximately 32% of all industrial robot installations in Europe during the year. The country’s industrial automation ecosystem is strongly supported by automotive manufacturing, machinery production, electrical and electronics, metalworking, and other engineering-intensive industries. Germany also recorded a robot density of approximately 449 robots per 10,000 manufacturing employees in 2024, placing it among the world’s most highly automated manufacturing economies. The increasing adoption of smart factories, artificial intelligence, machine vision, collaborative robots, and connected production systems is supporting further technological development. Automotive manufacturers and industrial equipment producers are particularly focused on flexible automation to improve production efficiency, quality, and responsiveness while addressing labor and skills shortages.
China World’s Largest Market for Industrial Robots
China Industrial Robotics Market is the world’s largest and continues to expand through extensive manufacturing automation, government-supported industrial modernization, and strong demand from major manufacturing sectors. China accounted for approximately 54% of global industrial robot installations in 2024, with around 295,000 robots installed, representing a 7% year-over-year increase and the highest annual installation level recorded in the country. China’s operational industrial robot stock exceeded 2 million units in 2024, making it the largest installed base globally. The country’s robotics demand is supported by its enormous automotive, electrical and electronics, metal and machinery, battery, semiconductor, and consumer goods manufacturing industries. Domestic robotics manufacturers are also becoming increasingly important; Chinese suppliers achieved approximately 57% of their domestic market in 2024, compared with around 28% a decade earlier. The expansion of electric vehicle production, battery manufacturing, electronics assembly, and smart factories is generating additional requirements for automated welding, assembly, material handling, inspection, and machine tending. Continued investment in advanced manufacturing and intelligent production is expected to sustain substantial demand for industrial robotics in China.
UAE Automation Supporting Industrial Diversification
United Arab Emirates Industrial Robotics Market is developing as the country expands advanced manufacturing, logistics, food processing, metals, automotive-related activities, and other technology-intensive industries. Industrial robotics is increasingly relevant to the UAE’s efforts to improve manufacturing productivity, introduce smart-factory technologies, and reduce dependence on labor-intensive production processes. While the UAE does not have the installation scale of major robotics markets such as China, the United States, or Germany, opportunities are emerging through investments in industrial automation, artificial intelligence, digital manufacturing, and advanced logistics infrastructure. The country’s strategic focus on manufacturing and technological development is encouraging businesses to adopt robotic systems for assembly, welding, material handling, packaging, palletizing, inspection, and warehouse operations. The wider Middle East and Africa region installed approximately 5,900 industrial robots in 2024, providing a broader indication of the developing regional automation ecosystem. Demand in the UAE is also supported by food and beverage manufacturing, metals, petrochemicals, construction-related manufacturing, and logistics. Increasing investment in smart industrial facilities and Industry 4.0 technologies is expected to create additional opportunities for industrial robotics adoption.
Asia, Europe and the Americas - overview
- China is by far the world’s largest market in 2024, representing 54% of global deployments. The latest figures show that 295,000 industrial robots have been installed - the highest annual total on record. For the first time, Chinese manufacturers have sold more than foreign suppliers in their home country. Their domestic market share climbed to 57% last year, up from about 28% over the past decade. China’s operational robot stock exceeded the 2 million mark in 2024, the largest of any country. As robotics in China is opening up new markets, there is no indication that robot demand in China will decrease. There is still a lot of potential in Chinese manufacturing for 10% growth on average each year until 2028.
- Japan maintained its position as the second-largest market for industrial robots, with 44,500 units installed in 2024 – a slight 4% decrease. The country's operational stock rose by 3%, with 450,500 units now in use. Demand for robots will grow slightly by lower single-digit rates in 2025. It will then accelerate to a medium single-digit rate on average in the next few years.
- The market in the Republic of Korea installed 30,600 units in 2024 – down 3%. Annual installations had been trending sideways of around 31,000 units since 2019. The country is the fourth largest robot market in the world in terms of annual installations in 2024, after the United States, Japan, and China.
- India continues to grow with a record of 9,100 units installed in 2024 – up 7%. The automotive industry was the strongest driver with a market share of 45%. In terms of annual installations, India ranks sixth worldwide, one place up behind Germany.
Industrial Robotics Market Segments
Industrial Robotics Market & Volume
- Automotive Industry and Forecast
- Electrical and Electronics Industry and Forecast
- Metal and Machinery Industry and Forecast
- Plastic and Chemical Products
- Food Industry and Forecast
- Others
Countries
America
- United States
- Canada
- Mexico
- Others
Europe
- France
- Germany
- Italy
- Spain
- Others
Asia Pacific
- China
- India
- Japan
- Republic of Korea
- Thailand
- Others
Rest of the World
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Company Analysis:
- KUKA
- iRobot Corporation
- Intuitive Surgical, Inc.
- Panasonic Corporation
- Fanuc
- ABB Ltd
- Stryker Corporation
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Segment and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.