Europe Anticoagulants Market Report by Drug Class, Route of Administration, Distribution Channel, Application, Countries and Companies Analysis 2026-2034
Buy NowEurope Anticoagulants Market Size and Forecast
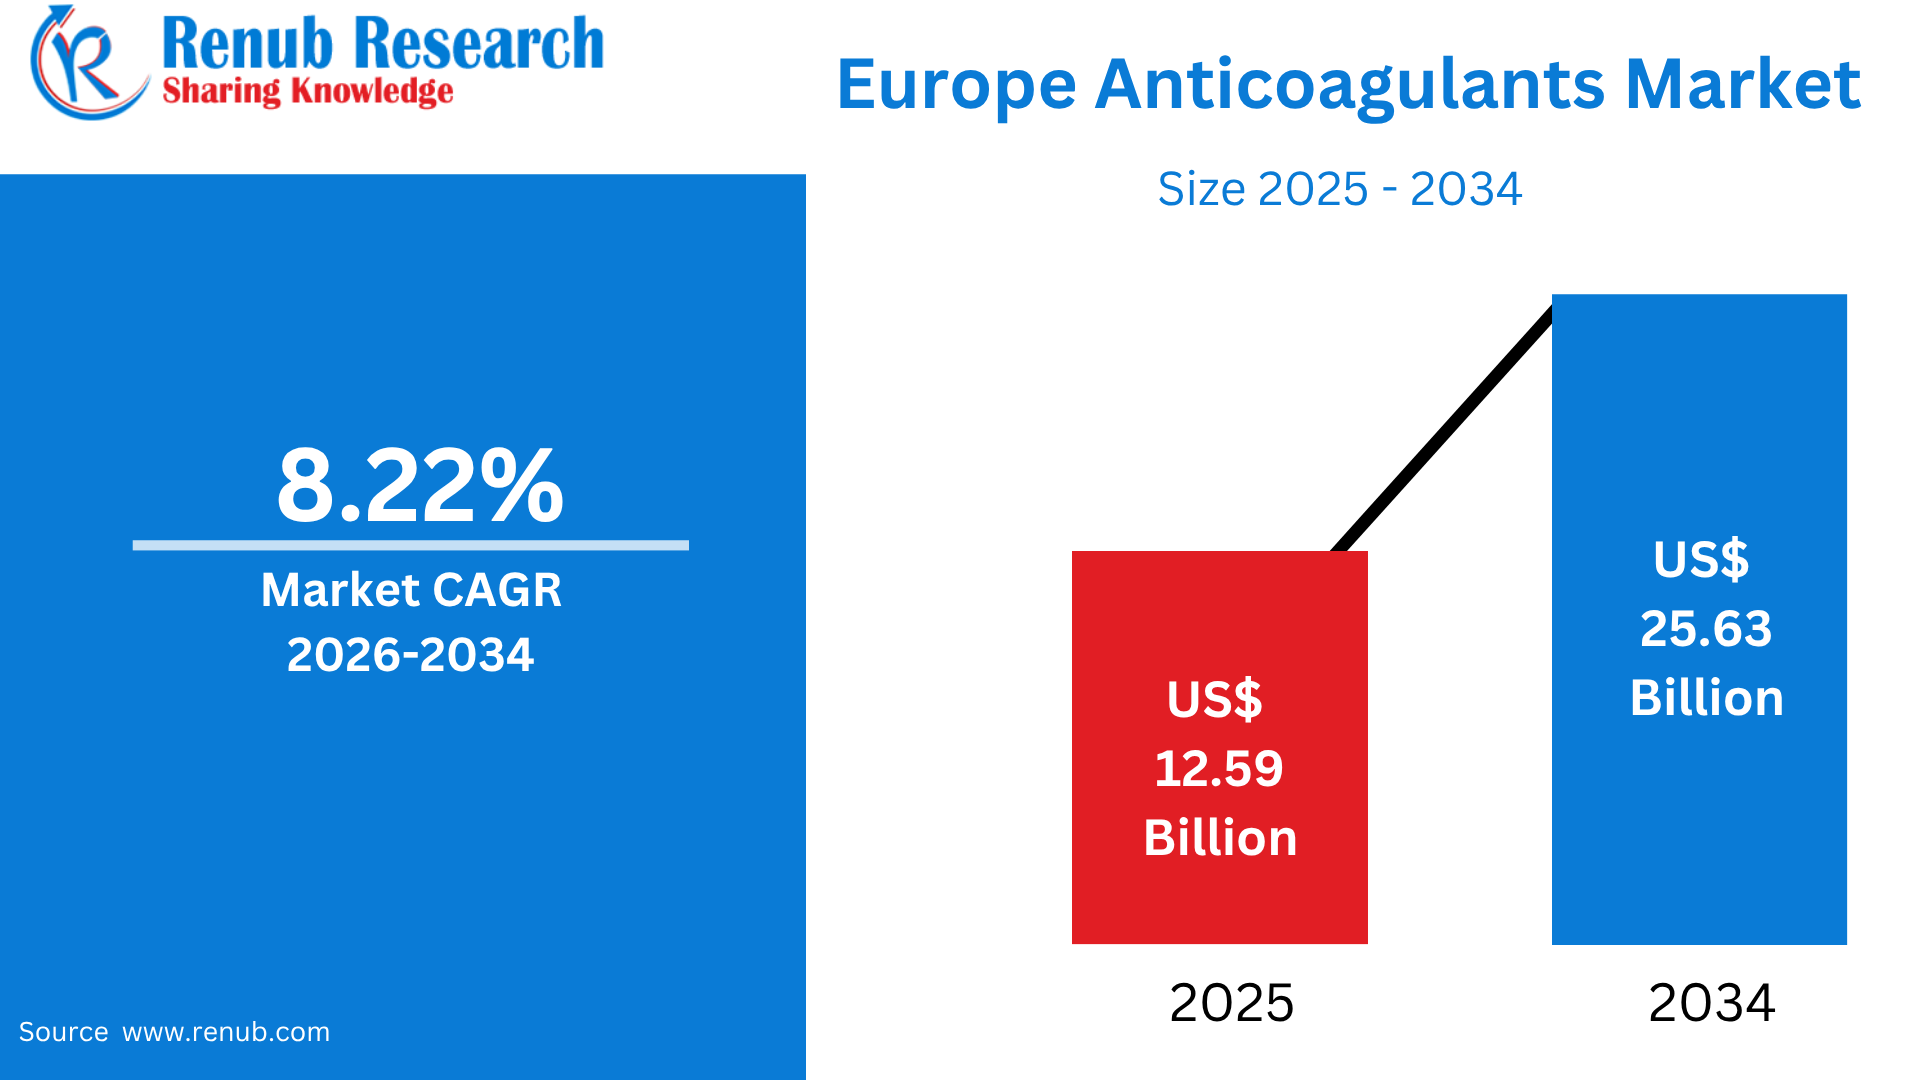
The Europe Anticoagulants Market is projected to expand from US$ 12.59 billion in 2025 to US$ 25.63 billion by 2034, registering a CAGR of 8.22% during 2026–2034. The market is expected to grow steadily as the prevalence of cardiovascular and thromboembolic disorders increases across the region. Atrial fibrillation, deep vein thrombosis (DVT), pulmonary embolism, and ischemic stroke remain important clinical indications driving demand for anticoagulant therap
What are Anticoagulants? Uses & Popularity in Europe
Anticoagulants are medicines that reduce the blood’s ability to form harmful clots. They are commonly known as “blood thinners,” although they do not actually thin the blood. Anticoagulants work by interfering with specific proteins or factors involved in the blood-clotting process. Major classes include vitamin K antagonists such as warfarin, heparins, and newer direct oral anticoagulants (DOACs), including apixaban, rivaroxaban, and dabigatran. In Europe, anticoagulants are widely used to prevent and treat deep vein thrombosis (DVT), pulmonary embolism (PE), venous thromboembolism (VTE), and stroke associated with non-valvular atrial fibrillation (AF).
Their popularity is increasing as Europe faces an aging population and a growing cardiovascular disease burden. An EU study estimated that AF affected approximately 8.8 million adults aged over 55 in 2010, with the number projected to reach 17.9 million by 2060. The availability of convenient oral therapies, expanding diagnosis, and improved clinical evidence have further strengthened anticoagulant adoption across European healthcare systems.
Increase in the Share of Population Aged 65 Years and Over, 2015–2025
- Albania (AL): The share of the population aged 65 years and over increased by 8.8 percentage points, the highest increase among the listed European countries.
- North Macedonia (MK): The 65+ population share increased by 5.9 percentage points, highlighting a significant shift toward an older population structure.
- Poland (PL): The proportion of people aged 65+ rose by 5.6 percentage points, reflecting rapid population aging.
- Romania (RO): The share of the population aged 65 and over increased by 4.7 percentage points during 2015–2025.
- Serbia (RS): Serbia recorded a 4.2-percentage-point increase in its 65+ population share.
- Slovakia (SK): The share of people aged 65+ also increased by 4.2 percentage points, indicating continued demographic aging.
- Croatia (HR): Croatia experienced a 3.8-percentage-point increase in the share of its population aged 65 years and over.
- Cyprus (CY): The proportion of people aged 65+ increased by 3.7 percentage points between 2015 and 2025.
- Italy (IT): Italy recorded a 3.7-percentage-point increase, reinforcing its position among Europe’s rapidly aging populations.
- France (FR): The share of the population aged 65 years and over increased by 3.5 percentage points over the period.
Source: Eurostat
Growth Drivers of the Europe Anticoagulants Market
Rising Prevalence of Atrial Fibrillation and Thromboembolic Disorders
The growing burden of atrial fibrillation (AF), venous thromboembolism, deep vein thrombosis, and pulmonary embolism is a major driver of the European anticoagulants market. AF is particularly important because it substantially increases the risk of ischemic stroke and systemic embolism, creating sustained demand for long-term anticoagulation. A European Union projection estimated that the number of adults aged over 55 with AF could increase from 8.8 million in 2010 to 17.9 million by 2060, representing more than a twofold increase. The same analysis projected that AF among people aged over 75 would rise from 5.6 million to 13.8 million over the period. As cardiovascular risk factors and the elderly population expand, more patients require long-term prevention of stroke and recurrent blood clots. Anticoagulants such as apixaban, rivaroxaban, and dabigatran are approved in Europe for stroke prevention in eligible patients with non-valvular AF, as well as for treating DVT and PE. Consequently, the increasing diagnosis and management of thromboembolic conditions are expected to sustain demand for anticoagulant therapies.
Increasing Adoption of Direct Oral Anticoagulants (DOACs)
The shift toward direct oral anticoagulants (DOACs) is another important growth driver for the Europe anticoagulants market. Drugs such as apixaban, rivaroxaban, and dabigatran provide oral treatment options for patients with several thromboembolic conditions and have expanded the therapeutic alternatives available to physicians. Unlike traditional vitamin K antagonists such as warfarin, DOACs directly target specific clotting factors and generally offer simpler treatment pathways. The European Medicines Agency has authorized these medicines for indications including stroke prevention in non-valvular AF and treatment and prevention of recurrent DVT and PE. Clinical evidence is also supporting their continued utilization. The OECD reports that DOACs provide important cardiovascular benefits in patients with non-valvular AF and VTE, with several agents demonstrating non-inferior or superior efficacy compared with warfarin for stroke prevention. A frequently cited advantage is a lower risk of intracranial hemorrhage compared with standard warfarin therapy. The convenience of oral administration, expanding clinical experience, and availability of multiple branded and generic products are expected to encourage continued DOAC adoption across European healthcare systems.
Aging Population and Expansion of Cardiovascular Healthcare
Europe’s demographic aging is creating a larger patient population vulnerable to cardiovascular and thromboembolic diseases, supporting long-term demand for anticoagulants. Age is a major risk factor for atrial fibrillation and other cardiovascular disorders. Research on AF prevalence found that it rises sharply among older adults: prevalence reached 24.2% among men and 16.1% among women aged over 85 in the underlying European population study. At the same time, improvements in cardiovascular screening, diagnostic capabilities, hospital infrastructure, and access to specialist care are helping identify patients who require anticoagulation earlier and more consistently. European healthcare systems increasingly emphasize prevention of stroke and recurrent thromboembolic events, creating opportunities for both established and newer anticoagulant therapies. The EMA lists anticoagulants such as Eliquis and Xarelto for prevention of stroke and systemic embolism in appropriate patients with non-valvular AF and for treatment and prevention of recurrent VTE. Furthermore, broader availability of generic anticoagulants can improve affordability and treatment access. Together, demographic aging, greater disease awareness, improved diagnosis, and expanding cardiovascular-care capacity are supporting the long-term development of the European anticoagulants market.
Challenges of the Europe Anticoagulants Market
Risk of Bleeding and Safety Concerns
The risk of bleeding remains one of the most significant challenges for the Europe anticoagulants market. Because anticoagulants intentionally reduce the body’s ability to form clots, patients can experience bleeding complications, particularly when therapy is not appropriately dosed or when multiple medicines interact. The concern is especially important among older patients, who frequently require anticoagulation because of AF but may also have multiple chronic conditions and take several medications simultaneously. An EMA-funded real-world study covering Denmark, France, Germany, Spain, the Netherlands, and the United Kingdom evaluated serious bleeding associated with direct oral anticoagulants including apixaban, dabigatran, and rivaroxaban. The EMA concluded that the observed pattern of serious bleeding was consistent with clinical-trial expectations but highlighted an increased risk of bleeding among patients older than 75 years. These safety considerations require appropriate patient selection, dose adjustment, monitoring of relevant clinical factors, and education about drug interactions. Concerns surrounding bleeding can influence prescribing decisions and patient adherence, creating a continuing challenge for market expansion despite the clinical benefits of anticoagulation.
Treatment Adherence, Monitoring and Healthcare-System Differences
Differences in healthcare systems, reimbursement policies, clinical practices, and patient adherence across European countries can create challenges for anticoagulant market development. Although DOACs have simplified anticoagulation compared with traditional vitamin K antagonists, treatment still requires appropriate prescribing, adherence, assessment of renal function and other patient-specific factors, and consideration of potential drug interactions. This becomes increasingly important as anticoagulants are prescribed to older patients with multiple medical conditions. The EMA’s review of DOAC use across six European countries found no robust evidence of a high level of non-adherence to authorized product information, but it also emphasized the need to consider safety issues and appropriate use, particularly among older patients. Meanwhile, European countries differ in healthcare budgets, reimbursement arrangements, prescribing guidelines, and access to specialist care. These differences can lead to variations in the uptake of newer anticoagulants and generic alternatives. Cost pressures are another consideration because long-term anticoagulant therapy can represent a substantial expenditure for healthcare systems. Maintaining affordability while ensuring access to effective therapies, appropriate patient monitoring, and consistent treatment practices remains an important challenge for market participants across Europe.
Anticoagulant Product Launches in Europe
1.Daxanlo – Dabigatran | 2023
- Company: KRKA
- Launch: First marketed in Europe in 2023.
- Active ingredient: Dabigatran etexilate.
- Category: Direct thrombin inhibitor.
- Significance: Added a generic alternative to Pradaxa for anticoagulation.
- KRKA subsequently expanded Daxanlo into Serbia, Greece, Montenegro, and the UK in 2025.
2.Generic Apixaban – Portugal | September 2023
- Launch: Generic apixaban versions were introduced in Portugal in September 2023.
- Application: Stroke and systemic embolism prevention in eligible AF patients and treatment/prevention of recurrent DVT and PE.
- Market impact: Generic competition significantly increased during 2023–2024.
- By the final quarter of the study period, 84% of apixaban pills sold in Portugal were generic, demonstrating rapid uptake.
3.Dabigatran Generics – Portugal | January 2024
- Launch: Generic dabigatran products entered the Portuguese market in January 2024.
- Active ingredient: Dabigatran etexilate.
- Category: Direct thrombin inhibitor.
- Market impact: Generics contributed to lower treatment costs and increased competition.
- Generic NOACs accounted for 33.2% of total NOAC pills sold in Portugal during the July 2023–June 2024 study period.
4.Rivaroxaban Generics – Portugal | April 2024
- Launch: Generic rivaroxaban was introduced in Portugal in April 2024.
- Category: Direct factor Xa inhibitor.
- Indications: Includes prevention of stroke/systemic embolism in non-valvular AF and treatment/prevention of recurrent DVT and PE.
- Market impact: The launch followed increasing availability of generic rivaroxaban across Europe after patent expiry.
5.Rivaroxaban Viatris – European Expansion | 2025
- Company: Viatris
- Product: Rivaroxaban Viatris, previously Rivaroxaban Mylan.
- 2025 development: The product’s EMA documentation was updated in 2025–2026, while Viatris continued commercialization of the generic anticoagulant.
- Active ingredient: Rivaroxaban.
- Category: Factor Xa inhibitor.
- European relevance: Provides a generic alternative to Xarelto.
6.Xerdoxo – Rivaroxaban | France & Ireland, 2025
- Company: KRKA
- Launch/rollout: KRKA expanded Xerdoxo into France and Ireland in 2025.
- Active ingredient: Rivaroxaban.
- Category: Direct factor Xa inhibitor.
- Significance: Strengthened generic competition in major Western European anticoagulant markets.
- KRKA reported that Xerdoxo had originally been rolled out in 2020 and expanded into additional markets in 2025.
7.Aboxoma – Apixaban | UK & Other European Markets, 2025
- Company: KRKA
- Launch/rollout: Aboxoma was rolled out in the United Kingdom, Montenegro, and Bosnia and Herzegovina in 2025.
- Active ingredient: Apixaban.
- Category: Direct factor Xa inhibitor.
- Significance: Expanded availability of generic apixaban in European markets.
- The product competes in a rapidly expanding generic segment where NHS England identifies generic apixaban as one of the best-value DOAC options.
8.Delianda – Edoxaban | Europe, 2025
- Company: KRKA
- Launch/rollout: Delianda was introduced in nine markets in 2025, including Romania and Iceland.
- Active ingredient: Edoxaban.
- Category: Direct factor Xa inhibitor.
- Significance: KRKA reported entering Slovenia, Bulgaria, and Croatia as the first provider of a generic edoxaban in those markets.
- Edoxaban is used for stroke/systemic embolism prevention in eligible AF patients and for DVT/PE treatment and recurrence prevention.
9.Generic Rivaroxaban – UK Market Expansion
- Launch driver: Rivaroxaban generics became increasingly available in the UK following Xarelto’s patent expiry in April 2024.
- Market significance: The patent expiry enabled significantly lower acquisition costs compared with the branded product.
- NHS procurement: By September 2024, generic rivaroxaban was ranked among the best-value DOAC options for appropriate AF patients.
- This development accelerated price competition and expanded access to oral anticoagulation.
10.Generic NOAC Expansion – Europe
- Products involved: Generic apixaban, rivaroxaban, dabigatran, and edoxaban.
- Market trend: European anticoagulant markets increasingly shifted toward lower-cost generic NOACs.
- A 2026 real-world European analysis covering 113,473 patients with non-valvular AF across the UK, Germany, Italy, and Spain found apixaban accounted for 57.4% of DOAC initiations, followed by rivaroxaban at 20.4%, edoxaban at 19.0%, and dabigatran at 3.1%.
Rising Adoption of Direct Oral Anticoagulants
Europe Novel Oral Anticoagulants (NOACs), also known as direct oral anticoagulants (DOACs), market is expanding as healthcare systems increasingly shift from vitamin K antagonists (VKAs) toward newer therapies for stroke and thromboembolism prevention. NOACs include factor Xa inhibitors such as apixaban, rivaroxaban, and edoxaban, as well as the direct thrombin inhibitor dabigatran. Their predictable pharmacological effects, fixed-dose regimens, fewer food interactions, and reduced requirement for routine coagulation monitoring have strengthened their position in clinical practice. A 2026 European real-world study covering 113,473 patients with atrial fibrillation across the UK, Germany, Italy, and Spain found that apixaban accounted for 57.4% of DOAC initiations, followed by rivaroxaban at 20.4%, edoxaban at 19.0%, and dabigatran at 3.1%. The average patient age was approximately 75 years, highlighting the strong relationship between NOAC demand and Europe’s aging population. Atrial fibrillation (AF) remains a major demand driver for anticoagulant therapy because of its association with ischemic stroke and systemic embolism. AF prevalence is particularly high in Europe, with European and North American populations reporting age- and sex-standardized prevalence levels of approximately 270–360 cases per 100,000 people in multinational research. Europe’s aging demographic profile further strengthens the opportunity for anticoagulants. The EU median age reached 44.7 years in 2024, increasing by 5.4 years from 2004, reflecting a steadily aging population. European anticoagulation landscape continues to move toward NOACs because of their convenience and established role in stroke prevention among eligible patients with non-valvular AF. Real-world European evidence continues to evaluate apixaban, rivaroxaban, edoxaban, and dabigatran across different patient populations, supporting greater evidence-based utilization. However, bleeding risk, renal-function considerations, appropriate dose selection, medication adherence, and reimbursement policies remain important factors influencing treatment decisions.
Continued Role of Warfarin and Other VKAs
Europe Vitamin K Anticoagulants market continues to represent an important part of anticoagulation therapy despite the rapid adoption of NOACs. Warfarin and other vitamin K antagonists (VKAs) remain clinically relevant for selected patients, particularly those for whom NOACs are unsuitable or contraindicated. VKAs have decades of clinical experience and remain an established treatment option across European healthcare systems. VKAs remain particularly important in patients requiring anticoagulation for certain mechanical heart valves, where NOACs are generally not recommended. Their established efficacy and relatively low drug acquisition costs also support continued use in cost-sensitive healthcare environments. However, VKAs require regular INR monitoring, dose adjustments, and management of interactions with food and other medicines. These disadvantages have contributed to the gradual shift toward DOACs where clinically appropriate. European registry evidence describes this transition as a major change in AF stroke-prevention practice, with patients increasingly moving from VKA-based regimens toward factor Xa and direct thrombin inhibitors. The principal challenge for VKAs is the increasing preference for DOACs because of their simpler dosing and reduced monitoring burden. Nevertheless, VKAs are expected to maintain a stable niche because anticoagulation therapy must be individualized according to the patient’s diagnosis, renal function, bleeding risk, comorbidities, and type of cardiovascular condition.
Increasing Demand for Long-Term Stroke Prevention
The Europe Oral Anticoagulants market is growing as the prevalence of atrial fibrillation, venous thromboembolism, and other thromboembolic conditions increases. Oral anticoagulants include both DOACs and vitamin K antagonists, providing physicians with multiple options for preventing and treating blood-clot-related complications. AF is particularly important because anticoagulation is a central component of stroke prevention for patients with sufficient thromboembolic risk. DOACs have become increasingly prominent because they eliminate many of the practical limitations associated with traditional VKAs. Evidence from large real-world populations illustrates the scale of this transition. A European study published in 2026 analyzed more than 113,000 AF patients initiating a DOAC in the UK, Germany, Italy, and Spain, demonstrating substantial utilization of apixaban, rivaroxaban, edoxaban, and dabigatran. Demographic aging is another structural growth factor. The EU median age increased from 39.3 years in 2004 to 44.7 years in 2024, while Italy recorded the highest median age among EU countries at 48.7 years. Since AF and thromboembolic disorders become more common with advancing age, this demographic shift is expected to sustain demand for oral anticoagulation.
Hospitals Remain Major Treatment Centers
Hospitals represent a critical end-user segment for anticoagulants because they manage patients requiring acute anticoagulation, perioperative treatment, cardiovascular procedures, and treatment of conditions such as deep vein thrombosis (DVT), pulmonary embolism (PE), and atrial fibrillation. Anticoagulants may be initiated or adjusted in emergency departments, cardiology units, intensive-care settings, surgical departments, and inpatient wards. The increasing number of cardiovascular interventions, orthopedic procedures, and high-risk hospitalized patients creates continued demand for anticoagulation. Hospitals also play an important role in assessing bleeding risk, renal function, drug interactions, and appropriate dosing before patients transition to longer-term outpatient therapy. The growing availability of DOACs is changing hospital anticoagulation pathways. European real-world evidence shows substantial use of apixaban, rivaroxaban, edoxaban, and dabigatran among AF patients. In a 2026 multinational cohort, the mean age of DOAC users was approximately 75 years, emphasizing the importance of hospital and specialist services in managing anticoagulation among older adults.
France Large Atrial Fibrillation Patient Base
France represents an important European market for anticoagulants because of its substantial AF burden and well-developed healthcare infrastructure. Santé publique France estimated that approximately 2.03 million people had atrial fibrillation or atrial flutter among the population alive on January 1, 2023, based on national health-data records involving hospitalization and long-term disease coverage. Historical national data also demonstrate the expanding role of oral anticoagulants. In 2018, 225,747 newly treated patients with AF receiving oral anticoagulation were identified in France, corresponding to a standardized rate of 410 per 100,000 inhabitants. The rate had increased substantially from 295 per 100,000 in 2010, with the introduction of direct oral anticoagulants contributing to broader treatment of AF patients. French healthcare guidance recognizes both VKAs and direct oral anticoagulants—including dabigatran, rivaroxaban, and apixaban—as anticoagulation options for appropriate AF patients. Reduced monitoring requirements and easier administration continue to support DOAC utilization, although bleeding risk, drug interactions, renal function, and reimbursement remain important considerations.
United Kingdom High Prevalence of Atrial Fibrillation
The United Kingdom has a substantial anticoagulant treatment population. NHS England reports that approximately 1.5 million people in England live with atrial fibrillation, while AF is associated with around one in five strokes. This creates significant demand for long-term anticoagulation and stroke-prevention therapies. The NHS has actively promoted DOAC utilization for eligible AF patients. By 2023, 90% of high-stroke-risk AF patients were receiving treatment, six years ahead of the original 2029 target. The NHS also reported that the accelerated DOAC rollout generated more than £100 million in medicine-cost savings, supported by national procurement arrangements. The UK market is also benefiting from programs designed to improve AF detection and treatment. In 2024, NHS England reported that approximately 1 million people with AF had been prescribed anticoagulant medication during the previous year, and estimated that 1,200 strokes were avoided between 2023 and 2024. These initiatives are strengthening demand for anticoagulants while improving treatment coverage among high-risk patients.
Germany Strong Healthcare Infrastructure and Aging Population
Germany is one of Europe’s major pharmaceutical and healthcare markets, providing a strong environment for anticoagulant demand. The country has a large and aging patient population, while cardiovascular diseases and AF remain important drivers of anticoagulation therapy. The broader European demographic trend is particularly relevant, with the EU median age reaching 44.7 years in 2024. Germany has experienced the broader European transition from VKAs toward DOAC-based anticoagulation. Real-world European evidence covering Germany, the UK, Italy, and Spain included 113,473 patients with non-valvular AF who initiated a DOAC between 2016 and 2024. Apixaban represented 57.4% of the cohort, while rivaroxaban accounted for 20.4%, edoxaban 19.0%, and dabigatran 3.1%. Despite the advantages of DOACs, bleeding risk and correct dose selection remain important clinical considerations. European research has highlighted concerns around inappropriate DOAC dosing and its potential association with poorer outcomes, reinforcing the importance of individualized treatment and ongoing clinical monitoring.
Spain Aging Population Drives Anticoagulation Demand
Spain represents another significant European market for anticoagulants, supported by its aging population and increasing burden of cardiovascular conditions. The median age in Spain has increased substantially over the past decade, reflecting the broader demographic shift across Europe. The EU median age reached 44.7 years in 2024, while Spain was among the countries where median age increased by 3.8 years between 2014 and 2024. DOACs are increasingly important in Spain because of their convenient dosing and reduced need for routine coagulation monitoring compared with VKAs. A large 2026 real-world analysis specifically covering Spain, Germany, Italy, and the UK evaluated 113,473 patients initiating DOAC therapy for non-valvular AF, providing evidence of substantial real-world adoption across these markets. Spain’s anticoagulant market is also supported by efforts to improve AF diagnosis and stroke prevention. However, treatment decisions continue to be influenced by bleeding risk, renal function, appropriate dose selection, healthcare access, and the cost of newer medicines. As AF prevalence rises with population aging and DOACs remain central to contemporary stroke-prevention strategies, Spain is expected to remain an important market for oral anticoagulation therapies.
Europe Anticoagulants Market Segmentation
Drug Class
- Novel Oral Anticoagulants (NOACs)
- Heparin and Low Molecular Weight Heparin (LMWH)
- Vitamin K Antagonist
- Others
Route of Administration
- Oral Anticoagulant
- Injectable Anticoagulant
Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Stores
- Others
Application
- Atrial Fibrillation and Heart Attack
- Stroke
- Deep Vein Thrombosis (DVT)
- Pulmonary Embolism (PE)
- Others
Countries
- France
- Germany
- Italy
- Spain
- United Kingdom
- Belgium
- Netherlands
- Russia
- Poland
- Greece
- Norway
- Romania
- Portugal
- Rest of Europe
All companies have been covered with 5 Viewpoints
- Overviews
- Key Person
- Recent Developments
- SWOT Analysis
- Revenue Analysis
Key Players Analysis
- Pfizer Inc.
- Alexion Pharmaceuticals Inc.
- Aspen Holdings
- Bayer AGS
- Sanofi
- Johnson & Johnson Private Limited
- Bristol-Myers Squibb Company
- Daiichi Sankyo Company Limited
Report Details:
| Report Features | Details |
| Base Year |
2025 |
| Historical Period |
2022 - 2025 |
| Forecast Period |
2026 - 2034 |
| Market |
US$ Billion |
| Segment Covered |
Drug Class, Route of Administration, Distribution Channel, Application and Countries |
| Countries Covered |
|
| Companies Covered |
|
| Customization Scope |
20% Free Customization |
| Post-Sale Analyst Support |
1 Year (52 Weeks) |
| Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on request) |
Customization Services available
- Analysis of Market Size and Its Segments
- More Company Profiles (Upto 10 without any additional cost):
- Additional Countries (Other than mentioned Countries):
- Region/Country Specific Reports:
- Market Entry Strategy:
- Region-Specific Market Dynamics:
- Regional Market Share Analysis:
- Trade Analysis:
- Production Insights:
- Others Customized Requests:
For more information contact our analysts.
Need More Assistance?
- Talk to our analysts to get more precious information on the current market trends.
- Include more countries and segments and customize the report based on the final requirement.
- Get a competitive advantage in your industry by knowing the report findings and making a positive impact on your revenues and operations.
- Our analysts are always ready to provide more help and pertinent information if you need any additional assistance.